What is the Single-Mode Optical Transceiver Market Size and Growth Rate?
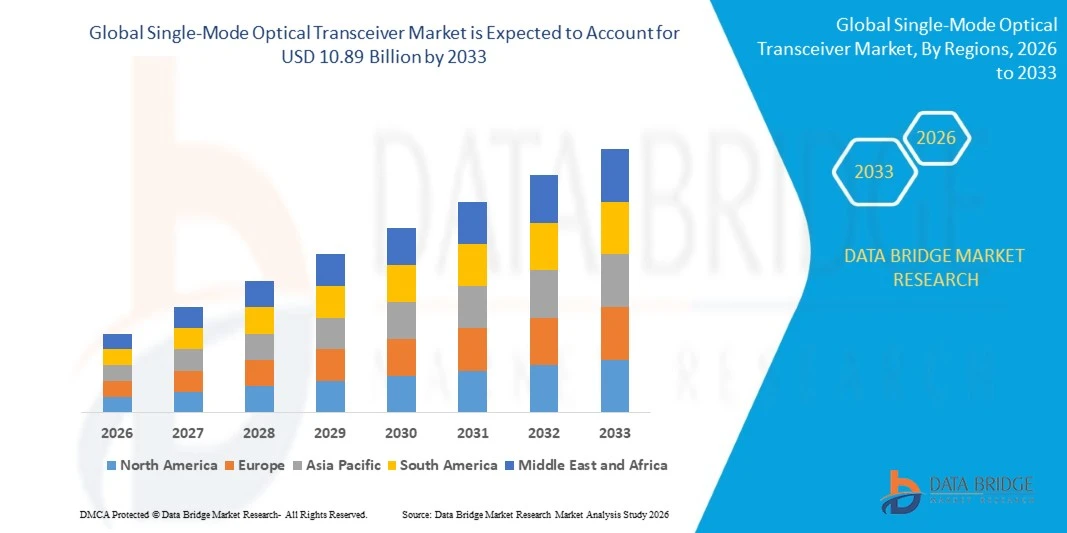
- As per Data Bridge Market Research analysis, the single-mode optical transceiver market was valued at USD 5.08 billion in 2025 and is projected to reach USD 10.89 billion by 2033, growing at a CAGR of 10.00% from 2026 to 2033.
- The market is experiencing rapid growth driven by rising demand for high-bandwidth connectivity, increasing build-out of AI and cloud data centers, and expanding upgrades to 5G, fiber, and metro networks.
- The increasing shift toward 400G, 800G, and 1.6T links, silicon photonics, and energy-efficient pluggable optics, combined with growing demand for longer reach and lower latency, is supporting market adoption. Single-mode transceivers are being applied across data center interconnects, telecom backhaul, campus networks, and AI clusters, offering operators greater bandwidth and reach through single-mode optical transceivers, optical transceivers, and silicon photonics modules that convert electrical signals into light.
Market Size & Forecast
- Global Market Value (2025): USD 5.08 Billion
- Expected Market Value (2033): USD 10.89 Billion
- Forecast CAGR (2026–2033): 10.00%
- Leading Region in 2025: Asia-Pacific
- Fastest Growing Region: North America
What are the Major Takeaways of the Single-Mode Optical Transceiver Market?
- Asia-Pacific dominated the single-mode optical transceiver market with the largest revenue share of 38.10% in 2025, supported by large optical module manufacturing in China, strong telecom network investment, and growing data center capacity.
- North America is expected to be the fastest-growing region at a CAGR of 12.20% from 2026 to 2033, fueled by hyperscale AI data center expansion, large cloud investment, and demand for 800G and 1.6T optics.
- The SFP+ & SFP28 segment led the market with a 31.80% share in 2025, driven by wide installed base, low cost, and extensive use in enterprise, access, and telecom networks.
- QSFP-DD & OSFP are the fastest-growing form factors, projected to register a CAGR of 16.40%, reflecting rising demand for high-density 400G, 800G, and 1.6T links in AI clusters.
- The 25G to 100G segment dominated the data rate category with a 41.50% revenue share in 2025, led by large deployments across data centers, mobile fronthaul, and enterprise networks.
- Data centers & cloud accounted for 46.30% of the market share in 2025, preferred for massive switch port volumes, short and medium reach links, and frequent upgrades.
- The AI & HPC clusters segment is the fastest-growing application, with a CAGR of 19.40%, driven by GPU networking, scale-out fabrics, and record demand for 800G optics.
Report Scope and Single-Mode Optical Transceiver Market Segmentation
|
Attributes |
Single-Mode Optical Transceiver Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, geographically represented company-wise production and capacity, network layouts of distributors and partners, detailed and updated price trend analysis and deficit analysis of supply chain and demand. |
What is the Key Trend in the Single-Mode Optical Transceiver Market?
- Single-mode optical transceivers are increasingly moving up the speed ladder, from 400G to 800G and 1.6T, while adopting silicon photonics, advanced lasers, and co-packaged approaches to cut power and cost per bit.
- For instance, in September 2026, Coherent expanded its pluggable optical line systems portfolio to support high-capacity 800G ZR/ZR+ AI data center links
- Silicon photonics is gaining share, as module makers use photonic integrated circuits to reduce component counts, improve yield, and lower power consumption in high-volume data center transceivers.
- Hyperscalers and module makers are increasingly collaborating early, as buyers compare modules on power per bit, reliability, interoperability, supply security, and ability to scale production for AI deployments.
- For instance, in March 2026, OpenLight announced its first volume-production orders for laser-integrated 800G and 1.6T photonic integrated circuits.
- As AI clusters, 1.6T and 3.2T links, silicon photonics, and co-packaged optics continue to advance, single-mode optical transceivers are expected to expand beyond pluggable modules into integrated, ultra-dense interconnects.
What are the Key Drivers of the Single-Mode Optical Transceiver Market?
- The rapid growth of AI training and inference clusters has significantly increased demand for optical links that move huge volumes of data between servers, switches, and racks at low latency.
- For instance, in March 2026, Marvell expanded its 1.6T optical DSP portfolio to improve performance, power efficiency, and optical link reliability.
- Hyperscalers, telecom carriers, enterprises, and research networks are adopting single-mode transceivers to support higher bandwidth, longer reach, lower power per bit, and more flexible network designs.
- For instance, in August 2026, according to Lumentum’s fiscal 2026 results, the company reported net revenue of USD 3.01 billion and said that as AI compute workloads grow, data center architects are turning to optical links as a primary means of connectivity and the importance of optics in large clusters.
- With hyperscalers committing to multi-year AI infrastructure investment and carriers upgrading fiber networks, single-mode optical transceivers can gain wider qualification, volume orders, and long-term supply agreements.
What Factors are Challenging the Growth of the Single-Mode Optical Transceiver Market?
- Single-mode transceivers face intense price competition and rapid technology change, which compress margins and make older products obsolete quickly, especially for suppliers with limited scale.
- For instance, in March 2026, Taclink launched a 1.6T OSFP DR8 single-mode optical transceiver designed for transmission distances up to 500 meters.
- These pricing dynamics can squeeze margins for smaller suppliers, while heavy capital needs for lasers, photonic chips, and test equipment may limit the ability to invest in new generations.
- Supply constraints for indium phosphide lasers and advanced packaging, trade restrictions on high-speed optics, and strict qualification cycles with hyperscalers further restrict growth, requiring suppliers to invest in capacity, diversified sourcing, and long validation programs that may increase costs.
- The combination of price competition, capital intensity, supply constraints, and trade and qualification risks can constrain growth among smaller suppliers and cost-sensitive buyers.
How is the Single-Mode Optical Transceiver Market Segmented?
The single-mode optical transceiver market is segmented on the basis of form factor, data rate, distance, and application.
- By Form Factor
On the basis of form factor, the single-mode optical transceiver market is segmented into SFF & SFP, SFP+ & SFP28, QSFP+ & QSFP28, and QSFP-DD & OSFP. The SFP+ & SFP28 segment dominated the market with 31.80% share in 2025, supported by its wide installed base, low cost, and extensive use in enterprise, access, and telecom networks. These modules support 10G and 25G links over single-mode fiber. They are compact, hot-pluggable, and compatible with a large range of switches and routers. Established multi-source agreements make them easy to source from many suppliers. Steady upgrades from lower speeds and large replacement demand continue to reinforce the segment’s leadership. Suppliers also offer industrial-temperature and extended-reach versions to serve harsher environments.
The QSFP-DD & OSFP segment is projected to register the fastest growth at a CAGR of 16.40% from 2026 to 2033, driven by rising demand for high-density 400G, 800G, and 1.6T links in AI clusters. These form factors support more lanes per module and higher faceplate density. Switch makers are designing platforms around them for hyperscale networks. Advances in thermal design and power efficiency are improving practicality. Cost, heat, and compatibility remain important considerations. Suppliers are also developing liquid-cooled and low-power variants for dense deployments.
- By Data Rate
On the basis of data rate, the single-mode optical transceiver market is segmented into up to 25G, 25G to 100G, 200G to 400G, and 800G & above. The 25G to 100G segment dominated the market with 41.50% share in 2025, supported by large deployments across data centers, mobile fronthaul, and enterprise networks. These speeds offer a strong balance of cost, power, and bandwidth. Many existing networks still use 100G as a core building block. Mature supply chains keep prices competitive. Continued use in telecom and enterprise upgrades continues to reinforce the segment’s leadership. Producers also offer variants for longer reach and varying temperature ranges to serve many network needs.
The 800G & above segment is projected to register the fastest growth at a CAGR of 18.20% from 2026 to 2033, driven by AI cluster networking, higher switch radix, and rising bandwidth per server. Hyperscalers are moving quickly to 800G, with 1.6T beginning to ship. Silicon photonics and advanced EMLs help control power. Module makers are expanding capacity for these products. Power consumption, yield, and cost remain important considerations. Customers are also pushing suppliers for faster qualification and stable supply of lasers and driver chips.
- By Distance
On the basis of distance, the single-mode optical transceiver market is segmented into up to 2 km, 2 km to 40 km, and above 40 km. The up to 2 km segment dominated the market with 55.30% share in 2025, driven by large volumes of short and medium reach links inside and between data center buildings. Single-mode fiber supports higher speeds and longer lengths than multimode. Campus-scale AI clusters increasingly use single-mode for reach and future-proofing. Standards such as DR and FR optics serve these links. Established deployment practices continue to reinforce this segment's leadership. Growing use of parallel single-mode optics also helps support high speeds over short reaches at low cost.
The 2 km to 40 km segment is projected to register the fastest growth at a CAGR of 10.60% from 2026 to 2033, supported by metro networks, data center interconnect, and 5G transport. Operators upgrade access and aggregation networks with higher-speed optics. Distributed data center campuses need links over several kilometers. Coherent and direct-detect options offer different cost and reach trade-offs. Power, dispersion, and cost remain important design factors. Growth of edge data centers and cloud on-ramps also adds links in the metro range.
- By Application
On the basis of application, the single-mode optical transceiver market is segmented into data centers & cloud, AI & HPC clusters, telecom & 5G, and enterprise & others. The data centers & cloud segment dominated the market with 46.30% share in 2025, supported by massive switch port volumes, short and medium reach links, and frequent upgrades. Cloud providers deploy large numbers of transceivers across leaf, spine, and interconnect layers. Standardized designs and bulk purchasing support steady volumes. Close relationships between module makers and hyperscalers continue to reinforce this segment's leadership. Strong demand for refresh cycles also helps suppliers maintain steady volumes across product generations.
The AI & HPC clusters segment is projected to register the fastest growth at a CAGR of 19.40% from 2026 to 2033, driven by GPU networking, scale-out fabrics, and record demand for 800G optics. Training clusters need very high bandwidth and low latency between accelerators. Operators are adopting optical links over copper as speeds rise. Co-packaged and near-packaged optics are emerging for future systems. Power, reliability, and supply availability remain key considerations. Operators also run large pilot clusters to validate new optics before wider deployment.
Which Region Holds the Largest Share of the Single-Mode Optical Transceiver Market?
- Asia-Pacific dominated the single-mode optical transceiver market with the largest revenue share of 38.10% in 2025, supported by large optical module manufacturing in China, strong telecom network investment, and growing data center capacity.
- The region also benefits from a large concentration of optical component and module manufacturers, strong investment in fiber and 5G networks, and rapid growth of cloud and AI data centers. Increasing domestic demand and export capacity continue to strengthen Asia-Pacific’s position in the global market. Strong government support for semiconductor and telecom industries also supports local capacity growth.
Japan Single-Mode Optical Transceiver Market Insight
The Japan single-mode optical transceiver market is witnessing consistent growth due to strong optical component expertise, advanced telecom networks, and high quality expectations. Domestic suppliers and carriers are increasingly adopting high-speed and coherent modules. Moreover, strong demand for reliability, compact designs, and research into next-generation photonics is further contributing to market growth in Japan. Close cooperation between suppliers and carriers also supports long-term network upgrades.
China Single-Mode Optical Transceiver Market Insight
The China single-mode optical transceiver market is growing rapidly, driven by large domestic module makers, extensive 5G and fiber networks, and strong investment in AI computing. Growing production of 400G and 800G modules is significantly boosting market demand. In addition, vertically integrated suppliers, cost advantages, and strong exports are positioning China as a key growth market across Asia-Pacific. Strong government support for computing and optical industries also helps suppliers scale quickly.
Europe Single-Mode Optical Transceiver Market Insight
The Europe single-mode optical transceiver market is experiencing strong growth, driven by expanding data centers, 5G deployment, cloud computing, and increasing demand for high-speed, long-distance data transmission. Investments in fiber-optic infrastructure and network modernization are accelerating adoption across telecommunications and enterprise applications. Germany, the United Kingdom, and France represent key regional markets. Emerging 400G and 800G technologies, energy-efficient designs, and advanced optical components are creating new opportunities, despite supply-chain constraints and pricing pressures.
U.K. Single-Mode Optical Transceiver Market Insight
The U.K. single-mode optical transceiver market is experiencing steady growth, supported by full-fibre network rollout, growing data center capacity, and strong photonics research. Carriers and cloud operators are increasingly adopting higher-speed optics. Furthermore, active start-ups, university research, and demand for secure networks are supporting wider adoption of single-mode transceivers in the U.K. Strong data center development in the south of England also supports demand for higher-speed optics.
Germany Single-Mode Optical Transceiver Market Insight
The Germany single-mode optical transceiver market is expanding steadily due to the country’s strong industrial base, growing data center investment, and extensive fiber rollout. Carriers, enterprises, and research networks are increasingly utilizing high-speed single-mode optics. Continuous innovation in photonics, strong engineering capability, and Germany’s focus on reliability and energy efficiency are further driving market growth in the country. Strong demand from Frankfurt and other data center hubs also supports transceiver volumes.
Which are the Top Companies in Single-Mode Optical Transceiver Market?
The single-mode optical transceiver industry is primarily led by well-established companies, including:
- Coherent Corp. (U.S.)
- Lumentum Holdings Inc. (U.S.)
- Broadcom Inc. (U.S.)
- Accelink Technologies Co., Ltd. (China)
- Zhongji Innolight Co., Ltd. (China)
- Cisco Systems, Inc. (U.S.)
- Sumitomo Electric Industries, Ltd. (Japan)
- Fujitsu Optical Components Limited (Japan)
- Mitsubishi Electric Corporation (Japan)
- Eoptolink Technology Inc., Ltd. (China)
- Fabrinet (Thailand)
- Marvell Technology, Inc. (U.S.)
- Ciena Corporation (U.S.)
- Nokia Corporation (Finland)
- Huawei Technologies Co., Ltd. (China)
- Source Photonics, Inc. (U.S.)
- Applied Optoelectronics, Inc. (U.S.)
- NEC Corporation (Japan)
- Hisense Broadband Multimedia Technologies Co., Ltd. (China)
- Furukawa Electric Co., Ltd. (Japan)
What are Latest Developments in Single-Mode Optical Transceiver Market?
- In September 2026, Credo introduced 1.6T ZeroFlap optical transceivers featuring silicon photonics and real-time link diagnostics for AI networks.
- In September 2026, Coherent expanded its pluggable optical line systems portfolio to support high-capacity 800G ZR/ZR+ AI data center links.
- In August 2026, Lumentum reported fiscal 2026 net revenue of USD 3.01 billion and said its cloud module business is advancing 1.6T adoption. The company highlighted that AI workloads are pushing data center architects toward optical links as the primary means of connectivity. The company also pointed to strong demand for indium phosphide lasers.
- In March 2026, Marvell expanded its 1.6T optical DSP portfolio to improve performance, power efficiency, and optical link reliability.
- In March 2026, OpenLight announced its first volume-production orders for laser-integrated 800G and 1.6T photonic integrated circuits.
- In March 2026, Taclink launched a 1.6T OSFP DR8 single-mode optical transceiver designed for transmission distances up to 500 meters.
- In September 2026, Semtech introduced FiberEdge transimpedance amplifiers for 1.6T optical interconnects and improved 800G power efficiency.
- In April 2025, Jabil launched 1.6T OSFP transceivers using Intel silicon photonics, supporting parallel single-mode fiber connectivity.
- In March 2025, Broadcom introduced 3nm Sian3 and 5nm Sian2M DSP solutions targeting 800G and 1.6T optical transceivers.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Single Mode Optical Transceiver Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Single Mode Optical Transceiver Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Single Mode Optical Transceiver Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.