B2B Non-Dairy Creamer (NDC) Market Overview
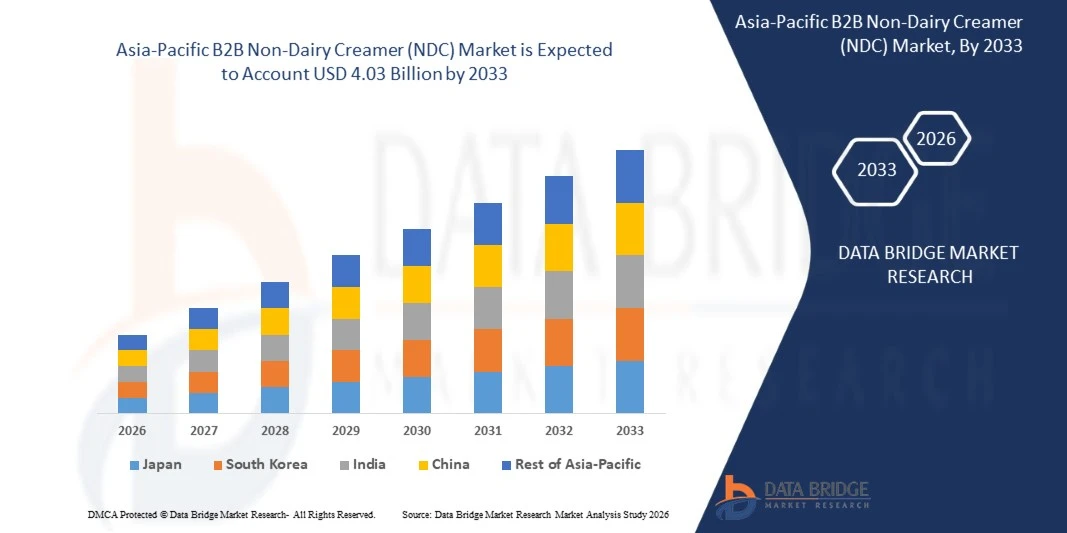
The Asia-Pacific B2B Non-Dairy Creamer (NDC) market was valued at USD 2.31 Billion in 2025 and is projected to reach USD 4.03 Billion by 2033, growing at a CAGR of 11.74% from 2026 to 2033. The increasing demand for convenient beverage solutions, rising consumption of coffee and tea, and expanding use of non-dairy creamers across food and beverage applications are supporting market growth. Food and beverage manufacturers, coffee premix producers, instant beverage companies, and foodservice operators are increasingly adopting non-dairy creamers to improve creaminess, whiteness, texture, flavor, and product stability. Growing demand for instant coffee, ready-to-mix beverages, vending machine products, and convenient beverage preparations is further contributing to market expansion.
Furthermore, the growing demand for products with extended shelf life, cost-effective formulations, and consistent functional performance is encouraging manufacturers to develop innovative non-dairy creamer solutions. Advancements in spray-drying technology, increasing availability of plant-based ingredients, and rising interest in lactose-free alternatives are creating opportunities for product development. The expansion of cafés, hotels, restaurants, and commercial beverage services, coupled with increasing demand for coffee and tea premixes across household and institutional channels, is expected to support the growth of the Asia-Pacific B2B Non-Dairy Creamer (NDC) market during the forecast period.
Market Size & Forecast
- Asia-Pacific Market Value (2025): USD 2.31 Billion
- Expected Market Value (2033): USD 4.03 Billion
- Forecast CAGR (2026–2033): 11.74%
- Leading Region in 2025: China
- Fastest Growing Region: India
Key Market Trends & Insights
- The China state dominated the Asia-Pacific B2B Non-Dairy Creamer (NDC) market with the largest revenue share of 31.00% in 2025, driven by its well-established food and beverage processing industry, strong demand for coffee and tea products, and widespread use of instant beverage formulations. The presence of established food manufacturers, coffee premix producers, and commercial foodservice operators supports demand for non-dairy creamers across industrial applications.
- The spray-dried NDC segment dominated the market with a 74.72% share in 2025, owing to its extended shelf life, convenient handling, cost-effective storage and transportation, and suitability for large-scale food and beverage manufacturing. Its ability to provide consistent solubility, whitening properties, and creamy texture makes it widely suitable for instant coffee, tea premixes, vending beverages, and other powdered beverage formulations.
- India is expected to be the fastest-growing country in the Asia-Pacific B2B Non-Dairy Creamer (NDC) market, registering a CAGR of 10.34% during 2026–2033, driven by increasing demand for convenient beverage solutions, expanding specialty coffee culture, and growing consumption of instant coffee and tea products. The expansion of cafés, restaurants, hotels, and other foodservice establishments is supporting demand for non-dairy creamers that provide consistent creaminess, texture, and product stability.
- The granulated NDC segment is projected to be the fastest-growing segment, registering a CAGR of 13.81% during 2026–2033. Growth is driven by increasing demand for convenient handling, improved product dosing, and easy incorporation into beverage mixes and food formulations. Granulated formats can support efficient blending and processing in suitable applications, making them attractive to manufacturers of instant coffee, tea premixes, vending products, and other powdered beverage solutions.
- The 28–35% fat NDC segment dominated the market with a 61.00% share in 2025, driven by its ability to provide a balanced combination of creaminess, mouthfeel, whitening performance, and formulation versatility. This fat range is suitable for a broad range of commercial beverage applications, including instant coffee, tea premixes, and vending machine beverages.
- The palm oil-based NDC segment dominated the market with a 82.58% share in 2025, supported by the ingredient's established supply chains, formulation versatility, and suitability for large-scale non-dairy creamer production. Palm oil-based formulations can contribute to the desired creamy mouthfeel, texture, and stability required in instant beverages and powdered food products.
- The standard NDC segment dominated the market with a 78.93% share in 2025, owing to its broad commercial applicability, cost-effectiveness, and established use across conventional beverage formulations. Standard non-dairy creamers provide the whitening, creaminess, and texture required for everyday coffee and tea products, instant beverage mixes, and foodservice applications.
Report Scope and B2B Non-Dairy Creamer (NDC) Market Segmentation
|
Attributes |
B2B Non-Dairy Creamer (NDC) Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
Asia-Pacific
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
B2B Non-Dairy Creamer (NDC) Market Trends
Trend: Expansion of Plant-Based Formulations, Clean-Label Ingredients, and Functional Creamer Innovation
The Asia-Pacific Non-Dairy Creamer (NDC) market is increasingly shifting beyond conventional creamer formulations toward plant-based ingredients, simplified ingredient lists, innovative flavors, and improved functional performance. Manufacturers are expanding their product portfolios to address changing dietary preferences, rising demand for dairy-free alternatives, and the requirements of commercial beverage applications. Improvements in formulation and processing technologies are also supporting the development of non-dairy creamers with enhanced taste, texture, solubility, and stability for coffee, tea, instant beverage mixes, and foodservice applications.
For instance,
- In June 2024, Elmhurst 1925 launched a range of dairy-free cashew creamers in flavors including Sweet Cream, Cinnamon Churro, Caramel Brûlée, and Unsweetened. The products were formulated without oils, gums, or added fibers, reflecting growing interest in plant-based creamers with simplified ingredient compositions.
- In March 2024, Califia Farms introduced Organic Almond Creamers, expanding its portfolio of plant-based beverage products. The launch highlighted growing demand for organic creamer alternatives and formulations designed to meet consumer preferences for recognizable ingredients.
- In January 2024, MPearlRock completed its acquisition of Nutpods, a brand specializing in dairy-free coffee creamers and related plant-based products. The acquisition reflected continued investment in the non-dairy creamer category and opportunities to expand product distribution and strengthen market presence.
Overall, these developments indicate that product innovation is becoming increasingly important in the Asia-Pacific Non-Dairy Creamer (NDC) market. The growing focus on plant-based ingredients, clean-label formulations, flavor diversification, and functional performance is expected to encourage manufacturers to develop differentiated products for commercial beverage producers, foodservice operators, and other B2B customers. Continued investment in formulation technologies and expanding applications across coffee, tea, and instant beverage products are expected to support market development during the forecast period.
Asia-Pacific B2B Non-Dairy Creamer (NDC) Market Dynamics
Key Market Driver: Rising Demand for Convenient Beverages, Functional Ingredients, and Cost-Effective Formulations
The Asia-Pacific B2B Non-Dairy Creamer (NDC) market is witnessing increasing demand as food and beverage manufacturers focus on developing convenient, shelf-stable, and cost-effective beverage products. Non-dairy creamers are widely used in instant coffee, tea premixes, vending beverages, ready-to-mix drinks, and various food applications because they provide creaminess, whitening properties, texture, and consistent product performance. The expansion of commercial beverage production, growing consumption of instant drinks, and increasing demand for ingredients that simplify large-scale manufacturing are encouraging food processors and beverage companies to incorporate non-dairy creamers into their formulations.
For instance,
- In August 2024, Nestlé continued to expand its coffee portfolio through established brands such as NESCAFÉ and Nescafé Dolce Gusto, reflecting the continuing importance of convenient coffee formats in the Asia-Pacific beverage industry. The development of instant and portion-based coffee products supports demand for functional ingredients that deliver consistent taste, texture, and preparation convenience.
- In June 2025, FrieslandCampina Ingredients offers specialty ingredients for food and beverage manufacturers, including solutions designed to support product functionality and formulation performance. The broader development of application-specific ingredients highlights the importance of ingredient innovation in meeting manufacturers' requirements for consistent quality, processing efficiency, and end-product performance.
- In May 2026, Kerry Group develops taste and nutrition solutions for food and beverage applications, supporting manufacturers in responding to evolving consumer preferences and product formulation requirements. Such ingredient innovation reflects the broader industry focus on improving sensory characteristics, product consistency, and convenience across commercial beverage applications.
Overall, the growing demand for convenient beverage products, consistent formulation performance, and cost-efficient ingredient solutions is expected to support the expansion of the Asia-Pacific B2B Non-Dairy Creamer (NDC) market. Increasing consumption of instant coffee and tea, expansion of cafés and foodservice establishments, and rising demand for powdered beverage premixes are creating opportunities for non-dairy creamer suppliers. Continued improvements in spray-drying technology, formulation versatility, and ingredient functionality are also expected to strengthen the role of non-dairy creamers across industrial food and beverage applications.
Key Restraint/Challenge: Raw Material Price Volatility, Clean-Label Expectations, and Sustainable Ingredient Sourcing
The Asia-Pacific B2B Non-Dairy Creamer (NDC) market faces increasing challenges in balancing cost competitiveness, functional performance, and evolving sustainability requirements. Manufacturers rely on ingredients such as vegetable oils, glucose syrups, maltodextrin, emulsifiers, stabilizers, and other functional additives to achieve the desired creaminess, whiteness, solubility, and shelf stability. Fluctuations in the prices and availability of these raw materials can increase production costs and create uncertainty for bulk purchasers, including coffee premix manufacturers, beverage producers, and foodservice suppliers. At the same time, growing interest in clean-label formulations, plant-based ingredients, and transparent sourcing is encouraging manufacturers to reconsider ingredient selection and processing methods.
For instance,
- In January 2025, Organic Valley launched its first organic oat-based creamer range in four flavors, including vanilla, caramel, oatmeal cookie, and cinnamon spice. The launch highlighted growing interest in plant-based creamer alternatives and sourcing ingredients through established organic farming networks. For B2B manufacturers, meeting similar expectations can require stronger supplier traceability, reliable raw material availability, and careful control of formulation costs.
- In March 2025, Violife introduced Supreme Coffee Creamers in three flavors, using a lentil-based formulation designed to maintain a smooth texture and reduce separation and curdling in coffee. This development highlights the technical challenge of reproducing the blending performance and sensory qualities of conventional creamers with alternative ingredients. Similar functional requirements are important for ingredient suppliers serving commercial beverage manufacturers.
- In January 2026, MALK launched a coconut-based creamer range in unsweetened, vanilla, and sweet cream varieties. The products were positioned around simplified formulations without oils, gums, natural flavors, or fillers. This launch illustrates the growing emphasis on clean-label product development, which can create additional formulation challenges for manufacturers seeking to maintain creaminess, consistency, and stability while limiting the use of conventional functional ingredients.
- In January 2026, Califia Farms expanded its Simple & Organic portfolio with two new creamer flavors, Sweet Crème and Salted Caramel, alongside updated core creamer recipes. The development reflects continued product innovation in the plant-based creamer category and highlights the need for manufacturers to adapt formulations to changing taste preferences while maintaining product consistency.
- In May 2026, Ingredion announced a strategic partnership and joint venture with Sanstar Limited to expand access to specialty food and pharmaceutical ingredient markets in India. Although the announcement was not specific to non-dairy creamers, it demonstrates how ingredient suppliers are strengthening sourcing, manufacturing, and formulation capabilities to serve evolving food industry requirements. Such developments highlight the importance of reliable ingredient supply and scalable production capabilities for manufacturers operating in the broader NDC value chain.
Overall, these challenges highlight the need for improved raw material sourcing strategies, efficient production processes, formulation innovation, and stronger supply chain management in the Asia-Pacific B2B Non-Dairy Creamer (NDC) market. Manufacturers that can maintain cost efficiency while delivering consistent functional performance and meeting evolving clean-label and sustainability requirements will be better positioned to address changing buyer expectations and strengthen their competitiveness during the forecast period.
Key Market Opportunity: Expansion of Functional Creamer Formulations, Plant-Based Ingredients, and Customized Beverage Solutions
The Asia-Pacific B2B Non-Dairy Creamer (NDC) market is increasingly moving beyond conventional powdered creamers toward specialized formulations that offer improved solubility, creamy texture, formulation flexibility, and suitability for evolving beverage applications. Food and beverage manufacturers are focusing on product innovation to meet the growing demand for specialty coffee, bubble tea, cold beverages, instant premixes, and plant-based alternatives. Opportunities are emerging for non-dairy creamer suppliers to develop customized ingredient solutions with different fat contents, flavor profiles, and functional properties for industrial beverage producers and foodservice operators.
For instance,
- In June 2025, Rich Products introduced its All-In-One Creamer, a multifunctional creamer developed primarily with non-dairy ingredients and a milk derivative. The product was designed for specialty beverages, including dirty sodas, bubble tea, specialty coffees, and smoothies. Its versatility as a beverage base, foam, and whipped topping highlights opportunities for creamer suppliers to serve expanding specialty beverage categories and provide convenient solutions to foodservice operators.
- In September 2025, Santos Premium Krimer participated in Food Ingredients Asia Thailand 2025, highlighting its efforts to strengthen international market presence and connect with potential business customers across the ASEAN region. The company emphasized opportunities to engage with ingredient buyers and develop potential commercial relationships, demonstrating how industry exhibitions can support market expansion, customer acquisition, and business development for non-dairy creamer manufacturers.
- In May 2026, Ingredion announced a strategic partnership and joint venture with Sanstar Limited, alongside an equity stake, to expand access to food and pharmaceutical ingredient markets in India. Although the announcement was not specific to non-dairy creamers, the partnership combines local manufacturing capabilities with Asia-Pacific ingredient formulation and commercialization expertise. This development illustrates a broader opportunity for ingredient companies to strengthen regional supply chains, expand customer access, and develop differentiated food and beverage formulations.
Overall, these developments highlight opportunities for the Asia-Pacific B2B Non-Dairy Creamer (NDC) market through functional product innovation, customized formulations, and stronger commercial partnerships. Growing demand for specialty beverages, convenient premixes, and ingredients that deliver consistent texture and solubility is expected to encourage manufacturers to diversify their product portfolios. Investments in formulation capabilities, regional distribution networks, and customer-specific solutions are likely to create additional growth opportunities across foodservice, beverage manufacturing, and industrial food processing applications.
Asia-Pacific B2B Non-Dairy Creamer (NDC) Market Scope
The Asia-Pacific non-dairy creamer market is segmented into seven notable segments based on the vehicle type, power output, number of passengers, transmission type, propulsion type, battery type, and application.
- By Form
On the basis of form, the Asia-Pacific non-dairy creamer market is segmented into powdered NDC, liquid NDC, granulated NDC, spray-dried NDC, and other forms. In 2025, the spray-dried NDC segment is expected to dominate the Asia-Pacific B2B Non-Dairy Creamer (NDC) market with a market share of 74.72% due to its extended shelf life, cost-effective storage and transportation, and suitability for large-scale commercial production.
The Granulated NDC segment is projected to register the fastest CAGR of 11.43% from 2026 to 2033, owing to increasing demand for convenient, easy-to-handle creamer formats and their suitability for instant beverage and powdered food applications. Granulated non-dairy creamers offer advantages in handling, dosing, blending, and processing, making them suitable for manufacturers of coffee and tea premixes, vending beverages, and other instant drink formulations.
- By Fat Content
On the basis of fat content, the Asia-Pacific non-dairy creamer market is segmented into below 20% fat, 20–27% fat, 28–35% fat, 36–50% fat, and above 50% fat. In 2025, the 28–35% fat segment is expected to dominate the market with a share of 61.00% due to its balanced combination of creaminess, mouthfeel, whitening performance, and formulation versatility. Non-dairy creamers within this fat range are widely suitable for coffee and tea premixes, instant beverages, vending machine products, and other commercial food and beverage applications.
The 36–50% Fat segment is projected to register the fastest CAGR of 10.60% from 2026 to 2033, owing to increasing demand for non-dairy creamers that deliver richer creaminess, enhanced mouthfeel, and improved texture in specialty beverage and food applications. Higher-fat formulations are suitable for premium coffee and tea premixes, vending beverages, and other commercial beverage preparations where a fuller body and creamy sensory profile are preferred.
- By Fat / Oil Source
On the basis of fat/oil source, the Asia-Pacific non-dairy creamer market is segmented into palm oil-based, coconut oil-based, soy oil-based, canola/rapeseed oil-based, corn oil-based, blended vegetable oil-based, and other oil sources. In 2025, the palm oil-based segment is expected to dominate the market with a share of 82.58% due to its wide availability, cost competitiveness, and suitability for large-scale non-dairy creamer manufacturing. Palm oil provides functional properties that contribute to the desired creamy texture, mouthfeel, and stability of creamer formulations used in coffee and tea premixes, instant beverages, and other food applications.
The Blended Vegetable Oil-Based segment is expected to experience the fastest CAGR of 13.54% from 2026 to 2033, owing to increasing demand for customized oil blends that deliver a balanced combination of functionality, cost efficiency, texture, and stability in non-dairy creamer formulations. Blending different vegetable oils enables manufacturers to adjust the fat composition and functional properties of creamers according to the requirements of coffee and tea premixes, instant beverages, and other food applications.
- By Product Positioning
On the basis of product positioning, the Asia-Pacific non-dairy creamer market is segmented into standard NDC, premium NDC, and functional/specialty NDC. In 2025, the standard NDC segment is expected to dominate the market with a share of 78.93% due to its cost-effectiveness, wide availability, and established use across conventional coffee, tea, and instant beverage applications. Standard non-dairy creamers provide consistent whitening, creaminess, texture, and taste, making them suitable for large-scale beverage manufacturing and foodservice operations.
The Functional/Specialty NDC segment is expected to experience the fastest CAGR of 15.01% from 2026 to 2033, owing to increasing demand for customized creamer formulations with enhanced functional properties and application-specific performance. Food and beverage manufacturers are increasingly seeking specialty non-dairy creamers that offer improved solubility, heat stability, foaming capabilities, and texture for applications such as specialty coffee, tea premixes, ready-to-mix beverages, and vending products.
- By Formulation / Certification
On the basis of formulation/certification, the Asia-Pacific non-dairy creamer market is segmented into conventional, clean-label, organic, vegan/plant-based, palm-free, non-GMO, and other specialty formulations. In 2025, the conventional segment is expected to dominate the market with a share of 89.15% due to its cost-effectiveness, widespread availability, and established adoption across commercial food and beverage applications. Conventional non-dairy creamers offer consistent whitening, creaminess, texture, and performance, making them suitable for instant coffee, tea premixes, vending beverages, and large-scale food processing.
The Vegan / Plant-Based segment is expected to experience the fastest CAGR of 18.04% from 2026 to 2033, owing to increasing interest in alternative fat sources and growing demand for non-dairy creamer formulations that reduce dependence on palm oil. Food and beverage manufacturers are exploring palm-free alternatives to diversify ingredient sourcing and address customer preferences related to sustainability and responsible sourcing.
- By Application
On the basis of application, the Asia-Pacific non-dairy creamer market is segmented into 3-in-1 coffee, instant coffee, tea premixes, milk tea, bubble tea, instant beverage mixes, vending beverages, hot chocolate/cocoa mixes, bakery, confectionery, soups, sauces and gravies, desserts, and other applications. In 2025, the 3-in-1 Coffee segment is expected to dominate the market with a share of 32.97% due to the growing demand for convenient, ready-to-prepare beverage products that combine coffee, creamer, and sweetener in a single formulation. Non-dairy creamers provide the desired whiteness, creamy texture, and smooth mouthfeel, enhancing the sensory quality of instant coffee products.
The Bubble Tea segment is expected to experience the fastest CAGR of 14.89% from 2026 to 2033, owing to the growing popularity of specialty tea beverages, increasing expansion of bubble tea outlets, and rising demand for customized beverage experiences. Non-dairy creamers are increasingly used in milk tea and bubble tea formulations to provide a creamy texture, smooth mouthfeel, and consistent flavor profile.
- By Customer Type
On the basis of customer type, the Asia-Pacific non-dairy creamer market is segmented into food and beverage manufacturers, coffee and tea premix manufacturers, bakery and confectionery manufacturers, beverage manufacturers, foodservice and HoReCa, vending and automated beverage operators, bubble tea and specialty beverage chains, private-label and contract manufacturers, distributors and ingredient wholesalers, and other B2B customers. In 2025, the Bakery segment is expected to dominate the Asia-Pacific B2B Non-Dairy Creamer (NDC) market with a market share of 28.58% due to the extensive use of non-dairy creamers in instant coffee, tea premixes, and ready-to-prepare beverage formulations. These manufacturers rely on non-dairy creamers to deliver consistent whiteness, creaminess, smooth texture, and product stability across high-volume production.
The Bubble Tea & Specialty Beverage Chains segment is expected to experience the fastest CAGR of 12.86% from 2026 to 2033, owing to the growing popularity of customized specialty beverages, increasing expansion of bubble tea outlets, and rising consumer demand for innovative drink options. Non-dairy creamers are used in milk tea, bubble tea, specialty coffee, and other blended beverages to provide creamy texture, smooth mouthfeel, and consistent product quality.
Asia-Pacific B2B Non-Dairy Creamer (NDC) Market Regional Analysis
China dominated the Asia-Pacific B2B Non-Dairy Creamer (NDC) market and accounted for the largest revenue share of 31.00% in 2025. The region's established food and beverage processing industry, consistent demand for coffee and tea products, and widespread use of non-dairy creamers in instant beverage formulations supported its market leadership. The presence of coffee premix manufacturers, commercial beverage producers, and foodservice operators further strengthened regional demand. In addition, the growing consumption of convenient beverage products and the need for ingredients that provide consistent creaminess, texture, and shelf stability contributed to market development across Asia-Pacific.
Moreover, the India state is projected to register the highest CAGR of 10.34% during 2026–2033, driven by increasing consumption of coffee and tea, expanding café and hospitality industries, and rising demand for instant beverage mixes. Growing urbanization, changing consumption patterns, and the expansion of hotels, restaurants, and quick-service outlets are creating opportunities for non-dairy creamer suppliers. Furthermore, increasing demand for convenient, shelf-stable, and cost-effective beverage ingredients is encouraging food and beverage manufacturers to expand their product offerings. The growing availability of packaged beverages and the development of commercial foodservice channels are expected to further support regional market growth during the forecast period.
China B2B Non-Dairy Creamer (NDC) Market Insight
The China B2B Non-Dairy Creamer (NDC) market is experiencing growth driven by increasing demand for instant coffee, tea premixes, and convenient ready-to-prepare beverages. The expanding café culture, rising popularity of specialty drinks, and growth of foodservice establishments are supporting the adoption of non-dairy creamers across commercial applications. Food and beverage manufacturers are increasingly using these ingredients to improve creaminess, texture, whiteness, and product consistency. Furthermore, the expansion of bubble tea outlets, vending services, and packaged beverage production is creating opportunities for NDC suppliers across China.
India B2B Non-Dairy Creamer (NDC) Market Insight
The India B2B Non-Dairy Creamer (NDC) market is witnessing growth driven by increasing demand for instant coffee, tea premixes, and convenient ready-to-prepare beverages. Non-dairy creamers are increasingly used by food and beverage manufacturers to improve creaminess, texture, whiteness, and product consistency across commercial applications. The expansion of cafés, quick-service restaurants, vending services, and packaged beverage products is further supporting market demand. In addition, rising urbanization, changing consumption patterns, and the growing popularity of specialty beverages are creating opportunities for NDC suppliers across India.
Japan B2B Non-Dairy Creamer (NDC) Market Insight
The Japan B2B Non-Dairy Creamer (NDC) market is supported by growing demand for convenient beverage solutions, established coffee and tea consumption, and the expansion of cafés, foodservice outlets, and ready-to-drink beverage manufacturers. Non-dairy creamers are increasingly used in instant coffee, tea premixes, vending beverages, and commercial food applications to provide consistent creaminess, texture, and product stability. The growing popularity of specialty coffee, convenience-oriented products, and customized beverage formulations is further creating opportunities for NDC suppliers. In addition, demand for shelf-stable ingredients is supporting adoption among food and beverage manufacturers across Japan.
Asia-Pacific B2B Non-Dairy Creamer (NDC) Market Share
The Asia-Pacific B2B Non-Dairy Creamer (NDC) industry is primarily led by well-established companies, including:
- Krüger Group (Germany)
- Kerry Group plc (Ireland)
- Royal FrieslandCampina N.V. (Kievit) (Netherlands)
- Santho Holland Food (Netherlands)
- JDE Peet's (Super) (Netherlands)
- DEK (Grandos) (Germany)
- DMK Group (Turm / DP Supply) (Germany)
- Mokate Ingredients (Poland)
- Meggle Group GmbH (Germany)
- Suzhou Jiahe Foods Industry Co., Ltd. (Cograin) (China)
- Wenhui Food (China)
- Bigtree Group (China)
- Zhucheng Dongxiao Biotechnology Co., Ltd. (China)
- PT Lautan Natural Krimerindo (Indonesia)
- Yearrakarn Co., Ltd. (Thailand)
- Universal Robina Corporation (Philippines)
- Asia Saigon Food Ingredients (Vietnam)
- Dong Suh Companies (Frima) (South Korea)
- Custom Food Group (Thailand)
Latest Developments in Asia-Pacific B2B Non-Dairy Creamer (NDC) Market
- In February 2023, Adient's Korea R&D Center received the Best Collaboration Award from In February 2026, Expansion of instant cappuccino and 3-in-1 beverage offerings. KRÜGER introduced caramelised pistachio cappuccino in a 500 g pack and 3-in-1 pistachio coffee sticks, expanding its flavoured instant beverage portfolio. This is relevant to the non-dairy creamer market through demand for creamy instant coffee mixes, although the announcement does not confirm a new B2B creamer ingredient launch.
- In May 2026, Kerry's published oat-creamer case study describes the development of a vegan, gluten-free, nut-allergen-free oat creamer with no added sugar and frothing capability. The case study supports the market trend toward plant-based creamers with improved functionality; however, its publication date could not be confirmed as 2025 or 2026, so it should be treated as supporting product evidence rather than a dated news announcement.
- In February 2026, JDE Peet's reported FY2025 results and strategic progress. The company reported organic sales growth of 15.3% for 2025, driven by pricing growth despite a decline in volume and mix. The announcement also covered its brand-led strategy and the proposed Keurig Dr Pepper transaction. This is relevant to the broader coffee market and demand for coffee accompaniments, but it does not confirm a new Super-branded non-dairy creamer product.
- In August 2026, Keurig Dr Pepper announced an agreement to acquire JDE Peet's. The proposed transaction was intended to create a Asia-Pacific coffee business with a broader portfolio and expanded scale. It is relevant to the wider coffee supply chain, although the announcement did not identify a specific non-dairy creamer launch.
- In August 2026, JDE Peet's launched its “Grounded in Nature” Nature Transition Plan. The plan outlines actions to protect ecosystems, strengthen farmer resilience, and support deforestation-conscious coffee supply chains. This is relevant to sustainability and sourcing trends in coffee-related products, but it is not a direct non-dairy creamer development.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Table of Content
1 INTRODUCTION
1.1 OBJECTIVES OF THE STUDY
1.2 MARKET DEFINITION
1.3 OVERVIEW OF ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET
1.4 CURRENCY AND PRICING
1.5 LIMITATION
1.6 MARKETS COVERED
2 MARKET SEGMENTATION
2.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: SEGMENTATION
2.2 KEY TAKEAWAYS
2.3 ARRIVING AT THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET SIZE
2.4 MARKETS COVERED
2.5 GEOGRAPHIC SCOPE
2.5.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: GEOGRAPHIC SCOPE
2.6 YEARS CONSIDERED FOR THE STUDY
2.7 RESEARCH METHODOLOGY
2.7.1 RESEARCH APPROACH: PRIMARY AND SECONDARY RESOURCES
2.7.2 HISTORICAL DATA BUILD-UP
2.7.3 DROC ANALYSIS
2.7.4 PARENT MARKET AND TARGET MARKET
2.7.5 ARRIVING AT THE MARKET SIZE
2.8 TECHNOLOGY LIFE LINE CURVE
2.9 MULTIVARIATE MODELLING
2.1 PRIMARY INTERVIEWS WITH KEY OPINION LEADERS
2.11 DBMR MARKET POSITION GRID
2.12 MARKET APPLICATION COVERAGE GRID
2.12.1 MARKET COVERAGE GRID: ROUTES TO MARKET EVIDENCED IN PUBLISHED SOURCES
2.13 DBMR MARKET CHALLENGE MATRIX
2.14 SECONDARY SOURCES
2.15 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: RESEARCH SNAPSHOT
2.15.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: RESEARCH SNAPSHOT
2.16 ASSUMPTIONS
3 MARKET OVERVIEW
3.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC): KEY FINDINGS
3.2 DRIVERS
3.2.1 PRODUCT POSITIONING: STANDARD NDC -> FUNCTIONAL / SPECIALTY NDC: DRIVER IMPACT ANALYSIS
3.2.2 FRANCHISED MILK TEA, BUBBLE TEA AND VALUE COFFEE CHAINS SCALING ACROSS ASIA PACIFIC
3.2.3 CENTRALISED TENDERING AND THE SHIFT OF CREAMER VOLUME INTO PRIVATE-LABEL AND CONTRACT MANUFACTURE
3.2.4 POLICY-DRIVEN VEGETABLE OIL VOLATILITY FORCING MULTI-OIL BASES AND FAT-BAND REDESIGN
3.2.5 TRANS FAT ELIMINATION FOLLOWED BY SATURATED FAT AND SUGAR LABELLING REFORM
3.2.6 DEFORESTATION DUE DILIGENCE AND CASEINATE-FREE CHEMISTRY REWRITING THE CERTIFICATION STACK
3.2.6.1 PRODUCT POSITIONING: STANDARD NDC -> FUNCTIONAL / SPECIALTY NDC: IMPACT ANALYSIS
3.3 RESTRAINTS
3.3.1 PALM OIL FEEDSTOCK VOLATILITY AND INDONESIAN EXPORT POLICY SET THE CREAMER COST FLOOR
3.3.2 TRANS-FAT AND SATURATED-FAT LIMITS HAVE TAKEN THE CHEAPEST HARDSTOCK OFF THE TABLE
3.3.3 SODIUM CASEINATE KEEPS NON-DAIRY CREAMER INSIDE THE MILK ALLERGEN DECLARATION
3.3.4 PREMIX BUYER CONCENTRATION AND BACKWARD INTEGRATION CAP MERCHANT CREAMER DEMAND
3.4 OPPORTUNITIES
3.4.1 BUBBLE TEA AND MILK TEA CHAINS ARE CENTRALISING CREAMER PROCUREMENT
3.4.2 DEFORESTATION-FREE AND PALM-FREE RULES ARE RESETTING THE EUROPEAN FAT PHASE
3.4.3 CASEINATE-FREE VEGAN CREAMER IS OPENING THE FUNCTIONAL AND SPECIALTY TIER
3.4.4 SACHET COFFEE ACROSS AFRICA, THE GULF AND SOUTH ASIA REWARDS A LOW-FAT GRANULATED CREAMER
3.4.4.1 APPLICATION: INSTANT COFFEE -> 3-IN-1 COFFEE AND TEA PREMIXES: IMPACT ANALYSIS
3.5 CHALLENGES
3.5.1 PRICE-LED COMPETITION FROM INTEGRATED REFINERS AND SELF-SUPPLYING BEVERAGE CHAINS
3.5.2 REGULATORY AND APPLICATION FRAGMENTATION THAT STOPS ONE FORMULA FROM TRAVELLING
3.5.3 A THIN BENCH OF SPRAY-DRYING, EMULSIFICATION AND CERTIFICATION SKILLS
3.5.4 WORKING CAPITAL TIED UP IN OIL VOLATILITY AND LONG QUALIFICATION CYCLES
3.5.4.1 IMPACT TABLE: IMPACT ANALYSIS
4 EMERGING TRENDS IN THE INDUSTRY
4.1 PALM TRACEABILITY MOVES FROM A SUSTAINABILITY CLAIM INTO THE CREAMER SPECIFICATION
4.2 BIOFUEL MANDATES SET THE PRICE OF CREAMER FAT, AND BUYERS REBUILD THE FAT LADDER
4.3 MILK TEA AND BUBBLE TEA CHAINS INDUSTRIALISE CREAMER PROCUREMENT
4.4 LABEL RULES ARE REWRITING WHAT A NON-DAIRY CREAMER CONTAINS
4.5 DRYING CAPACITY CONSOLIDATES AND BRAND OWNERS MOVE TO CONTRACT MANUFACTURE
5 EXECUTIVE SUMMARY
5.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2018-2033 (USD MILLION)
5.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: SEGMENTATION AT A GLANCE, 2025
6 PREMIUM INSIGHTS
6.1 PORTER'S FIVE FORCES ANALYSIS
6.1.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PORTER'S FIVE FORCES
6.2 PESTLE ANALYSIS
6.2.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PESTLE ANALYSIS
7 INNOVATION TRACKER AND STRATEGIC ANALYSIS
7.1 MAJOR DEALS AND STRATEGIC ALLIANCES ANALYSIS
7.1.1 MERGERS AND ACQUISITIONS
7.1.2 LICENSING AND PARTNERSHIP
7.1.3 TECHNOLOGY COLLABORATIONS
7.1.4 STRATEGIC DIVESTMENTS
7.2 NUMBER OF PRODUCTS IN DEVELOPMENT
7.2.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: DISCLOSED DEVELOPMENT AND LAUNCH ACTIVITY
7.3 STAGE OF DEVELOPMENT
7.4 TIMELINES AND MILESTONES
7.5 INNOVATION STRATEGIES AND METHODOLOGIES
7.6 RISK ASSESSMENT AND MITIGATION
7.7 R&D PIPELINE
7.8 FUTURE OUTLOOK
8 PRICING ANALYSIS
9 INDUSTRY ECOSYSTEM ANALYSIS
9.1 PROMINENT COMPANIES
9.1.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PROMINENT COMPANIES
9.2 SMALL & MEDIUM SIZE COMPANIES
9.2.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: SMALL AND MEDIUM SIZE COMPANIES
9.3 END USERS
9.3.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: END USERS AND THEIR PURCHASE DRIVERS
10 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2018–2033 (USD MILLION)
10.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM: KEY FINDINGS
10.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2025
10.3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2018-2025 (USD MILLION)
10.4 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2026-2033 (USD MILLION)
10.5 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2018-2025 (METRIC TONS (MT))
10.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2026-2033 (METRIC TONS (MT))
10.7 OVERVIEW
10.8 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2033 (USD MILLION)
10.9 POWDERED NDC
10.1 LIQUID NDC
10.11 GRANULATED NDC
10.12 SPRAY-DRIED NDC
10.13 OTHER FORMS
11 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2018–2033 (USD MILLION)
11.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT: KEY FINDINGS
11.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2025
11.3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2018-2025 (USD MILLION)
11.4 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2026-2033 (USD MILLION)
11.5 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
11.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
11.7 OVERVIEW
11.7.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2033 (USD MILLION)
11.8 BELOW 20% FAT
11.9 20-27% FAT
11.1 28-35% FAT
11.11 36-50% FAT
11.12 ABOVE 50% FAT
12 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2018–2033 (USD MILLION)
12.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE: KEY FINDINGS
12.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2025
12.3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
12.4 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
12.5 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
12.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
12.7 OVERVIEW
12.7.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2033 (USD MILLION)
12.8 PALM OIL-BASED
12.9 COCONUT OIL-BASED
12.1 SOY OIL-BASED
12.11 CANOLA/RAPESEED OIL-BASED
12.12 CORN OIL-BASED
12.13 BLENDED VEGETABLE OIL-BASED
12.14 OTHER OIL SOURCES
13 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2018–2033 (USD MILLION)
13.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING: KEY FINDINGS
13.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2025
13.3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
13.4 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
13.5 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
13.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
13.7 OVERVIEW
13.7.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2033 (USD MILLION)
13.8 STANDARD NDC
13.9 PREMIUM NDC
13.1 FUNCTIONAL / SPECIALTY NDC
14 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2018–2033 (USD MILLION)
14.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION: KEY FINDINGS
14.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2025
14.3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
14.4 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
14.5 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
14.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
14.7 OVERVIEW
14.7.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2033 (USD MILLION)
14.8 CONVENTIONAL
14.9 CLEAN-LABEL
14.1 ORGANIC
14.11 VEGAN / PLANT-BASED
14.12 PALM-FREE
14.13 NON-GMO
14.14 OTHER SPECIALTY FORMULATIONS
15 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2018–2033 (USD MILLION)
15.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION: KEY FINDINGS
15.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2025
15.3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2018-2025 (USD MILLION)
15.4 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2026-2033 (USD MILLION)
15.5 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
15.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
15.7 OVERVIEW
15.7.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2033 (USD MILLION)
15.8 3-IN-1 COFFEE
15.9 INSTANT COFFEE
15.1 TEA PREMIXES
15.11 MILK TEA
15.12 BUBBLE TEA
15.13 INSTANT BEVERAGE MIXES
15.14 VENDING BEVERAGES
15.15 HOT CHOCOLATE / COCOA MIXES
15.16 BAKERY
15.17 CONFECTIONERY
15.18 SOUPS
15.19 SAUCES & GRAVIES
15.2 DESSERTS
15.21 OTHER APPLICATIONS
16 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2018–2033 (USD MILLION)
16.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE: KEY FINDINGS
16.2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2025
16.3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
16.4 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
16.5 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
16.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
16.7 OVERVIEW
16.7.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2033 (USD MILLION)
16.8 FOOD & BEVERAGE MANUFACTURERS
16.9 COFFEE & TEA PREMIX MANUFACTURERS
16.1 BAKERY & CONFECTIONERY MANUFACTURERS
16.11 BEVERAGE MANUFACTURERS
16.12 FOODSERVICE & HORECA
16.13 VENDING & AUTOMATED BEVERAGE OPERATORS
16.14 BUBBLE TEA & SPECIALTY BEVERAGE CHAINS
16.15 PRIVATE-LABEL / CONTRACT MANUFACTURERS
16.16 DISTRIBUTORS & INGREDIENT WHOLESALERS
16.17 OTHER B2B CUSTOMERS
17 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY REGION, 2018–2033 (USD MILLION)
17.1.1 ASIA PACIFIC
17.1.1.1 ASIA PACIFIC, BY COUNTRY, 2025
17.1.1.2 ASIA PACIFIC, BY COUNTRY, 2018-2025 (USD MILLION)
17.1.1.3 ASIA PACIFIC, BY COUNTRY, 2026-2033 (USD MILLION)
17.1.1.4 ASIA PACIFIC, BY COUNTRY, 2018-2025 (METRIC TONS (MT))
17.1.1.5 ASIA PACIFIC, BY COUNTRY, 2026-2033 (METRIC TONS (MT))
17.1.1.6 ASIA PACIFIC, BY FORM, 2018-2025 (USD MILLION)
17.1.1.7 ASIA PACIFIC, BY FORM, 2026-2033 (USD MILLION)
17.1.1.8 ASIA PACIFIC, BY FORM, 2018-2025 (METRIC TONS (MT))
17.1.1.9 ASIA PACIFIC, BY FORM, 2026-2033 (METRIC TONS (MT))
17.1.1.10 ASIA PACIFIC, BY FAT CONTENT, 2018-2025 (USD MILLION)
17.1.1.11 ASIA PACIFIC, BY FAT CONTENT, 2026-2033 (USD MILLION)
17.1.1.12 ASIA PACIFIC, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
17.1.1.13 ASIA PACIFIC, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
17.1.1.14 ASIA PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
17.1.1.15 ASIA PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
17.1.1.16 ASIA PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
17.1.1.17 ASIA PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
17.1.1.18 ASIA PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
17.1.1.19 ASIA PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
17.1.1.20 ASIA PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
17.1.1.21 ASIA PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
17.1.1.22 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
17.1.1.23 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
17.1.1.24 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.25 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.26 ASIA PACIFIC, BY APPLICATION, 2018-2025 (USD MILLION)
17.1.1.27 ASIA PACIFIC, BY APPLICATION, 2026-2033 (USD MILLION)
17.1.1.28 ASIA PACIFIC, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.29 ASIA PACIFIC, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.30 ASIA PACIFIC, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
17.1.1.31 ASIA PACIFIC, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
17.1.1.32 ASIA PACIFIC, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
17.1.1.33 ASIA PACIFIC, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
17.1.1.34 CHINA
17.1.1.34.1 CHINA, BY FORM, 2018-2025 (USD MILLION)
17.1.1.34.2 CHINA, BY FORM, 2026-2033 (USD MILLION)
17.1.1.34.3 CHINA, BY FORM, 2018-2025 (METRIC TONS (MT))
17.1.1.34.4 CHINA, BY FORM, 2026-2033 (METRIC TONS (MT))
17.1.1.34.5 CHINA, BY FAT CONTENT, 2018-2025 (USD MILLION)
17.1.1.34.6 CHINA, BY FAT CONTENT, 2026-2033 (USD MILLION)
17.1.1.34.7 CHINA, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
17.1.1.34.8 CHINA, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
17.1.1.34.9 CHINA, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
17.1.1.34.10 CHINA, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
17.1.1.34.11 CHINA, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
17.1.1.34.12 CHINA, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
17.1.1.34.13 CHINA, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
17.1.1.34.14 CHINA, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
17.1.1.34.15 CHINA, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
17.1.1.34.16 CHINA, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
17.1.1.34.17 CHINA, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
17.1.1.34.18 CHINA, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
17.1.1.34.19 CHINA, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.34.20 CHINA, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.34.21 CHINA, BY APPLICATION, 2018-2025 (USD MILLION)
17.1.1.34.22 CHINA, BY APPLICATION, 2026-2033 (USD MILLION)
17.1.1.34.23 CHINA, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.34.24 CHINA, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.34.25 CHINA, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
17.1.1.34.26 CHINA, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
17.1.1.34.27 CHINA, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
17.1.1.34.28 CHINA, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
17.1.1.35 JAPAN
17.1.1.35.1 JAPAN, BY FORM, 2018-2025 (USD MILLION)
17.1.1.35.2 JAPAN, BY FORM, 2026-2033 (USD MILLION)
17.1.1.35.3 JAPAN, BY FORM, 2018-2025 (METRIC TONS (MT))
17.1.1.35.4 JAPAN, BY FORM, 2026-2033 (METRIC TONS (MT))
17.1.1.35.5 JAPAN, BY FAT CONTENT, 2018-2025 (USD MILLION)
17.1.1.35.6 JAPAN, BY FAT CONTENT, 2026-2033 (USD MILLION)
17.1.1.35.7 JAPAN, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
17.1.1.35.8 JAPAN, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
17.1.1.35.9 JAPAN, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
17.1.1.35.10 JAPAN, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
17.1.1.35.11 JAPAN, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
17.1.1.35.12 JAPAN, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
17.1.1.35.13 JAPAN, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
17.1.1.35.14 JAPAN, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
17.1.1.35.15 JAPAN, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
17.1.1.35.16 JAPAN, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
17.1.1.35.17 JAPAN, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
17.1.1.35.18 JAPAN, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
17.1.1.35.19 JAPAN, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.35.20 JAPAN, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.35.21 JAPAN, BY APPLICATION, 2018-2025 (USD MILLION)
17.1.1.35.22 JAPAN, BY APPLICATION, 2026-2033 (USD MILLION)
17.1.1.35.23 JAPAN, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.35.24 JAPAN, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.35.25 JAPAN, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
17.1.1.35.26 JAPAN, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
17.1.1.35.27 JAPAN, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
17.1.1.35.28 JAPAN, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
17.1.1.36 INDIA
17.1.1.36.1 INDIA, BY FORM, 2018-2025 (USD MILLION)
17.1.1.36.2 INDIA, BY FORM, 2026-2033 (USD MILLION)
17.1.1.36.3 INDIA, BY FORM, 2018-2025 (METRIC TONS (MT))
17.1.1.36.4 INDIA, BY FORM, 2026-2033 (METRIC TONS (MT))
17.1.1.36.5 INDIA, BY FAT CONTENT, 2018-2025 (USD MILLION)
17.1.1.36.6 INDIA, BY FAT CONTENT, 2026-2033 (USD MILLION)
17.1.1.36.7 INDIA, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
17.1.1.36.8 INDIA, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
17.1.1.36.9 INDIA, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
17.1.1.36.10 INDIA, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
17.1.1.36.11 INDIA, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
17.1.1.36.12 INDIA, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
17.1.1.36.13 INDIA, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
17.1.1.36.14 INDIA, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
17.1.1.36.15 INDIA, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
17.1.1.36.16 INDIA, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
17.1.1.36.17 INDIA, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
17.1.1.36.18 INDIA, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
17.1.1.36.19 INDIA, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.36.20 INDIA, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.36.21 INDIA, BY APPLICATION, 2018-2025 (USD MILLION)
17.1.1.36.22 INDIA, BY APPLICATION, 2026-2033 (USD MILLION)
17.1.1.36.23 INDIA, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.36.24 INDIA, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.36.25 INDIA, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
17.1.1.36.26 INDIA, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
17.1.1.36.27 INDIA, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
17.1.1.36.28 INDIA, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
17.1.1.37 SOUTH KOREA
17.1.1.37.1 SOUTH KOREA, BY FORM, 2018-2025 (USD MILLION)
17.1.1.37.2 SOUTH KOREA, BY FORM, 2026-2033 (USD MILLION)
17.1.1.37.3 SOUTH KOREA, BY FORM, 2018-2025 (METRIC TONS (MT))
17.1.1.37.4 SOUTH KOREA, BY FORM, 2026-2033 (METRIC TONS (MT))
17.1.1.37.5 SOUTH KOREA, BY FAT CONTENT, 2018-2025 (USD MILLION)
17.1.1.37.6 SOUTH KOREA, BY FAT CONTENT, 2026-2033 (USD MILLION)
17.1.1.37.7 SOUTH KOREA, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
17.1.1.37.8 SOUTH KOREA, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
17.1.1.37.9 SOUTH KOREA, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
17.1.1.37.10 SOUTH KOREA, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
17.1.1.37.11 SOUTH KOREA, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
17.1.1.37.12 SOUTH KOREA, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
17.1.1.37.13 SOUTH KOREA, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
17.1.1.37.14 SOUTH KOREA, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
17.1.1.37.15 SOUTH KOREA, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
17.1.1.37.16 SOUTH KOREA, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
17.1.1.37.17 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
17.1.1.37.18 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
17.1.1.37.19 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.37.20 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.37.21 SOUTH KOREA, BY APPLICATION, 2018-2025 (USD MILLION)
17.1.1.37.22 SOUTH KOREA, BY APPLICATION, 2026-2033 (USD MILLION)
17.1.1.37.23 SOUTH KOREA, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.37.24 SOUTH KOREA, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.37.25 SOUTH KOREA, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
17.1.1.37.26 SOUTH KOREA, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
17.1.1.37.27 SOUTH KOREA, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
17.1.1.37.28 SOUTH KOREA, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
17.1.1.38 AUSTRALIA & NEW ZEALAND
17.1.1.38.1 AUSTRALIA & NEW ZEALAND, BY FORM, 2018-2025 (USD MILLION)
17.1.1.38.2 AUSTRALIA & NEW ZEALAND, BY FORM, 2026-2033 (USD MILLION)
17.1.1.38.3 AUSTRALIA & NEW ZEALAND, BY FORM, 2018-2025 (METRIC TONS (MT))
17.1.1.38.4 AUSTRALIA & NEW ZEALAND, BY FORM, 2026-2033 (METRIC TONS (MT))
17.1.1.38.5 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2018-2025 (USD MILLION)
17.1.1.38.6 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2026-2033 (USD MILLION)
17.1.1.38.7 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
17.1.1.38.8 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
17.1.1.38.9 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
17.1.1.38.10 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
17.1.1.38.11 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
17.1.1.38.12 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
17.1.1.38.13 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
17.1.1.38.14 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
17.1.1.38.15 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
17.1.1.38.16 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
17.1.1.38.17 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
17.1.1.38.18 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
17.1.1.38.19 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.38.20 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.38.21 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2018-2025 (USD MILLION)
17.1.1.38.22 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2026-2033 (USD MILLION)
17.1.1.38.23 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.38.24 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.38.25 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
17.1.1.38.26 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
17.1.1.38.27 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
17.1.1.38.28 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
17.1.1.39 REST OF ASIA-PACIFIC
17.1.1.39.1 REST OF ASIA-PACIFIC, BY FORM, 2018-2025 (USD MILLION)
17.1.1.39.2 REST OF ASIA-PACIFIC, BY FORM, 2026-2033 (USD MILLION)
17.1.1.39.3 REST OF ASIA-PACIFIC, BY FORM, 2018-2025 (METRIC TONS (MT))
17.1.1.39.4 REST OF ASIA-PACIFIC, BY FORM, 2026-2033 (METRIC TONS (MT))
17.1.1.39.5 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2018-2025 (USD MILLION)
17.1.1.39.6 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2026-2033 (USD MILLION)
17.1.1.39.7 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
17.1.1.39.8 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
17.1.1.39.9 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
17.1.1.39.10 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
17.1.1.39.11 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
17.1.1.39.12 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
17.1.1.39.13 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
17.1.1.39.14 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
17.1.1.39.15 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
17.1.1.39.16 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
17.1.1.39.17 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
17.1.1.39.18 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
17.1.1.39.19 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.39.20 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.39.21 REST OF ASIA-PACIFIC, BY APPLICATION, 2018-2025 (USD MILLION)
17.1.1.39.22 REST OF ASIA-PACIFIC, BY APPLICATION, 2026-2033 (USD MILLION)
17.1.1.39.23 REST OF ASIA-PACIFIC, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
17.1.1.39.24 REST OF ASIA-PACIFIC, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
17.1.1.39.25 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
17.1.1.39.26 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
17.1.1.39.27 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
17.1.1.39.28 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
18 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, COMPANY LANDSCAPE
18.1 COMPANY SHARE ANALYSIS: GLOBAL
18.1.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: ESTIMATED COMPANY SHARE, GLOBAL, 2025
18.2 MERGERS & ACQUISITIONS
18.2.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: MERGERS & ACQUISITIONS
18.3 NEW PRODUCT DEVELOPMENT & APPROVALS
18.3.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: NEW PRODUCT DEVELOPMENT & APPROVALS
18.4 EXPANSIONS
18.4.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: EXPANSIONS
18.5 PARTNERSHIP AND OTHER STRATEGIC DEVELOPMENTS
18.5.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PARTNERSHIP AND OTHER STRATEGIC DEVELOPMENTS
18.6 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, SWOT ANALYSIS
18.6.1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC): SWOT ANALYSIS
19 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, COMPANY PROFILES
19.1 ASIA-PACIFIC COMPANIES
19.1.1 KRÜGER GROUP
19.1.1.1 KRÜGER GROUP, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.1.2 COMPANY OVERVIEW
19.1.1.2.1 KRÜGER GROUP: COMPANY SNAPSHOT
19.1.1.3 REVENUE ANALYSIS
19.1.1.4 GEOGRAPHIC PRESENCE
19.1.1.5 PRODUCT PORTFOLIO
19.1.1.5.1 KRÜGER GROUP: PRODUCT PORTFOLIO
19.1.1.6 RECENT DEVELOPMENTS
19.1.1.6.1 KRÜGER GROUP: RECENT DEVELOPMENTS
19.1.1.6.2 MAJOR DEALS
19.1.1.6.3 M&A
19.1.1.6.4 COLLABORATION
19.1.1.6.5 PRODUCT ACQUISITION
19.1.1.6.6 PRODUCTION CAPACITY EXPANSION
19.1.1.6.7 JOINT VENTURES
19.1.1.6.8 INNOVATIONS
19.1.1.6.9 PRODUCT LAUNCHES
19.1.1.7 RECENT NEWS
19.1.1.7.1 KRÜGER GROUP: RECENT NEWS
19.1.1.7.2 EVENTS
19.1.1.7.3 OTHERS
19.1.2 KERRY GROUP PLC
19.1.2.1 KERRY GROUP PLC, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.2.2 COMPANY OVERVIEW
19.1.2.2.1 KERRY GROUP PLC: COMPANY SNAPSHOT
19.1.2.3 REVENUE ANALYSIS
19.1.2.4 GEOGRAPHIC PRESENCE
19.1.2.5 PRODUCT PORTFOLIO
19.1.2.5.1 KERRY GROUP PLC: PRODUCT PORTFOLIO
19.1.2.6 RECENT DEVELOPMENTS
19.1.2.6.1 KERRY GROUP PLC: RECENT DEVELOPMENTS
19.1.2.6.2 MAJOR DEALS
19.1.2.6.3 M&A
19.1.2.6.4 COLLABORATION
19.1.2.6.5 PRODUCT ACQUISITION
19.1.2.6.6 PRODUCTION CAPACITY EXPANSION
19.1.2.6.7 JOINT VENTURES
19.1.2.6.8 INNOVATIONS
19.1.2.6.9 PRODUCT LAUNCHES
19.1.2.7 RECENT NEWS
19.1.2.7.1 KERRY GROUP PLC: RECENT NEWS
19.1.2.7.2 EVENTS
19.1.2.7.3 WEBINARS
19.1.2.7.4 OTHERS
19.1.3 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT)
19.1.3.1 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.3.2 COMPANY OVERVIEW
19.1.3.2.1 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): COMPANY SNAPSHOT
19.1.3.3 REVENUE ANALYSIS
19.1.3.4 GEOGRAPHIC PRESENCE
19.1.3.5 PRODUCT PORTFOLIO
19.1.3.5.1 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): PRODUCT PORTFOLIO
19.1.3.6 RECENT DEVELOPMENTS
19.1.3.6.1 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): RECENT DEVELOPMENTS
19.1.3.6.2 MAJOR DEALS
19.1.3.6.3 M&A
19.1.3.6.4 COLLABORATION
19.1.3.6.5 PRODUCTION CAPACITY EXPANSION
19.1.3.6.6 JOINT VENTURES
19.1.3.6.7 INNOVATIONS
19.1.3.6.8 PRODUCT LAUNCHES
19.1.3.7 RECENT NEWS
19.1.3.7.1 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): RECENT NEWS
19.1.3.7.2 EVENTS
19.1.3.7.3 CONFERENCES
19.1.3.7.4 WEBINARS
19.1.3.7.5 OTHERS
19.1.4 SANTHO HOLLAND FOOD
19.1.4.1 SANTHO HOLLAND FOOD, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.4.2 COMPANY OVERVIEW
19.1.4.2.1 SANTHO HOLLAND FOOD: COMPANY SNAPSHOT
19.1.4.3 REVENUE ANALYSIS
19.1.4.4 GEOGRAPHIC PRESENCE
19.1.4.5 PRODUCT PORTFOLIO
19.1.4.5.1 SANTHO HOLLAND FOOD: PRODUCT PORTFOLIO
19.1.4.5.2 MAJOR DEALS
19.1.4.5.3 M&A
19.1.4.5.4 COLLABORATION
19.1.4.5.5 INNOVATIONS
19.1.4.5.6 PRODUCT LAUNCHES
19.1.4.5.7 EVENTS
19.1.4.5.8 OTHERS
19.1.5 JDE PEET'S (SUPER)
19.1.5.1 JDE PEET'S (SUPER), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.5.2 COMPANY OVERVIEW
19.1.5.2.1 JDE PEET'S (SUPER): COMPANY SNAPSHOT
19.1.5.3 REVENUE ANALYSIS
19.1.5.4 GEOGRAPHIC PRESENCE
19.1.5.5 PRODUCT PORTFOLIO
19.1.5.5.1 JDE PEET'S (SUPER): PRODUCT PORTFOLIO
19.1.5.6 RECENT DEVELOPMENTS
19.1.5.6.1 JDE PEET'S (SUPER): RECENT DEVELOPMENTS
19.1.5.6.2 MAJOR DEALS
19.1.5.6.3 M&A
19.1.5.6.4 COLLABORATION
19.1.5.6.5 PRODUCT ACQUISITION
19.1.5.6.6 PRODUCTION CAPACITY EXPANSION
19.1.5.6.7 JOINT VENTURES
19.1.5.6.8 INNOVATIONS
19.1.5.6.9 PRODUCT LAUNCHES
19.1.5.7 RECENT NEWS
19.1.5.7.1 JDE PEET'S (SUPER): RECENT NEWS
19.1.5.7.2 EVENTS
19.1.5.7.3 CONFERENCES
19.1.5.7.4 SYMPOSIUMS
19.1.5.7.5 WEBINARS
19.1.5.7.6 OTHERS
19.1.6 DEK (GRANDOS)
19.1.6.1 DEK (GRANDOS), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.6.2 COMPANY OVERVIEW
19.1.6.2.1 DEK (GRANDOS): COMPANY SNAPSHOT
19.1.6.3 REVENUE ANALYSIS
19.1.6.4 GEOGRAPHIC PRESENCE
19.1.6.5 PRODUCT PORTFOLIO
19.1.6.5.1 DEK (GRANDOS): PRODUCT PORTFOLIO
19.1.6.5.2 MAJOR DEALS
19.1.6.5.3 M&A
19.1.6.5.4 COLLABORATION
19.1.6.5.5 PRODUCT ACQUISITION
19.1.6.5.6 PRODUCTION CAPACITY EXPANSION
19.1.6.5.7 JOINT VENTURES
19.1.6.5.8 INNOVATIONS
19.1.6.5.9 PRODUCT LAUNCHES
19.1.6.6 RECENT NEWS
19.1.6.6.1 DEK (GRANDOS): RECENT NEWS
19.1.6.6.2 EVENTS
19.1.6.6.3 CONFERENCES
19.1.6.6.4 SYMPOSIUMS
19.1.6.6.5 WEBINARS
19.1.6.6.6 OTHERS
19.1.7 DMK GROUP (TURM / DP SUPPLY)
19.1.7.1 DMK GROUP (TURM / DP SUPPLY), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.7.2 COMPANY OVERVIEW
19.1.7.2.1 DMK GROUP (TURM / DP SUPPLY): COMPANY SNAPSHOT
19.1.7.3 REVENUE ANALYSIS
19.1.7.4 GEOGRAPHIC PRESENCE
19.1.7.5 PRODUCT PORTFOLIO
19.1.7.5.1 DMK GROUP (TURM / DP SUPPLY): PRODUCT PORTFOLIO
19.1.7.6 RECENT DEVELOPMENTS
19.1.7.6.1 DMK GROUP (TURM / DP SUPPLY): RECENT DEVELOPMENTS
19.1.7.6.2 MAJOR DEALS
19.1.7.6.3 M&A
19.1.7.6.4 COLLABORATION
19.1.7.6.5 PRODUCT ACQUISITION
19.1.7.6.6 PRODUCTION CAPACITY EXPANSION
19.1.7.6.7 JOINT VENTURES
19.1.7.6.8 INNOVATIONS
19.1.7.6.9 PRODUCT LAUNCHES
19.1.7.7 RECENT NEWS
19.1.7.7.1 DMK GROUP (TURM / DP SUPPLY): RECENT NEWS
19.1.7.7.2 EVENTS
19.1.7.7.3 OTHERS
19.1.8 MOKATE INGREDIENTS
19.1.8.1 MOKATE INGREDIENTS, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.8.2 COMPANY OVERVIEW
19.1.8.2.1 MOKATE INGREDIENTS: COMPANY SNAPSHOT
19.1.8.3 REVENUE ANALYSIS
19.1.8.4 GEOGRAPHIC PRESENCE
19.1.8.5 PRODUCT PORTFOLIO
19.1.8.5.1 MOKATE INGREDIENTS: PRODUCT PORTFOLIO
19.1.8.6 RECENT DEVELOPMENTS
19.1.8.6.1 MOKATE INGREDIENTS: RECENT DEVELOPMENTS
19.1.8.6.2 MAJOR DEALS
19.1.8.6.3 M&A
19.1.8.6.4 COLLABORATION
19.1.8.6.5 PRODUCTION CAPACITY EXPANSION
19.1.8.6.6 INNOVATIONS
19.1.8.6.7 PRODUCT LAUNCHES
19.1.8.7 RECENT NEWS
19.1.8.7.1 MOKATE INGREDIENTS: RECENT NEWS
19.1.8.7.2 EVENTS
19.1.8.7.3 CONFERENCES
19.1.8.7.4 OTHERS
19.1.9 MEGGLE GROUP GMBH
19.1.9.1 MEGGLE GROUP GMBH, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.9.2 COMPANY OVERVIEW
19.1.9.2.1 MEGGLE GROUP GMBH: COMPANY SNAPSHOT
19.1.9.3 REVENUE ANALYSIS
19.1.9.4 GEOGRAPHIC PRESENCE
19.1.9.5 PRODUCT PORTFOLIO
19.1.9.5.1 MEGGLE GROUP GMBH: PRODUCT PORTFOLIO
19.1.9.6 RECENT DEVELOPMENTS
19.1.9.6.1 MEGGLE GROUP GMBH: RECENT DEVELOPMENTS
19.1.9.6.2 MAJOR DEALS
19.1.9.6.3 M&A
19.1.9.6.4 COLLABORATION
19.1.9.6.5 PRODUCT ACQUISITION
19.1.9.6.6 PRODUCTION CAPACITY EXPANSION
19.1.9.6.7 INNOVATIONS
19.1.9.6.8 PRODUCT LAUNCHES
19.1.9.7 RECENT NEWS
19.1.9.7.1 MEGGLE GROUP GMBH: RECENT NEWS
19.1.9.7.2 EVENTS
19.1.9.7.3 OTHERS
19.1.10 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN)
19.1.10.1 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.10.2 COMPANY OVERVIEW
19.1.10.2.1 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): COMPANY SNAPSHOT
19.1.10.3 REVENUE ANALYSIS
19.1.10.4 GEOGRAPHIC PRESENCE
19.1.10.5 PRODUCT PORTFOLIO
19.1.10.5.1 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): PRODUCT PORTFOLIO
19.1.10.6 RECENT DEVELOPMENTS
19.1.10.6.1 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): RECENT DEVELOPMENTS
19.1.10.6.2 MAJOR DEALS
19.1.10.6.3 M&A
19.1.10.6.4 COLLABORATION
19.1.10.6.5 PRODUCT ACQUISITION
19.1.10.6.6 PRODUCTION CAPACITY EXPANSION
19.1.10.6.7 JOINT VENTURES
19.1.10.6.8 INNOVATIONS
19.1.10.6.9 PRODUCT LAUNCHES
19.1.10.7 RECENT NEWS
19.1.10.7.1 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): RECENT NEWS
19.1.10.7.2 EVENTS
19.1.10.7.3 WEBINARS
19.1.10.7.4 OTHERS
19.1.11 WENHUI FOOD
19.1.11.1 WENHUI FOOD, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.11.2 COMPANY OVERVIEW
19.1.11.2.1 WENHUI FOOD: COMPANY SNAPSHOT
19.1.11.3 REVENUE ANALYSIS
19.1.11.4 GEOGRAPHIC PRESENCE
19.1.11.5 PRODUCT PORTFOLIO
19.1.11.5.1 WENHUI FOOD: PRODUCT PORTFOLIO
19.1.11.6 RECENT DEVELOPMENTS
19.1.11.6.1 WENHUI FOOD: RECENT DEVELOPMENTS
19.1.11.6.2 MAJOR DEALS
19.1.11.6.3 COLLABORATION
19.1.11.6.4 PRODUCT ACQUISITION
19.1.11.6.5 PRODUCTION CAPACITY EXPANSION
19.1.11.6.6 JOINT VENTURES
19.1.11.6.7 INNOVATIONS
19.1.11.6.8 PRODUCT LAUNCHES
19.1.11.7 RECENT NEWS
19.1.11.7.1 WENHUI FOOD: RECENT NEWS
19.1.11.7.2 EVENTS
19.1.11.7.3 CONFERENCES
19.1.11.7.4 WEBINARS
19.1.11.7.5 OTHERS
19.1.12 BIGTREE GROUP
19.1.12.1 BIGTREE GROUP, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.12.2 COMPANY OVERVIEW
19.1.12.2.1 BIGTREE GROUP: COMPANY SNAPSHOT
19.1.12.3 REVENUE ANALYSIS
19.1.12.4 GEOGRAPHIC PRESENCE
19.1.12.5 PRODUCT PORTFOLIO
19.1.12.5.1 BIGTREE GROUP: PRODUCT PORTFOLIO
19.1.12.6 RECENT DEVELOPMENTS
19.1.12.6.1 BIGTREE GROUP: RECENT DEVELOPMENTS
19.1.12.6.2 MAJOR DEALS
19.1.12.6.3 M&A
19.1.12.6.4 COLLABORATION
19.1.12.6.5 PRODUCT ACQUISITION
19.1.12.6.6 PRODUCTION CAPACITY EXPANSION
19.1.12.6.7 JOINT VENTURES
19.1.12.6.8 INNOVATIONS
19.1.12.6.9 PRODUCT LAUNCHES
19.1.12.7 RECENT NEWS
19.1.12.7.1 BIGTREE GROUP: RECENT NEWS
19.1.12.7.2 EVENTS
19.1.12.7.3 CONFERENCES
19.1.12.7.4 WEBINARS
19.1.12.7.5 OTHERS
19.1.13 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.
19.1.13.1 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD., SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.13.2 COMPANY OVERVIEW
19.1.13.2.1 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: COMPANY SNAPSHOT
19.1.13.3 REVENUE ANALYSIS
19.1.13.4 GEOGRAPHIC PRESENCE
19.1.13.5 PRODUCT PORTFOLIO
19.1.13.5.1 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: PRODUCT PORTFOLIO
19.1.13.6 RECENT DEVELOPMENTS
19.1.13.6.1 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: RECENT DEVELOPMENTS
19.1.13.6.2 MAJOR DEALS
19.1.13.6.3 M&A
19.1.13.6.4 COLLABORATION
19.1.13.6.5 PRODUCT ACQUISITION
19.1.13.6.6 PRODUCTION CAPACITY EXPANSION
19.1.13.6.7 JOINT VENTURES
19.1.13.6.8 INNOVATIONS
19.1.13.6.9 PRODUCT LAUNCHES
19.1.13.7 RECENT NEWS
19.1.13.7.1 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: RECENT NEWS
19.1.13.7.2 EVENTS
19.1.13.7.3 CONFERENCES
19.1.13.7.4 SYMPOSIUMS
19.1.13.7.5 WEBINARS
19.1.13.7.6 OTHERS
19.1.14 PT SANTOS PREMIUM KRIMER
19.1.14.1 PT SANTOS PREMIUM KRIMER, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.14.2 COMPANY OVERVIEW
19.1.14.2.1 PT SANTOS PREMIUM KRIMER: COMPANY SNAPSHOT
19.1.14.3 REVENUE ANALYSIS
19.1.14.4 GEOGRAPHIC PRESENCE
19.1.14.5 PRODUCT PORTFOLIO
19.1.14.5.1 PT SANTOS PREMIUM KRIMER: PRODUCT PORTFOLIO
19.1.14.6 RECENT DEVELOPMENTS
19.1.14.6.1 PT SANTOS PREMIUM KRIMER: RECENT DEVELOPMENTS
19.1.14.6.2 MAJOR DEALS
19.1.14.6.3 M&A
19.1.14.6.4 COLLABORATION
19.1.14.6.5 PRODUCT ACQUISITION
19.1.14.6.6 PRODUCTION CAPACITY EXPANSION
19.1.14.6.7 JOINT VENTURES
19.1.14.6.8 INNOVATIONS
19.1.14.6.9 PRODUCT LAUNCHES
19.1.14.7 RECENT NEWS
19.1.14.7.1 PT SANTOS PREMIUM KRIMER: RECENT NEWS
19.1.14.7.2 EVENTS
19.1.14.7.3 CONFERENCES
19.1.14.7.4 SYMPOSIUMS
19.1.14.7.5 WEBINARS
19.1.14.7.6 OTHERS
19.1.15 PT LAUTAN NATURAL KRIMERINDO
19.1.15.1 PT LAUTAN NATURAL KRIMERINDO, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.15.2 COMPANY OVERVIEW
19.1.15.2.1 PT LAUTAN NATURAL KRIMERINDO: COMPANY SNAPSHOT
19.1.15.3 REVENUE ANALYSIS
19.1.15.4 GEOGRAPHIC PRESENCE
19.1.15.5 PRODUCT PORTFOLIO
19.1.15.5.1 PT LAUTAN NATURAL KRIMERINDO: PRODUCT PORTFOLIO
19.1.15.6 RECENT DEVELOPMENTS
19.1.15.6.1 PT LAUTAN NATURAL KRIMERINDO: RECENT DEVELOPMENTS
19.1.15.6.2 MAJOR DEALS
19.1.15.6.3 M&A
19.1.15.6.4 OLLABORATION
19.1.15.6.5 PRODUCT ACQUISITION
19.1.15.6.6 PRODUCTION CAPACITY EXPANSION
19.1.15.6.7 JOINT VENTURES
19.1.15.6.8 INNOVATIONS
19.1.15.6.9 PRODUCT LAUNCHES
19.1.15.7 RECENT NEWS
19.1.15.7.1 PT LAUTAN NATURAL KRIMERINDO: RECENT NEWS
19.1.15.7.2 EVENTS
19.1.15.7.3 CONFERENCES
19.1.15.7.4 SYMPOSIUMS
19.1.15.7.5 WEBINARS
19.1.15.7.6 OTHERS
19.1.16 YEARRAKARN CO., LTD.
19.1.16.1 YEARRAKARN CO., LTD., SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.16.2 COMPANY OVERVIEW
19.1.16.2.1 YEARRAKARN CO., LTD.: COMPANY SNAPSHOT
19.1.16.3 REVENUE ANALYSIS
19.1.16.4 GEOGRAPHIC PRESENCE
19.1.16.5 PRODUCT PORTFOLIO
19.1.16.5.1 YEARRAKARN CO., LTD.: PRODUCT PORTFOLIO
19.1.16.6 RECENT DEVELOPMENTS
19.1.16.6.1 YEARRAKARN CO., LTD.: RECENT DEVELOPMENTS
19.1.16.6.2 MAJOR DEALS
19.1.16.6.3 M&A
19.1.16.6.4 COLLABORATION
19.1.16.6.5 PRODUCT ACQUISITION
19.1.16.6.6 PRODUCTION CAPACITY EXPANSION
19.1.16.6.7 JOINT VENTURES
19.1.16.6.8 INNOVATIONS
19.1.16.6.9 PRODUCT LAUNCHES
19.1.16.7 RECENT NEWS
19.1.16.7.1 YEARRAKARN CO., LTD.: RECENT NEWS
19.1.16.7.2 EVENTS
19.1.16.7.3 CONFERENCES
19.1.16.7.4 WEBINARS
19.1.16.7.5 OTHERS
19.1.17 UNIVERSAL ROBINA CORPORATION
19.1.17.1 UNIVERSAL ROBINA CORPORATION, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.17.2 COMPANY OVERVIEW
19.1.17.2.1 UNIVERSAL ROBINA CORPORATION: COMPANY SNAPSHOT
19.1.17.3 REVENUE ANALYSIS
19.1.17.4 GEOGRAPHIC PRESENCE
19.1.17.5 PRODUCT PORTFOLIO
19.1.17.5.1 UNIVERSAL ROBINA CORPORATION: PRODUCT PORTFOLIO
19.1.17.6 RECENT DEVELOPMENTS
19.1.17.6.1 UNIVERSAL ROBINA CORPORATION: RECENT DEVELOPMENTS
19.1.17.6.2 MAJOR DEALS
19.1.17.6.3 M&A
19.1.17.6.4 COLLABORATION
19.1.17.6.5 PRODUCT ACQUISITION
19.1.17.6.6 PRODUCTION CAPACITY EXPANSION
19.1.17.6.7 JOINT VENTURES
19.1.17.6.8 INNOVATIONS
19.1.17.6.9 PRODUCT LAUNCHES
19.1.17.7 RECENT NEWS
19.1.17.7.1 UNIVERSAL ROBINA CORPORATION: RECENT NEWS
19.1.17.7.2 EVENTS
19.1.17.7.3 CONFERENCES
19.1.17.7.4 WEBINARS
19.1.17.7.5 OTHERS
19.1.18 ASIA SAIGON FOOD INGREDIENTS
19.1.18.1 ASIA SAIGON FOOD INGREDIENTS, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.18.2 COMPANY OVERVIEW
19.1.18.2.1 ASIA SAIGON FOOD INGREDIENTS: COMPANY SNAPSHOT
19.1.18.3 REVENUE ANALYSIS
19.1.18.4 GEOGRAPHIC PRESENCE
19.1.18.5 PRODUCT PORTFOLIO
19.1.18.5.1 ASIA SAIGON FOOD INGREDIENTS: PRODUCT PORTFOLIO
19.1.18.6 RECENT DEVELOPMENTS
19.1.18.6.1 ASIA SAIGON FOOD INGREDIENTS: RECENT DEVELOPMENTS
19.1.18.6.2 MAJOR DEALS
19.1.18.6.3 M&A
19.1.18.6.4 COLLABORATION
19.1.18.6.5 PRODUCT ACQUISITION
19.1.18.6.6 PRODUCTION CAPACITY EXPANSION
19.1.18.6.7 JOINT VENTURES
19.1.18.6.8 INNOVATIONS
19.1.18.7 RECENT NEWS
19.1.18.7.1 ASIA SAIGON FOOD INGREDIENTS: RECENT NEWS
19.1.18.7.2 EVENTS
19.1.18.7.3 CONFERENCES
19.1.18.7.4 SYMPOSIUMS
19.1.18.7.5 WEBINARS
19.1.18.7.6 OTHERS
19.1.19 DONG SUH COMPANIES (FRIMA)
19.1.19.1 DONG SUH COMPANIES (FRIMA), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.19.2 COMPANY OVERVIEW
19.1.19.2.1 DONG SUH COMPANIES (FRIMA): COMPANY SNAPSHOT
19.1.19.3 REVENUE ANALYSIS
19.1.19.4 GEOGRAPHIC PRESENCE
19.1.19.5 PRODUCT PORTFOLIO
19.1.19.5.1 DONG SUH COMPANIES (FRIMA): PRODUCT PORTFOLIO
19.1.19.6 RECENT DEVELOPMENTS
19.1.19.6.1 DONG SUH COMPANIES (FRIMA): RECENT DEVELOPMENTS
19.1.19.6.2 MAJOR DEALS
19.1.19.6.3 M&A
19.1.19.6.4 COLLABORATION
19.1.19.6.5 PRODUCT ACQUISITION
19.1.19.6.6 PRODUCTION CAPACITY EXPANSION
19.1.19.6.7 JOINT VENTURES
19.1.19.6.8 INNOVATIONS
19.1.19.6.9 PRODUCT LAUNCHES
19.1.19.7 RECENT NEWS
19.1.19.7.1 DONG SUH COMPANIES (FRIMA): RECENT NEWS
19.1.19.7.2 EVENTS
19.1.19.7.3 OTHERS
19.1.20 CUSTOM FOOD GROUP
19.1.20.1 CUSTOM FOOD GROUP, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
19.1.20.2 COMPANY OVERVIEW
19.1.20.2.1 CUSTOM FOOD GROUP: COMPANY SNAPSHOT
19.1.20.3 REVENUE ANALYSIS
19.1.20.4 GEOGRAPHIC PRESENCE
19.1.20.5 PRODUCT PORTFOLIO
19.1.20.5.1 CUSTOM FOOD GROUP: PRODUCT PORTFOLIO
19.1.20.6 RECENT DEVELOPMENTS
19.1.20.6.1 CUSTOM FOOD GROUP: RECENT DEVELOPMENTS
19.1.20.6.2 MAJOR DEALS
19.1.20.6.3 M&A
19.1.20.6.4 COLLABORATION
19.1.20.6.5 PRODUCT ACQUISITION
19.1.20.6.6 PRODUCTION CAPACITY EXPANSION
19.1.20.6.7 JOINT VENTURES
19.1.20.6.8 INNOVATIONS
19.1.20.6.9 PRODUCT LAUNCHES
19.1.20.7 RECENT NEWS
19.1.20.7.1 CUSTOM FOOD GROUP: RECENT NEWS
19.1.20.7.2 EVENTS
19.1.20.7.3 CONFERENCES
19.1.20.7.4 OTHERS
20 RELATED REPORTS
21 QUESTIONNAIRE
List of Table
TABLE 1 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: SEGMENTATION
TABLE 2 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: GEOGRAPHIC SCOPE
TABLE 3 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: RESEARCH SNAPSHOT
TABLE 4 PRODUCT POSITIONING: STANDARD NDC -> FUNCTIONAL / SPECIALTY NDC: IMPACT ANALYSIS
TABLE 5 APPLICATION: INSTANT COFFEE -> 3-IN-1 COFFEE AND TEA PREMIXES: IMPACT ANALYSIS
TABLE 6 IMPACT TABLE: IMPACT ANALYSIS
TABLE 7 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: SEGMENTATION AT A GLANCE, 2025
TABLE 8 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PORTER'S FIVE FORCES
TABLE 9 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: DISCLOSED DEVELOPMENT AND LAUNCH ACTIVITY
TABLE 10 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PROMINENT COMPANIES
TABLE 11 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: SMALL AND MEDIUM SIZE COMPANIES
TABLE 12 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: END USERS AND THEIR PURCHASE DRIVERS
TABLE 13 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2018-2025 (USD MILLION)
TABLE 14 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2026-2033 (USD MILLION)
TABLE 15 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 16 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 17 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 18 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 19 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 20 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 21 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 22 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 23 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 24 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 25 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 26 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 27 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 28 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 29 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 30 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 31 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 32 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 33 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 34 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 35 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 36 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 37 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 38 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 39 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 40 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 41 ASIA PACIFIC, BY COUNTRY, 2018-2025 (USD MILLION)
TABLE 42 ASIA PACIFIC, BY COUNTRY, 2026-2033 (USD MILLION)
TABLE 43 ASIA PACIFIC, BY COUNTRY, 2018-2025 (METRIC TONS (MT))
TABLE 44 ASIA PACIFIC, BY COUNTRY, 2026-2033 (METRIC TONS (MT))
TABLE 45 ASIA PACIFIC, BY FORM, 2018-2025 (USD MILLION)
TABLE 46 ASIA PACIFIC, BY FORM, 2026-2033 (USD MILLION)
TABLE 47 ASIA PACIFIC, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 48 ASIA PACIFIC, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 49 ASIA PACIFIC, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 50 ASIA PACIFIC, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 51 ASIA PACIFIC, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 52 ASIA PACIFIC, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 53 ASIA PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 54 ASIA PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 55 ASIA PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 56 ASIA PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 57 ASIA PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 58 ASIA PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 59 ASIA PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 60 ASIA PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 61 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 62 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 63 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 64 ASIA PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 65 ASIA PACIFIC, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 66 ASIA PACIFIC, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 67 ASIA PACIFIC, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 68 ASIA PACIFIC, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 69 ASIA PACIFIC, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 70 ASIA PACIFIC, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 71 ASIA PACIFIC, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 72 ASIA PACIFIC, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 73 CHINA, BY FORM, 2018-2025 (USD MILLION)
TABLE 74 CHINA, BY FORM, 2026-2033 (USD MILLION)
TABLE 75 CHINA, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 76 CHINA, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 77 CHINA, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 78 CHINA, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 79 CHINA, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 80 CHINA, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 81 CHINA, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 82 CHINA, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 83 CHINA, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 84 CHINA, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 85 CHINA, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 86 CHINA, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 87 CHINA, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 88 CHINA, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 89 CHINA, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 90 CHINA, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 91 CHINA, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 92 CHINA, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 93 CHINA, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 94 CHINA, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 95 CHINA, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 96 CHINA, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 97 CHINA, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 98 CHINA, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 99 CHINA, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 100 CHINA, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 101 JAPAN, BY FORM, 2018-2025 (USD MILLION)
TABLE 102 JAPAN, BY FORM, 2026-2033 (USD MILLION)
TABLE 103 JAPAN, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 104 JAPAN, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 105 JAPAN, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 106 JAPAN, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 107 JAPAN, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 108 JAPAN, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 109 JAPAN, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 110 JAPAN, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 111 JAPAN, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 112 JAPAN, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 113 JAPAN, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 114 JAPAN, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 115 JAPAN, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 116 JAPAN, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 117 JAPAN, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 118 JAPAN, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 119 JAPAN, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 120 JAPAN, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 121 JAPAN, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 122 JAPAN, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 123 JAPAN, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 124 JAPAN, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 125 JAPAN, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 126 JAPAN, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 127 JAPAN, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 128 JAPAN, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 129 INDIA, BY FORM, 2018-2025 (USD MILLION)
TABLE 130 INDIA, BY FORM, 2026-2033 (USD MILLION)
TABLE 131 INDIA, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 132 INDIA, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 133 INDIA, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 134 INDIA, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 135 INDIA, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 136 INDIA, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 137 INDIA, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 138 INDIA, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 139 INDIA, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 140 INDIA, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 141 INDIA, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 142 INDIA, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 143 INDIA, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 144 INDIA, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 145 INDIA, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 146 INDIA, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 147 INDIA, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 148 INDIA, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 149 INDIA, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 150 INDIA, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 151 INDIA, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 152 INDIA, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 153 INDIA, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 154 INDIA, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 155 INDIA, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 156 INDIA, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 157 SOUTH KOREA, BY FORM, 2018-2025 (USD MILLION)
TABLE 158 SOUTH KOREA, BY FORM, 2026-2033 (USD MILLION)
TABLE 159 SOUTH KOREA, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 160 SOUTH KOREA, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 161 SOUTH KOREA, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 162 SOUTH KOREA, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 163 SOUTH KOREA, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 164 SOUTH KOREA, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 165 SOUTH KOREA, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 166 SOUTH KOREA, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 167 SOUTH KOREA, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 168 SOUTH KOREA, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 169 SOUTH KOREA, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 170 SOUTH KOREA, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 171 SOUTH KOREA, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 172 SOUTH KOREA, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 173 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 174 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 175 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 176 SOUTH KOREA, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 177 SOUTH KOREA, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 178 SOUTH KOREA, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 179 SOUTH KOREA, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 180 SOUTH KOREA, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 181 SOUTH KOREA, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 182 SOUTH KOREA, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 183 SOUTH KOREA, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 184 SOUTH KOREA, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 185 AUSTRALIA & NEW ZEALAND, BY FORM, 2018-2025 (USD MILLION)
TABLE 186 AUSTRALIA & NEW ZEALAND, BY FORM, 2026-2033 (USD MILLION)
TABLE 187 AUSTRALIA & NEW ZEALAND, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 188 AUSTRALIA & NEW ZEALAND, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 189 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 190 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 191 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 192 AUSTRALIA & NEW ZEALAND, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 193 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 194 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 195 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 196 AUSTRALIA & NEW ZEALAND, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 197 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 198 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 199 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 200 AUSTRALIA & NEW ZEALAND, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 201 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 202 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 203 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 204 AUSTRALIA & NEW ZEALAND, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 205 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 206 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 207 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 208 AUSTRALIA & NEW ZEALAND, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 209 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 210 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 211 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 212 AUSTRALIA & NEW ZEALAND, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 213 REST OF ASIA-PACIFIC, BY FORM, 2018-2025 (USD MILLION)
TABLE 214 REST OF ASIA-PACIFIC, BY FORM, 2026-2033 (USD MILLION)
TABLE 215 REST OF ASIA-PACIFIC, BY FORM, 2018-2025 (METRIC TONS (MT))
TABLE 216 REST OF ASIA-PACIFIC, BY FORM, 2026-2033 (METRIC TONS (MT))
TABLE 217 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2018-2025 (USD MILLION)
TABLE 218 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2026-2033 (USD MILLION)
TABLE 219 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2018-2025 (METRIC TONS (MT))
TABLE 220 REST OF ASIA-PACIFIC, BY FAT CONTENT, 2026-2033 (METRIC TONS (MT))
TABLE 221 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (USD MILLION)
TABLE 222 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (USD MILLION)
TABLE 223 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2018-2025 (METRIC TONS (MT))
TABLE 224 REST OF ASIA-PACIFIC, BY FAT / OIL SOURCE, 2026-2033 (METRIC TONS (MT))
TABLE 225 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (USD MILLION)
TABLE 226 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (USD MILLION)
TABLE 227 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2018-2025 (METRIC TONS (MT))
TABLE 228 REST OF ASIA-PACIFIC, BY PRODUCT POSITIONING, 2026-2033 (METRIC TONS (MT))
TABLE 229 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (USD MILLION)
TABLE 230 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (USD MILLION)
TABLE 231 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2018-2025 (METRIC TONS (MT))
TABLE 232 REST OF ASIA-PACIFIC, BY FORMULATION / CERTIFICATION, 2026-2033 (METRIC TONS (MT))
TABLE 233 REST OF ASIA-PACIFIC, BY APPLICATION, 2018-2025 (USD MILLION)
TABLE 234 REST OF ASIA-PACIFIC, BY APPLICATION, 2026-2033 (USD MILLION)
TABLE 235 REST OF ASIA-PACIFIC, BY APPLICATION, 2018-2025 (METRIC TONS (MT))
TABLE 236 REST OF ASIA-PACIFIC, BY APPLICATION, 2026-2033 (METRIC TONS (MT))
TABLE 237 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2018-2025 (USD MILLION)
TABLE 238 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2026-2033 (USD MILLION)
TABLE 239 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2018-2025 (METRIC TONS (MT))
TABLE 240 REST OF ASIA-PACIFIC, BY CUSTOMER TYPE, 2026-2033 (METRIC TONS (MT))
TABLE 241 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: ESTIMATED COMPANY SHARE, GLOBAL, 2025
TABLE 242 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: MERGERS & ACQUISITIONS
TABLE 243 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: NEW PRODUCT DEVELOPMENT & APPROVALS
TABLE 244 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: EXPANSIONS
TABLE 245 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PARTNERSHIP AND OTHER STRATEGIC DEVELOPMENTS
TABLE 246 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC): SWOT ANALYSIS
TABLE 247 KRÜGER GROUP: PRODUCT PORTFOLIO
TABLE 248 KRÜGER GROUP: RECENT DEVELOPMENTS
TABLE 249 KRÜGER GROUP: RECENT NEWS
TABLE 250 KERRY GROUP PLC: PRODUCT PORTFOLIO
TABLE 251 KERRY GROUP PLC: RECENT DEVELOPMENTS
TABLE 252 KERRY GROUP PLC: RECENT NEWS
TABLE 253 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): COMPANY SNAPSHOT
TABLE 254 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): PRODUCT PORTFOLIO
TABLE 255 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): RECENT DEVELOPMENTS
TABLE 256 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT): RECENT NEWS
TABLE 257 SANTHO HOLLAND FOOD: COMPANY SNAPSHOT
TABLE 258 SANTHO HOLLAND FOOD: PRODUCT PORTFOLIO
TABLE 259 JDE PEET'S (SUPER): COMPANY SNAPSHOT
TABLE 260 JDE PEET'S (SUPER): PRODUCT PORTFOLIO
TABLE 261 JDE PEET'S (SUPER): RECENT DEVELOPMENTS
TABLE 262 JDE PEET'S (SUPER): RECENT NEWS
TABLE 263 DEK (GRANDOS): COMPANY SNAPSHOT
TABLE 264 DEK (GRANDOS): PRODUCT PORTFOLIO
TABLE 265 DEK (GRANDOS): RECENT NEWS
TABLE 266 DMK GROUP (TURM / DP SUPPLY): COMPANY SNAPSHOT
TABLE 267 DMK GROUP (TURM / DP SUPPLY): PRODUCT PORTFOLIO
TABLE 268 DMK GROUP (TURM / DP SUPPLY): RECENT DEVELOPMENTS
TABLE 269 DMK GROUP (TURM / DP SUPPLY): RECENT NEWS
TABLE 270 MOKATE INGREDIENTS: COMPANY SNAPSHOT
TABLE 271 MOKATE INGREDIENTS: PRODUCT PORTFOLIO
TABLE 272 MOKATE INGREDIENTS: RECENT DEVELOPMENTS
TABLE 273 MOKATE INGREDIENTS: RECENT NEWS
TABLE 274 MEGGLE GROUP GMBH: COMPANY SNAPSHOT
TABLE 275 MEGGLE GROUP GMBH: PRODUCT PORTFOLIO
TABLE 276 MEGGLE GROUP GMBH: RECENT DEVELOPMENTS
TABLE 277 MEGGLE GROUP GMBH: RECENT NEWS
TABLE 278 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): COMPANY SNAPSHOT
TABLE 279 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): PRODUCT PORTFOLIO
TABLE 280 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): RECENT DEVELOPMENTS
TABLE 281 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN): RECENT NEWS
TABLE 282 WENHUI FOOD: COMPANY SNAPSHOT
TABLE 283 WENHUI FOOD: PRODUCT PORTFOLIO
TABLE 284 WENHUI FOOD: RECENT DEVELOPMENTS
TABLE 285 WENHUI FOOD: RECENT NEWS
TABLE 286 BIGTREE GROUP: COMPANY SNAPSHOT
TABLE 287 BIGTREE GROUP: PRODUCT PORTFOLIO
TABLE 288 BIGTREE GROUP: RECENT DEVELOPMENTS
TABLE 289 BIGTREE GROUP: RECENT NEWS
TABLE 290 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: COMPANY SNAPSHOT
TABLE 291 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: PRODUCT PORTFOLIO
TABLE 292 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: RECENT DEVELOPMENTS
TABLE 293 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD.: RECENT NEWS
TABLE 294 PT SANTOS PREMIUM KRIMER: COMPANY SNAPSHOT
TABLE 295 PT SANTOS PREMIUM KRIMER: PRODUCT PORTFOLIO
TABLE 296 PT SANTOS PREMIUM KRIMER: RECENT DEVELOPMENTS
TABLE 297 PT SANTOS PREMIUM KRIMER: RECENT NEWS
TABLE 298 PT LAUTAN NATURAL KRIMERINDO: COMPANY SNAPSHOT
TABLE 299 PT LAUTAN NATURAL KRIMERINDO: PRODUCT PORTFOLIO
TABLE 300 PT LAUTAN NATURAL KRIMERINDO: RECENT DEVELOPMENTS
TABLE 301 PT LAUTAN NATURAL KRIMERINDO: RECENT NEWS
TABLE 302 YEARRAKARN CO., LTD.: COMPANY SNAPSHOT
TABLE 303 YEARRAKARN CO., LTD.: PRODUCT PORTFOLIO
TABLE 304 YEARRAKARN CO., LTD.: RECENT DEVELOPMENTS
TABLE 305 YEARRAKARN CO., LTD.: RECENT NEWS
TABLE 306 UNIVERSAL ROBINA CORPORATION: COMPANY SNAPSHOT
TABLE 307 UNIVERSAL ROBINA CORPORATION: PRODUCT PORTFOLIO
TABLE 308 UNIVERSAL ROBINA CORPORATION: RECENT DEVELOPMENTS
TABLE 309 UNIVERSAL ROBINA CORPORATION: RECENT NEWS
TABLE 310 ASIA SAIGON FOOD INGREDIENTS: COMPANY SNAPSHOT
TABLE 311 ASIA SAIGON FOOD INGREDIENTS: PRODUCT PORTFOLIO
TABLE 312 ASIA SAIGON FOOD INGREDIENTS: RECENT DEVELOPMENTS
TABLE 313 ASIA SAIGON FOOD INGREDIENTS: RECENT NEWS
TABLE 314 DONG SUH COMPANIES (FRIMA): COMPANY SNAPSHOT
TABLE 315 DONG SUH COMPANIES (FRIMA): PRODUCT PORTFOLIO
TABLE 316 DONG SUH COMPANIES (FRIMA): RECENT DEVELOPMENTS
TABLE 317 DONG SUH COMPANIES (FRIMA): RECENT NEWS
TABLE 318 CUSTOM FOOD GROUP: COMPANY SNAPSHOT
TABLE 319 CUSTOM FOOD GROUP: PRODUCT PORTFOLIO
TABLE 320 CUSTOM FOOD GROUP: RECENT DEVELOPMENTS
TABLE 321 CUSTOM FOOD GROUP: RECENT NEWS
List of Figure
FIGURE 1 YEARS CONSIDERED FOR THE STUDY
FIGURE 2 RESEARCH APPROACH: PRIMARY AND SECONDARY RESOURCES
FIGURE 3 HISTORICAL DATA BUILD-UP
FIGURE 4 DROC ANALYSIS
FIGURE 5 PARENT MARKET AND TARGET MARKET
FIGURE 6 ARRIVING AT THE MARKET SIZE
FIGURE 7 MARKET COVERAGE GRID: ROUTES TO MARKET EVIDENCED IN PUBLISHED SOURCES
FIGURE 8 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC): KEY FINDINGS
FIGURE 9 PRODUCT POSITIONING: STANDARD NDC -> FUNCTIONAL / SPECIALTY NDC: DRIVER IMPACT ANALYSIS
FIGURE 10 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2018-2033 (USD MILLION)
FIGURE 11 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET: PESTLE ANALYSIS
FIGURE 12 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM: KEY FINDINGS
FIGURE 13 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2025
FIGURE 14 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORM, 2033 (USD MILLION)
FIGURE 15 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT: KEY FINDINGS
FIGURE 16 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2025
FIGURE 17 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT CONTENT, 2033 (USD MILLION)
FIGURE 18 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE: KEY FINDINGS
FIGURE 19 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2025
FIGURE 20 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FAT / OIL SOURCE, 2033 (USD MILLION)
FIGURE 21 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING: KEY FINDINGS
FIGURE 22 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2025
FIGURE 23 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY PRODUCT POSITIONING, 2033 (USD MILLION)
FIGURE 24 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION: KEY FINDINGS
FIGURE 25 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2025
FIGURE 26 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY FORMULATION / CERTIFICATION, 2033 (USD MILLION)
FIGURE 27 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION: KEY FINDINGS
FIGURE 28 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2025
FIGURE 29 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY APPLICATION, 2033 (USD MILLION)
FIGURE 30 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE: KEY FINDINGS
FIGURE 31 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2025
FIGURE 32 ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, BY CUSTOMER TYPE, 2033 (USD MILLION)
FIGURE 33 ASIA PACIFIC, BY COUNTRY, 2025
FIGURE 34 KRÜGER GROUP, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 35 KRÜGER GROUP: COMPANY SNAPSHOT
FIGURE 36 KERRY GROUP PLC, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 37 KERRY GROUP PLC: COMPANY SNAPSHOT
FIGURE 38 ROYAL FRIESLANDCAMPINA N.V. (KIEVIT), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 39 SANTHO HOLLAND FOOD, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 40 JDE PEET'S (SUPER), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 41 DEK (GRANDOS), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 42 DMK GROUP (TURM / DP SUPPLY), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 43 MOKATE INGREDIENTS, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 44 MEGGLE GROUP GMBH, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 45 SUZHOU JIAHE FOODS INDUSTRY CO., LTD. (COGRAIN), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 46 WENHUI FOOD, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 47 BIGTREE GROUP, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 48 ZHUCHENG DONGXIAO BIOTECHNOLOGY CO., LTD., SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 49 PT SANTOS PREMIUM KRIMER, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 50 PT LAUTAN NATURAL KRIMERINDO, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 51 YEARRAKARN CO., LTD., SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 52 UNIVERSAL ROBINA CORPORATION, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 53 ASIA SAIGON FOOD INGREDIENTS, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 54 DONG SUH COMPANIES (FRIMA), SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025
FIGURE 55 CUSTOM FOOD GROUP, SHARE OF THE ASIA-PACIFIC B2B NON-DAIRY CREAMER (NDC) MARKET, 2025

Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.