What is the Active Spoiler Market Size and Growth Rate?
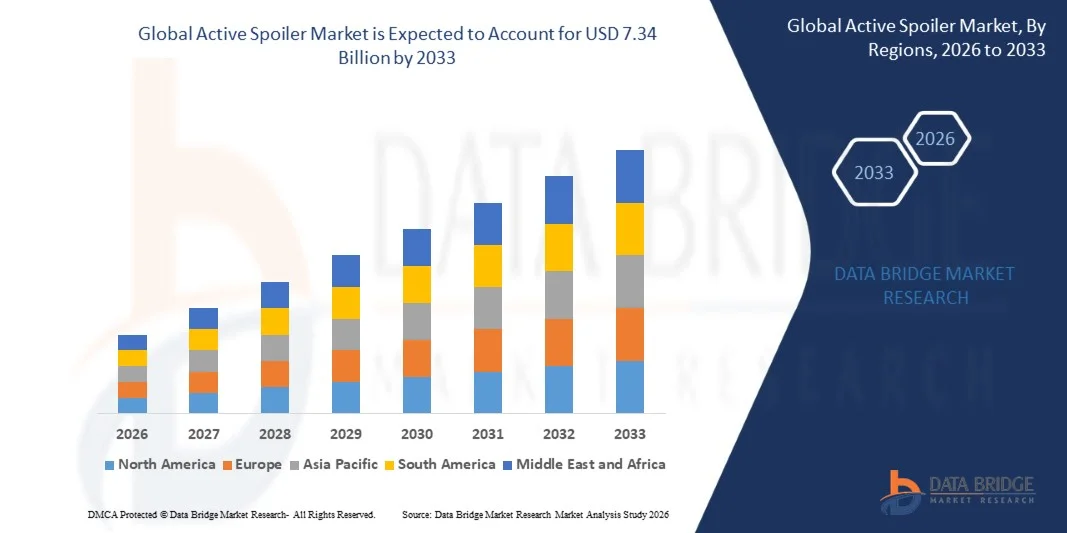
- As per Data Bridge Market Research analysis, the active spoiler market was valued at USD 4.27 billion in 2025 and is projected to reach USD 7.34 billion by 2033, growing at a CAGR of 7.00% from 2026 to 2033.
- The market is witnessing steady expansion driven by tightening emission and fuel-economy regulations, the rapid electrification of vehicle fleets, and rising consumer demand for performance-oriented and aerodynamically optimized vehicle designs.
- Active spoilers are electronically controlled aerodynamic devices that automatically adjust their height, angle, or deployment in real time based on vehicle speed, braking force, steering input, and selected drive mode. By dynamically balancing drag reduction against downforce generation, these systems improve high-speed stability, cornering performance, braking response, and energy efficiency. Their migration from supercars and luxury sedans into mainstream premium SUVs and battery electric vehicles, where every percentage point of drag reduction translates directly into driving range, is the central growth story of this market.
Market Size & Forecast
- Global Market Value (2025): USD 4.27 Billion
- Expected Market Value (2033): USD 7.34 Billion
- Forecast CAGR (2026–2033): 7.00%
- Leading Region in 2025: Europe
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Active Spoiler Market?
- Europe dominated the global active spoiler market with the largest revenue share of 34.62% in 2025, supported by the concentration of premium and performance vehicle manufacturers, stringent CO2 regulations, and a mature Tier-1 aerodynamic component supply base.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 9.1% from 2026 to 2033, driven by surging electric vehicle production in China, expanding premium vehicle demand in India and Southeast Asia, and rapid localization of active aerodynamic component manufacturing.
- The rear active spoilers segment led the market with a 46.28% share in 2025, owing to its established use across sports cars, luxury sedans, and performance SUVs, and its proven contribution to high-speed stability and braking balance.
- Active front splitters and air dams are the fastest-growing spoiler type, projected to register a CAGR of 8.4%, reflecting the growing use of front-end aerodynamic management to reduce lift and manage underbody airflow on electric platforms.
- The electro-mechanical actuation segment dominated the actuation category with a 58.34% revenue share in 2025, favoured for its precise positioning, low maintenance requirement, and straightforward integration with vehicle electronic architectures.
- Internal combustion engine vehicles accounted for 55.12% of the market in 2025, but battery electric vehicles represent the fastest-growing propulsion segment at a CAGR of 10.2%, as OEMs pursue drag reduction to extend real-world range.
- The AI and predictive control segment is the fastest-growing control technology category, with a CAGR of 9.4%, driven by the integration of active aerodynamics with navigation data, ADAS sensor fusion, and driver behaviour models.
Report Scope and Active Spoiler Market Segmentation
|
Attributes |
Active Spoiler Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Active Spoiler Market?
- Electric vehicle manufacturers are adopting active aerodynamic systems as a range-extension technology, shifting the value proposition of active spoilers from motorsport-inspired styling toward measurable energy efficiency gains.
- Aerodynamic drag accounts for the largest share of energy consumption at highway speeds, so even a modest reduction in the drag coefficient translates into additional kilometres of range without any increase in battery capacity, weight, or cost.
- For instance, in January 2024, Porsche held the world premiere of the all-electric Macan featuring Porsche Active Aerodynamics (PAA), a system combining an adaptive rear spoiler, active cooling flaps on the front air intakes, and a fully sealed underbody with flexible covers, achieving a drag coefficient of 0.25 compared with 0.35 on the previous generation.
- Premium and high-performance manufacturers are extending active aerodynamics from a single rear wing to coordinated multi-element systems that operate as an integrated whole across the vehicle body.
- For instance, in October 2024, Ferrari unveiled the F80, whose active rear wing contributes 590 kg of the car's total 1,050 kg of downforce at 250 km/h and deploys automatically in response to acceleration, steering wheel input, and heavy braking, working in concert with a front triplane wing, S-Duct, and rear diffuser.
- As electrification continues and range anxiety remains a key purchase consideration, active aerodynamic systems are expected to move progressively down-market from flagship models into mainstream premium and volume segments, reinforcing active spoilers as a core efficiency technology rather than a performance accessory.
What are the Key Drivers of the Active Spoiler Market?
- Tightening global emission and fuel-economy standards are compelling automakers to pursue every available efficiency lever, and aerodynamic optimization delivers meaningful CO2 reduction without powertrain redesign or additional battery cost.
- Active aerodynamic devices allow manufacturers to achieve low-drag configurations at cruising speed while retaining the downforce required for stability and safety during high-speed manoeuvring and braking, a trade-off that fixed spoilers cannot resolve.
- For instance, in April 2024, Porsche detailed how the Macan automatically assumes its optimal aerodynamic configuration when cruising, with the rear spoiler moving into its Eco position, the air flaps closing, and the chassis lowering, with the company's aerodynamics team stating that the active elements contribute significantly to range.
- Tier-1 suppliers are investing in integrated active aerodynamic product lines that combine actuators, control electronics, and lightweight moving surfaces, lowering the engineering burden for OEMs and accelerating adoption across vehicle platforms.
- For instance, in January 2022, Magna launched a first-to-market, high-volume active air deflector on the Ram 1500 which, combined with the company's active grille shutter, delivered a nearly 7% reduction in drag and a 1 mpg highway fuel saving, establishing the commercial template for the active aerodynamics portfolio the company has since expanded across vehicle segments.
- With regulators tightening efficiency targets and electrified platforms placing a premium on drag reduction, active spoilers and allied active aerodynamic devices are expected to remain a priority investment area for both OEMs and their component partners through the forecast period.
Which Factors are Challenging the Growth of the Active Spoiler Market?
- Active spoiler systems require actuators, position sensors, control electronics, reinforced mounting structures, and sealing solutions, which substantially increase component cost compared with a fixed moulded spoiler.
- These costs restrict adoption in entry-level and mid-segment vehicles, particularly in price-sensitive markets where manufacturers face intense pressure on bill-of-materials expenditure.
- Moving exterior components also introduce durability, warranty, and reliability exposure, since actuators and linkages must operate reliably across extreme temperatures, road salt, dust, vibration, and thousands of deployment cycles over the vehicle lifetime.
- For instance, in October 2024, General Motors confirmed that the 2025 Chevrolet Corvette ZR1 would launch with a fixed rather than active aerodynamic package, with the programme's chief engineer stating that nearly every active aero system the team had tested existed to enable an aesthetic rather than to deliver a performance benefit that a well-designed fixed installation could not already provide.
- High system cost, added mass, packaging complexity, and long-term serviceability concerns continue to limit the penetration of active spoilers beyond premium and performance vehicle segments. Until actuation and control costs fall substantially, adoption in high-volume mainstream vehicles is expected to remain selective, restraining the pace of market expansion in emerging and cost-sensitive regions.
How is the Active Spoiler Market Segmented?
The active spoiler market is segmented on the basis of spoiler type, actuation type, material, vehicle type, propulsion, control technology, component, functionality, application and sales channel.
- By Spoiler Type
On the basis of spoiler type, the global active spoiler market is segmented into rear active spoilers, active front splitters & air dams, roof-mounted active spoilers, and adaptive rear wings. The rear active spoilers segment dominated the market with a 46.28% share in 2025, owing to its long-established application across sports cars, luxury sedans, and performance SUVs, where deployable rear surfaces deliver the most direct improvement in high-speed stability, braking balance, and rear-axle downforce. The maturity of the supply base, proven durability, and comparatively straightforward packaging at the rear deck continue to make this the default configuration for OEM active aerodynamic programmers.
The active front splitters & air dams segment is projected to register the fastest growth at a CAGR of 8.4% from 2026 to 2033, driven by growing recognition that front-end airflow management is essential to controlling lift balance and underbody flow on low-slung electric platforms. Rising adoption of coordinated front-and-rear aerodynamic strategies, together with expanding supplier capability in deployable front-end components, is accelerating segment expansion.
- By Actuation Type
On the basis of actuation type, the global active spoiler market is segmented into electro-mechanical actuation, hydraulic actuation, pneumatic & inflatable actuation, and shape-memory & smart actuation. The electro-mechanical actuation segment led the market with a 58.34% share in 2025, supported by precise position control, compatibility with 12V and 48V vehicle electrical architectures, lower maintenance requirements than hydraulic alternatives, and the wide availability of automotive-grade actuators from established suppliers.
The pneumatic & inflatable actuation segment is expected to experience the fastest growth at a CAGR of 8.9% from 2026 to 2033, driven by interest in lightweight, low-complexity aerodynamic surfaces that avoid the mass and packaging penalty of individual electric motors and their supporting hardware. Ongoing patent activity and concept development among premium manufacturers are expanding the technical feasibility of this approach.
- By Material
On the basis of material, the global active spoiler market is segmented into thermoplastics & polymer composites, carbon fiber reinforced polymer, fiberglass & SMC, and aluminum & light alloys. The thermoplastics & polymer composites segment dominated the market with a share of 42.17% in 2025 due to favourable cost economics, high-volume moulding capability, corrosion resistance, and design freedom that allows complex aerodynamic geometries to be produced consistently at scale. Established injection moulding capacity among global exterior component suppliers further reinforces this segment’s leading position.
The carbon fiber reinforced polymer segment is anticipated to witness the fastest CAGR of 8.7% from 2026 to 2033, driven by the weight sensitivity of moving aerodynamic components, where reduced mass lowers actuator load, improves response time, and enhances durability. Falling composite processing costs and growing use of carbon fiber in performance and high-end electric vehicles are supporting segment growth.
- By Vehicle Type
On the basis of vehicle type, the global active spoiler market is segmented into passenger cars, sports & luxury cars, SUVs & crossovers, and light commercial vehicles. The passenger cars segment dominated the market with a share of 39.85% in 2025, supported by high absolute production volumes and the steady migration of active aerodynamic features from flagship models into mainstream premium sedans and hatchbacks.
The SUVs & crossovers segment is expected to witness the fastest CAGR of 8.6% from 2026 to 2033, driven by the aerodynamic disadvantage inherent to taller, higher-frontal-area body styles, which makes active drag management particularly valuable. As SUVs continue to gain share of global vehicle sales and electrified SUV platforms proliferate, demand for active spoilers and allied aerodynamic devices in this body style is rising sharply.
- By Propulsion
On the basis of propulsion, the global active spoiler market is segmented into internal combustion engine vehicles, battery electric vehicles, hybrid & plug-in hybrid vehicles, and fuel cell electric vehicles. The internal combustion engine vehicles segment dominated the market with a share of 55.12% in 2025, reflecting the continued dominance of combustion platforms in the global vehicle parc and the long-standing use of active spoilers on high-performance petrol models.
The battery electric vehicles segment is expected to witness the fastest CAGR of 10.2% from 2026 to 2033, driven by the direct relationship between aerodynamic drag and driving range. As manufacturers compete on real-world range rather than battery capacity alone, active aerodynamic content per electric vehicle is increasing, making this the most dynamic propulsion segment in the market.
- By Control Technology
On the basis of control technology, the global active spoiler market is segmented into speed-based control, sensor fusion & ADAS-integrated control, driver-selectable mode control, and AI & predictive control. The speed-based control segment dominated the market with a share of 47.96% in 2025 due to its simplicity, reliability, and low calibration burden, with deployment thresholds tied directly to vehicle speed remaining the most widely implemented strategy across production vehicles.
The AI & predictive control segment is expected to witness the fastest CAGR of 9.4% from 2026 to 2033, driven by the integration of active aerodynamics with navigation data, road gradient information, ADAS sensor inputs, and driver behaviour models. Predictive actuation allows the system to anticipate braking, cornering, and high-speed cruising rather than react to them, improving both efficiency and stability outcomes.
- By Component
On the basis of component, the global active spoiler market is segmented into spoiler blade & body, actuators & motors, electronic control units, sensors, and linkages, hinges & mounting hardware. The spoiler blade & body segment dominated the market with a share of 36.44% in 2025, accounting for the largest share of material content, tooling investment, and finishing cost within the assembly, and remaining the component most closely tied to vehicle styling and brand identity.
The actuators & motors segment is expected to witness the fastest CAGR of 8.2% from 2026 to 2033, driven by rising system sophistication, the shift toward multi-position and continuously variable deployment, and the growing number of independently actuated aerodynamic surfaces per vehicle. Supplier investment in compact, high-torque, automotive-grade actuation modules is further supporting segment growth.
- By Functionality
On the basis of functionality, the global active spoiler market is segmented into downforce generation & stability, drag reduction & efficiency, air brake assistance, and thermal & battery cooling support. The downforce generation & stability segment dominated the market with a share of 38.71% in 2025, reflecting the original and still-primary purpose of active spoilers in improving grip, high-speed handling, and braking balance on performance vehicles.
The drag reduction & efficiency segment is expected to witness the fastest CAGR of 8.8% from 2026 to 2033, driven by regulatory pressure on fleet emissions and the range imperative in electric vehicles. This functional shift is broadening the addressable market beyond performance models into efficiency-focused mainstream and electrified vehicles.
- By Application
On the basis of application, the global active spoiler market is segmented into performance enhancement, fuel & energy efficiency, vehicle stability & safety, and styling & aesthetics. The performance enhancement segment dominated the market with a share of 41.02% in 2025, supported by sustained demand for sports cars, performance variants of mainstream models, and track-capable derivatives where aerodynamic tuning is a core product attribute.
The fuel & energy efficiency segment is expected to witness the fastest CAGR of 9.0% from 2026 to 2033, driven by fleet-wide CO2 compliance requirements and the commercial importance of certified and real-world range figures in the electric vehicle market. This shift is repositioning active spoilers as a regulatory and efficiency technology rather than a discretionary performance option.
- By Sales Channel
On the basis of sales channel, the global active spoiler market is segmented into OEM and aftermarket. The OEM segment dominated the market with a share of 78.63% in 2025 due to the deep integration required between active aerodynamic hardware, vehicle electronic architecture, crash and pedestrian safety validation, and homologation processes, all of which make factory fitment the dominant route to market.
The aftermarket segment is expected to witness the fastest CAGR of 7.9% from 2026 to 2033, driven by growing enthusiast demand for retrofittable active spoiler kits, expanding availability of universal-fit electronically actuated systems, and strong vehicle personalization cultures in North America and Asia-Pacific. Regulatory and warranty considerations, however, continue to moderate the pace of aftermarket expansion.
Which Region Holds the Largest Share of the Active Spoiler Market?
- Europe dominated the active spoiler market and accounted for the largest revenue share of 34.62% in 2025, supported by the concentration of premium, luxury, and performance vehicle manufacturers in Germany, Italy, and the United Kingdom, and by a deep Tier-1 supply base specializing in active aerodynamic systems.
- The region also benefits from among the world’s most stringent CO2 and fleet efficiency regulations, which make aerodynamic optimization a compliance priority rather than a styling choice. Sustained investment in electric vehicle platforms, a strong motorsport engineering ecosystem, and early adoption of multi-element active aerodynamic strategies continue to reinforce Europe’s leadership in the global market.
Germany Active Spoiler Market Insight
The Germany active spoiler market holds a leading position within Europe, underpinned by the country’s premium automotive manufacturing base and its concentration of specialist aerodynamic and actuation suppliers. German manufacturers were among the earliest to deploy multi-position rear wings, active rear spoilers, and coordinated front-and-rear aerodynamic systems on series production vehicles. Ongoing investment in electric performance platforms, together with advanced research into alternative actuation concepts such as inflatable and compressor-driven aerodynamic surfaces, continues to position Germany as the principal innovation hub for active spoiler technology.
U.K. Active Spoiler Market Insight
The U.K. active spoiler market is growing steadily, supported by the country’s specialist sports car and low-volume performance vehicle manufacturers and its motorsport engineering cluster. Aerodynamic expertise developed in racing environments transfers directly into road car programmes, resulting in sophisticated active wing and air brake systems on domestically produced performance vehicles. Growing collaboration between motorsport engineering firms, composite specialists, and vehicle manufacturers is further strengthening the country’s position in high-value active aerodynamic development.
Asia-Pacific Active Spoiler Market Insight
The Asia-Pacific active spoiler market is expected to witness the fastest growth globally, driven by large-scale electric vehicle production, expanding premium vehicle demand, and the rapid localization of aerodynamic component manufacturing. Chinese, Japanese, and South Korean manufacturers are increasingly specifying active aerodynamic content to improve certified range and differentiate electric models in highly competitive domestic markets. Rising disposable income, growing enthusiasm for performance and personalization, and substantial investment in component tooling and actuator production are accelerating regional market expansion.
China Active Spoiler Market Insight
The China active spoiler market is expanding rapidly, supported by the world’s largest electric vehicle production base and intense competition on range and technology content among domestic manufacturers. Active aerodynamic features are increasingly used as a visible differentiator in mid-premium and premium electric models, while local suppliers are scaling capacity in actuators, control modules, and moulded aerodynamic surfaces. Growing cooperation between Chinese automakers and established European aerodynamic specialists for both domestic and export programmes is further accelerating market development.
Japan Active Spoiler Market Insight
The Japan active spoiler market is growing consistently, driven by the country’s established performance vehicle heritage, advanced component engineering capability, and strong supplier presence in actuators, control electronics, and exterior modules. Japanese manufacturers apply active aerodynamic systems across both performance derivatives and efficiency-focused hybrid and electric models. Continued emphasis on precision engineering, component durability, and lightweight materials is supporting steady adoption across the domestic vehicle portfolio.
Which are the Top Companies in Active Spoiler Market?
The active spoiler industry is primarily led by well-established companies, including:
- Magna International Inc. (Canada)
- OPmobility SE (France)
- Röchling Automotive SE & Co. KG (Germany)
- SMP Deutschland GmbH (Germany)
- Samvardhana Motherson International Limited (India)
- POLYTEC Holding AG (Austria)
- REHAU Automotive SE & Co. KG (Germany)
- SRG Global Inc. (U.S.)
- AP Plasman Inc. (Canada)
- Valeo SA (France)
- Continental AG (Germany)
- Robert Bosch GmbH (Germany)
- DENSO Corporation (Japan)
- Aisin Corporation (Japan)
- Toyoda Gosei Co., Ltd. (Japan)
- INOAC Corporation (Japan)
- Hyundai Mobis Co., Ltd. (South Korea)
- Seoyon E-Hwa Co., Ltd. (South Korea)
- HBPO GmbH (Germany)
- Brose Fahrzeugteile SE & Co. KG (Germany)
- Stabilus SE (Germany)
- Küster Holding GmbH (Germany)
- Mubea Carbo Tech GmbH (Austria)
- Multimatic Inc. (Canada)
- Gestamp Automoción, S.A. (Spain)
- Flex-N-Gate Corporation (U.S.)
- Johnson Electric Holdings Limited (Hong Kong)
- Thai Rung Union Car Public Company Limited (Thailand)
- Albar Industries, Inc. (U.S.)
- DAR Spoilers (U.S.)
- SEIBON Carbon (U.S.)
- Changzhou Huawei Plastic Co., Ltd. (China)
- Jiangnan Mould & Plastic Technology Co., Ltd. (China)
What are Latest Developments in Active Spoiler Market?
- In July 2026, Röchling Automotive announced that it had been nominated by Leapmotor International to supply active aerodynamics, exterior, and airflow management components for the automaker's future vehicle programmes in Europe. Production will take place at Röchling Automotive's plant in Araia, Spain, extending a technical partnership between the two companies dating back to 2019. The nomination reinforces the supplier's position in active aerodynamic systems and reflects the broader localization of Chinese electric vehicle production within Europe.
- In February 2026, General Motors was reported to have filed a patent covering active downforce control for drifting manoeuvres, describing a controller that reads steering angle and pedal position from vehicle sensors and adjusts front splitter and rear spoiler positions to reduce downforce during a controlled slide, operating independently of the stability control system. The filing indicates active aerodynamic control moving beyond speed-based actuation into driver-intent and behaviour-linked strategies.
- In October 2024, Ferrari revealed the F80, applying an active rear wing that is fully integrated into the bodywork when retracted and generates 590 kg of downforce at 250 km/h when deployed, alongside a front triplane wing, S-Duct, and flat underbody. The system represents the current benchmark for multi-element coordinated active aerodynamics in a series-production road car.
- In August 2024, BMW was reported to have filed a patent for an inflatable ducktail-style rear spoiler capable of near-infinitely variable deflection angles using pressurized air rather than electric or hydraulic actuation. The concept targets the weight, packaging, and supporting hardware penalties associated with conventional motor-driven active aerodynamic systems, and could be triggered by acceleration, speed, steering angle, suspension settings, or road gradient.
- In January 2024, Porsche launched the all-electric Macan with its PAA active aerodynamics package, comprising an adaptive rear spoiler, fully variable active cooling flaps that open to cool the battery during charging and close on the move to reduce drag, and flexible underbody covers, yielding a 0.25 drag coefficient. The deployment illustrates the shift in the commercial rationale for active aerodynamics from performance differentiation toward quantifiable range benefit.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.