What is the AI Accelerator Chips Market Size and Growth Rate?
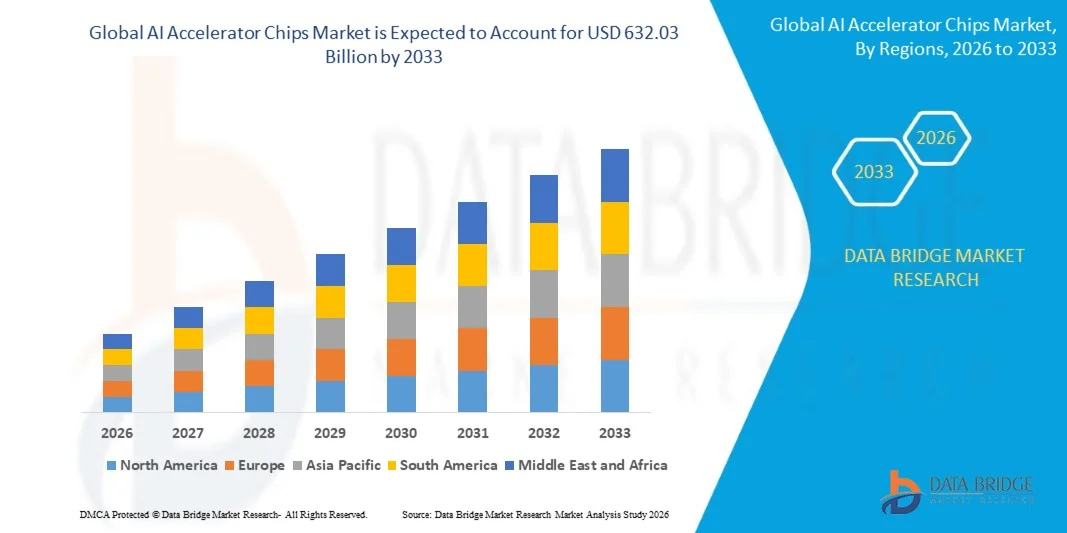
- As per market analysis, the global AI Accelerator Chips Market was valued at USD 119.5 billion in 2025 and is projected to reach USD 632.03 billion by 2033, growing at a CAGR of 23.40% from 2026 to 2033.
- The market is witnessing growth driven by the increasing deployment of artificial intelligence (ai), machine learning, generative ai, and high-performance computing applications, which require specialized chips capable of processing large volumes of data efficiently. Growing investments in ai infrastructure, expansion of hyperscale data centers, and rising demand for faster and more energy-efficient computing are supporting the adoption of ai accelerator chips across data centers, cloud computing, enterprise computing, and consumer electronics.
- Increasing adoption of generative ai, large language models, edge ai, autonomous systems, and ai-enabled applications is creating further growth opportunities. The expansion of ai workloads across cloud and on-premises environments, rising demand for GPU-, TPU-, NPU-, and asic-based acceleration, and continuous advancements in semiconductor manufacturing and chip architecture are supporting market development across data centers, automotive, healthcare, telecommunications, consumer electronics, and enterprise applications.
Market Size & Forecast
- Market Value (2025): USD 119.5 billion
- Expected Market Value (2033): USD 632.03 Million
- Forecast CAGR (2026–2033): 23.40%
- Leading Region in 2025: Asia-Pacific
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the AI Accelerator Chips Market?
- Asia-pacific accounted for 22.80% of the global ai accelerator market in 2025, supported by expanding ai infrastructure, increasing investments in data centers, growing adoption of cloud computing, and the presence of major semiconductor manufacturing and technology ecosystems across China, Japan, South Korea, And Taiwan. The region is also benefiting from increasing deployment of ai workloads across enterprise, automotive, telecommunications, and consumer applications.
- Asia-pacific is expected to witness strong growth in the global ai accelerator market during the forecast period, with a CAGR of 32.55%, supported by rising ai workloads, expanding hyperscale and cloud data centers, increasing generative ai adoption, and growing investments in high-performance computing infrastructure. The region's established semiconductor ecosystem and increasing deployment of ai technologies are further supporting market development.
- Graphics processing units (GPUs) represented the leading ai accelerator type segment with market share of 77.43% in 2025, supported by their high parallel-processing capabilities, established software ecosystem, and widespread use in ai model training, inference, generative ai, and high-performance computing. In the Asia-pacific ai accelerator market, GPUS accounted for, demonstrating their strong position within the accelerator-type segment.
- Cloud-based ai accelerators represented a major technology-integration segment of the ai accelerator market 59.26% of revenue in 2025, supported by the rapid expansion of cloud infrastructure, increasing adoption of ai-as-a-service, and growing demand for scalable computing resources. Cloud deployment enables enterprises and ai developers to access accelerator infrastructure without making equivalent investments in on-premise hardware.
- It and telecommunications represented a leading end-use segment of the ai accelerator market with share of 55.11% in 2025, supported by increasing ai workloads, cloud computing adoption, data-center expansion, and the deployment of generative ai and machine-learning applications. Ai accelerator demand is increasing as enterprises and telecommunications providers require high-performance computing for ai training, inference, data analytics, and real-time processing.
Report Scope AI Accelerator Chips Market Segmentation
|
Attributes |
AI Accelerator Chips Market Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, geographically represented company-wise production and capacity, network layouts of distributors and partners, detailed and updated price trend analysis and deficit analysis of supply chain and demand. |
What is the Key Trend in the AI Accelerator Chips Market?
- Increasing development of customized AI accelerator chips for inference and workload-specific computing is emerging as a key trend in the market. Hyperscalers and technology companies are increasingly developing proprietary GPUS, TPUS, ASICS, and other specialized accelerators to improve ai performance, reduce power consumption, optimize computing costs, and address specific training and inference requirements. This trend is particularly relevant to data centers supporting generative ai, large language models, ai agents, and other compute-intensive workloads.
- For instance, on April 9, 2025, google introduced ironwood, its seventh-generation tensor processing unit (TPU), at google cloud next 2025. Google described ironwood as its first TPU specifically designed for inference at scale. The architecture can scale to 9,216 liquid-cooled chips in a single superpod and provides 192 GB of HBM per chip, with HBM bandwidth reaching 7.37 tb/s per chip. Google positioned ironwood for demanding generative ai, reasoning, and inference workloads.
- The increasing focus on inference is further accelerating demand for specialized ai accelerators. As generative ai applications move from model training toward large-scale deployment, accelerator requirements are increasingly influenced by latency, energy efficiency, memory bandwidth, and cost per inference.
- The trend toward workload-specific accelerator architectures is also expanding into agentic ai and differentiated training and inference workloads.
What are the Key Drivers of the AI Accelerator Chips Market?
- Increasing adoption of specialized ai accelerator chips for inference and workload-specific computing is emerging as a key driver in the market. Hyperscalers and technology companies are increasingly developing custom TPUS, ASICS, and other dedicated accelerators to improve ai performance, reduce latency, increase energy efficiency, and optimize computing costs for specific workloads.
- The growing deployment of generative ai, large language models, ai agents, and real-time inference applications is increasing demand for specialized acceleration beyond conventional general-purpose computing platforms.
- For instance, on April 9, 2025, google introduced ironwood, its seventh-generation tensor processing unit (TPU), at google cloud next 2025. Google described ironwood as its first TPU specifically designed for inference at scale. The system can scale to 9,216 liquid-cooled chips in a single configuration and was developed to support the computational and communication requirements of advanced generative ai and inference workloads.
- The increasing requirement for energy-efficient ai computing is further driving demand for advanced accelerator architectures. Ai workloads require substantial computational power, memory bandwidth, networking, and cooling infrastructure, particularly as models become larger and inference volumes increase.
- This is encouraging accelerator developers to optimize performance per watt and reduce data movement. Google's ironwood, for instance, was developed with a focus on performance and power efficiency, while Microsoft has also developed custom ai accelerators with integrated power management and liquid-cooling approaches for large-scale ai workloads.
Which Factors are Challenging the Growth of the AI Accelerator Chips Market?
- Supply constraints for AI accelerator chips and critical components are emerging as a key challenge in the market. The rapid expansion of generative AI, large language models, and AI data centers is increasing demand for GPUs, ASICs, and other accelerator chips faster than manufacturing capacity can expand.
- For instance, in April 2026, The Futurum Group reported that accelerator/GPU supply and power and cooling availability together represented the biggest constraints for 49% of surveyed organizations, with 26% citing accelerator/GPU supply and 23% citing power and cooling availability as their single biggest constraint.
- High-bandwidth memory (HBM) and advanced packaging constraints are further challenging AI accelerator chip production. Modern AI accelerators require high-performance HBM and advanced packaging technologies to achieve high memory bandwidth and integrate multiple components efficiently.
- High power consumption and cooling requirements are creating additional challenges for AI accelerator deployment. Increasing computational density requires substantial electricity and advanced thermal-management infrastructure, particularly in large AI data centers.
How is the AI Accelerator Chips Market Segmented?
The market is segmented on the basis of Chip Type, Processing Type, and Industry.
- By Chip Type
On the basis of chip type, the global AI Accelerator Chips Market is segmented into GPU, ASIC, FPGA, CPU, and other. The GPU segment is expected to dominate the market with market share of 43.12% in 2025, supported by its high parallel-processing capabilities, flexibility across ai workloads, mature software ecosystem, and extensive use in ai model training and inference. GPUS are widely deployed across data centers, cloud platforms, autonomous systems, and other ai-intensive applications. Current industry analysis also identifies GPUS as the leading accelerator category by revenue.
The Asic segment is expected to witness significant growth during the forecast period with cagr of 6.43% in 2026 to 2033, supported by increasing development of workload-specific ai accelerators by hyperscale cloud providers and technology companies. Asics can be optimized for particular ai workloads, enabling improvements in performance, power efficiency, and cost per operation.
- By Processing Type
On the basis of processing type, the global AI Accelerator Chips Market is segmented into edge and cloud. The cloud segment is expected to dominate the market with market share of 54.23% in 2025, supported by the increasing deployment of ai training and inference workloads across hyperscale data centers, cloud platforms, and enterprise computing infrastructure. Large-scale ai models require substantial computational resources, making cloud-based accelerator deployment particularly important for generative ai and machine learning workloads.
The edge segment is expected to witness strong growth during the forecast period of CAGR 5.34% in 2026 to 2033, driven by increasing demand for real-time ai processing, low latency, data privacy, and reduced dependence on centralized cloud infrastructure. Automotive systems, industrial automation, healthcare devices, robotics, smartphones, and other connected devices are supporting the adoption of edge ai accelerators.
- By Industry
On the basis of industry, the global AI Accelerator Chips Market is segmented into automotive, consumer electronics, healthcare, manufacturing, and others. The consumer electronics segment is expected to account for a significant share of 43.23% in 2025, supported by increasing integration of ai capabilities into smartphones, pcs, smart cameras, wearables, and other connected devices. Ai accelerators enable on-device functions such as image processing, voice recognition, personalization, security, and generative ai.
The automotive segment is expected to witness significant growth of 7.45% of 2026 to 2033, supported by increasing adoption of autonomous driving, advanced driver-assistance systems, intelligent cockpit systems, and in-vehicle ai processing. The manufacturing segment is also expanding as ai accelerators are increasingly deployed for machine vision, predictive maintenance, automated inspection, robotics, and real-time industrial decision-making. Healthcare applications are gaining traction through medical imaging, diagnostics, and ai-assisted clinical technologies.
Which Region Holds the Largest Share of the AI Accelerator Chips Market?
- Asia-pacific accounted for 22.80% of the global ai accelerator market in 2025, supported by expanding ai infrastructure, increasing investments in data centers, growing adoption of cloud computing, and the presence of major semiconductor manufacturing and technology ecosystems across China, Japan, South Korea, And Taiwan. The region is also benefiting from increasing deployment of ai workloads across enterprise, automotive, telecommunications, and consumer applications.
- Asia-pacific is expected to witness strong growth in the global ai accelerator market during the forecast period, with a CAGR of 32.55%, supported by rising ai workloads, expanding hyperscale and cloud data centers, increasing generative ai adoption, and growing investments in high-performance computing infrastructure. The region's established semiconductor ecosystem and increasing deployment of ai technologies are further supporting market development.
U.S. AI Accelerator Chips Market Insight
The U.S. AI Accelerator Chips Market is expanding as demand for high-performance computing increases across cloud computing, data centers, generative AI, machine learning, and enterprise applications. The country benefits from the presence of leading semiconductor and technology companies, including NVIDIA, AMD, Intel, Google, Amazon Web Services, and Microsoft, supporting innovation in GPUs, ASICs, and specialized AI processors. Growing investments in hyperscale data centers and AI infrastructure are further supporting market development. Increasing adoption of edge AI, autonomous systems, and AI-enabled software is also creating opportunities for advanced accelerator technologies across multiple industries.
Europe AI Accelerator Chips Market Insight
Europe’s AI Accelerator Chips Market is expanding as investments in artificial intelligence, cloud computing, high-performance computing, and data-center infrastructure increase across the region. Growing adoption of GPUs, ASICs, FPGAs, and specialized AI processors is supporting applications in automotive, healthcare, manufacturing, financial services, and telecommunications. European automotive manufacturers are increasingly integrating AI computing into advanced driver-assistance systems and autonomous mobility technologies, while industrial companies are deploying AI for automation, predictive maintenance, and machine vision. Government initiatives supporting semiconductor manufacturing, AI development, and digital infrastructure are further strengthening regional demand for AI accelerator chips.
U.K. AI Accelerator Chips Market Insight
The U.K. AI Accelerator Chips Market is expanding as demand for artificial intelligence, machine learning, cloud computing, and high-performance computing continues to increase across enterprises and data centers. Growing adoption of generative AI and large language models is supporting demand for GPUs, ASICs, and other specialized accelerator architectures. Investments in AI infrastructure, advanced computing facilities, and data-center capacity are further strengthening market opportunities. The automotive, healthcare, financial services, and manufacturing sectors are also adopting AI-enabled solutions, creating additional demand for efficient accelerator technologies that support high-speed processing and real-time AI workloads.
Germany AI Accelerator Chips Market Insight
Germany’s AI Accelerator Chips Market is expanding as investments in artificial intelligence, high-performance computing, industrial automation, and data-center infrastructure continue to increase. Growing adoption of AI across automotive manufacturing, healthcare, financial services, and industrial applications is supporting demand for GPUs, ASICs, FPGAs, and other specialized accelerator technologies. Germany’s strong automotive and industrial ecosystem is encouraging the deployment of AI for autonomous systems, predictive maintenance, machine vision, and smart manufacturing. Increasing cloud adoption and edge computing requirements are further supporting market development, while semiconductor supply-chain considerations and high infrastructure costs remain important market factors.
Asia-Pacific AI Accelerator Chips Market Insight
The Asia-Pacific AI Accelerator Chips Market is expanding as investments in artificial intelligence infrastructure, data centers, cloud computing, and advanced semiconductor manufacturing continue to increase across the region. China, Japan, South Korea, and Taiwan are strengthening regional capabilities through investments in AI processors, GPUs, ASICs, and semiconductor fabrication facilities. Growing adoption of generative AI, machine learning, edge computing, autonomous systems, and smart devices is further supporting demand for high-performance accelerator chips. Increasing AI workloads and the expansion of hyperscale data centers are creating additional opportunities for accelerator-chip manufacturers across the region.
Japan AI Accelerator Chips Market Insight
Japan’s AI Accelerator Chips Market is expanding as investments in artificial intelligence, high-performance computing, robotics, and data-center infrastructure continue to increase. The country’s established semiconductor ecosystem, advanced electronics industry, and strong presence of technology and automotive companies support demand for GPUs, ASICs, and other specialized AI accelerators. Growing adoption of AI across manufacturing, automotive, healthcare, and consumer electronics is creating additional opportunities for accelerator-chip deployment. Increasing edge AI applications are also supporting demand for low-latency and energy-efficient computing solutions. However, high semiconductor development costs, technological complexity, and competition from global chip manufacturers remain key market consideration.
China AI Accelerator Chips Market Insight
China’s AI Accelerator Chips Market is expanding as investments in artificial intelligence, data centers, cloud computing, and high-performance computing continue to increase. Growing adoption of generative AI, large language models, autonomous systems, and industrial AI is supporting demand for GPUs, ASICs, and other specialized accelerator architectures. Domestic semiconductor companies are also strengthening AI chip development and expanding local computing capabilities to support increasing workloads. Rising deployment of AI across automotive, consumer electronics, healthcare, and manufacturing is creating additional opportunities. However, semiconductor supply-chain constraints, advanced manufacturing requirements, and intense competition remain important market considerations.
Which are the Top Companies in AI Accelerator Chips Market?
The AI Accelerator Chips Market industry is primarily led by well-established companies, including:
- NVIDIA Corporation (U.S.)
- Advanced Micro Devices, Inc. (AMD) (U.S.)
- Intel Corporation (U.S.)
- Google LLC (U.S.)
- Amazon Web Services, Inc. (AWS) (U.S.)
- Microsoft Corporation (U.S.)
- Qualcomm Incorporated (U.S.)
- Broadcom Inc. (U.S.)
- Huawei Technologies Co., Ltd. (China)
- Cerebras Systems Inc. (U.S.)
- Groq, Inc. (U.S.)
- SambaNova Systems, Inc. (U.S.)
- Graphcore Limited (U.K.)
- Tenstorrent Inc. (Canada)
- Samsung Electronics Co., Ltd. (South Korea)
What are Latest Developments in AI Accelerator Chips Market?
- In March 2026, NVIDIA introduced the Vera Rubin AI platform, bringing together the Rubin GPU, Vera CPU, Groq 3 LPX inference accelerator, BlueField-4 DPU, and networking technologies. The platform is designed to support AI workloads ranging from model training to real-time agentic inference, reflecting the industry's shift toward rack-scale AI computing.
- In April 2026, Google introduced its eighth-generation TPU portfolio, comprising TPU 8t for high-throughput training and TPU 8i for inference and reinforcement-learning workloads. Google stated that TPU 8t can support systems containing up to 9,600 chips, while TPU 8i is designed for low-latency inference and improved performance per dollar.
- In June 2026, OpenAI and Broadcom unveiled the Jalapeño AI accelerator, an LLM-focused inference chip developed as part of a multi-generation compute platform. The companies stated that the accelerator is intended for deployment at gigawatt scale with data-center partners, with initial deployment targeted for the end of 2026.
- In September 2026, TrendForce reported that advanced packaging is becoming an increasingly important development area for AI accelerator chips. TSMC's CoWoS-L is expected to remain a mainstream packaging solution through 2028, while NVIDIA and AMD are already adopting the technology for advanced AI accelerators. The report also highlighted growing development of Intel EMIB-T as an alternative packaging technology.
- In August 2026, AWS and NVIDIA announced plans to deploy an additional 2 million NVIDIA GPUs during 2027–2028. The planned deployment includes NVIDIA Blackwell Ultra, Rubin, and Rubin Ultra GPUs across AWS infrastructure and is intended to support agentic AI, scientific computing, enterprise automation, and physical AI workloads.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Ai Accelerator Chips Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Ai Accelerator Chips Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Ai Accelerator Chips Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.