


What is the Automatic Power Factor Controller Market Size and Growth Rate?
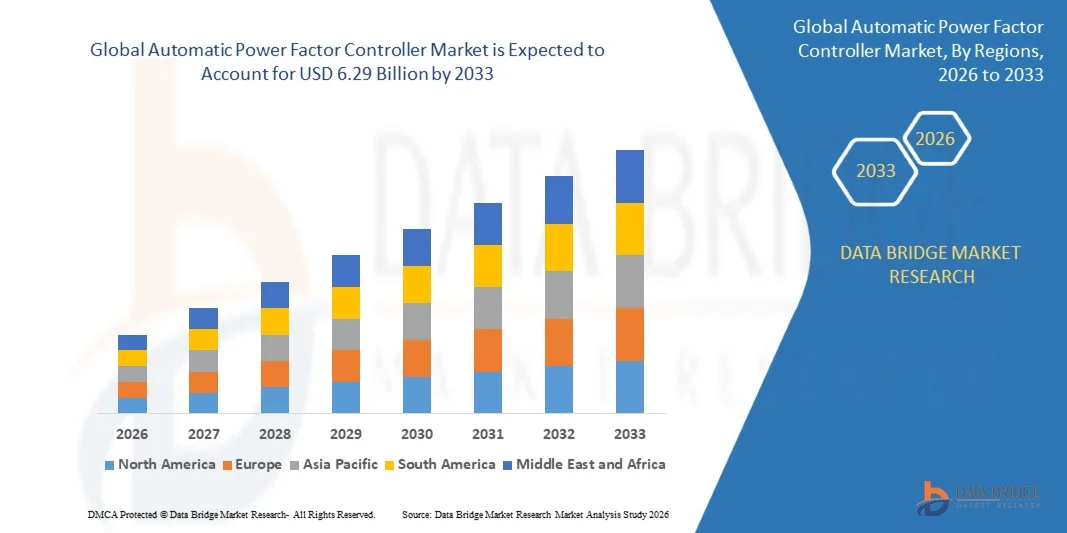
- As per Data Bridge Market Research analysis, the Automatic Power Factor Controller Market is estimated at USD 4.39 billion in 2025 and is projected to reach USD 6.29 billion by 2033, growing at a CAGR of 4.60% from 2026 to 2033.
- The market is experiencing steady growth driven by rising global emphasis on industrial energy efficiency, growing utility penalties for poor power factor, and continued modernization of aging electrical infrastructure across both developed and emerging markets.
- Growing industrial and commercial investment in power quality management, combined with rising adoption of digital monitoring and IoT-enabled capacitor bank technology, is compelling leading automation vendors to continuously enhance their APFC product portfolios. Continued industrialization across Asia-Pacific is expected to further support long-term category demand.
Market Size & Forecast
- Global Market Value (2025): USD 4.39 Billion
- Expected Market Value (2033): USD 6.29 Billion
- Forecast CAGR (2026–2033): 4.60%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Automatic Power Factor Controller Market?
- North America dominated the Automatic Power Factor Controller Market with the largest revenue share of 43.20% in 2025, supported by extensive industrial and commercial electrical infrastructure and strong regulatory emphasis on energy efficiency.
- Asia-Pacific is expected to be the fastest-growing region with CAGR of 5.2% from 2026 to 2033, fueled by rapid industrialization, rising awareness of energy conservation, and growing need for power quality optimization across diverse manufacturing sectors in China and India.
- The active APFC segment led the type category with a 67.30% share in 2025, driven by its ability to achieve power factor precision as high as 0.99.
- The capacitors segment dominated the component category with a 35.20% revenue share in 2025, reflecting their fundamental role in reactive power compensation.
- The self-standing panels segment led the installation type category with a 59.30% share in 2025, reflecting widespread preference for larger-capacity industrial and commercial installations.
- The industrial segment dominated the end user category with a 45.20% share in 2025, driven by extensive use of large electric motors and heavy equipment requiring power factor correction.
- The microcontrollers segment is the fastest-growing component category with a CAGR of 5.0%, reflecting growing integration of digital monitoring and connectivity features into modern APFC systems.
Report Scope and Automatic Power Factor Controller Market Segmentation
|
Attributes |
Automatic Power Factor Controller Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Automatic Power Factor Controller Market?
- Leading automation vendors continue to integrate digital monitoring and connectivity features into capacitor bank and APFC panel designs, enabling predictive maintenance and remote diagnostics.
- Schneider Electric's EcoStruxure-ready smart low voltage capacitor bank solutions illustrate the broader industry shift toward connected power factor correction systems that reduce operating and capital costs while improving power system efficiency.
- Manufacturers continue to expand hybrid power factor correction offerings that combine conventional capacitor banks with active harmonic filtering technology.
- For instance, In November 2024, Schneider Electric's PowerLogic PFC catalog described its smart low-voltage capacitor banks as solutions for reactive energy management, improved power availability, lower electricity costs, and improved business performance. The range is positioned as part of the company's connected power-management portfolio.
- Schneider Electric's VarSet Hybrid system, which integrates conventional power factor correction with IGBT-based active harmonic filtering, reflects growing industry demand for ultra-rapid response and infinitely variable reactive power control in applications such as welding equipment and large motor starting.
- For instance, In January 2025, The European Commission stated that Member States were required to transpose new electricity-market rules into national law, with the reforms focused partly on making energy costs more predictable and improving energy-market efficiency. Such policy developments reinforce the broader focus on electricity efficiency and cost management among commercial and industrial users.
- Regulatory and utility-driven energy efficiency standards continue to shape adoption patterns for power factor correction technology across major markets.
- Industry analysis published in 2025 confirmed that global emphasis on energy conservation, alongside standards such as the EU's ErP directive and U.S. ENERGY STAR program, continues to be a key driver supporting sustained demand for automatic power factor controllers across industrial and commercial applications.
As leading vendors continue to integrate digital monitoring, hybrid harmonic filtering, and connectivity features into their APFC product lines, the Automatic Power Factor Controller Market is expected to sustain steady growth across both mature and emerging industrial markets.
What are the Key Drivers of the Automatic Power Factor Controller Market?
- Rising global emphasis on industrial energy efficiency and growing utility penalties for poor power factor continue to drive adoption of automatic power factor correction systems across industrial and commercial facilities.
- Industry analysis has confirmed that upgrading industrial facilities to improve energy efficiency remains a key driver fueling automatic power factor controller market growth, as inductive loads from large electric motors and heavy equipment continue to create power factor challenges requiring correction.
- Continued modernization of aging electrical infrastructure across developed markets continues to support replacement and upgrade demand for power factor correction technology.
- Rapid industrialization and expanding manufacturing capacity across emerging markets, particularly in Asia-Pacific, continues to create substantial incremental demand for power quality management systems.
- Growing regulatory emphasis on energy conservation, including standards such as the EU's ErP directive and the U.S. ENERGY STAR program, continues to reinforce adoption of automatic power factor controllers across both industrial and commercial applications.
With global energy efficiency standards continuing to tighten and industrial electrification continuing to expand, particularly across Asia-Pacific, the Automatic Power Factor Controller Market is expected to remain a foundational category within the broader power quality management and industrial automation landscape.
Which Factors are Challenging the Growth of the Automatic Power Factor Controller Market?
- The automatic power factor controller market remains a relatively mature and moderately fragmented category, with numerous regional manufacturers competing on price, limiting pricing power for larger global vendors.
- Fluctuating raw material costs for capacitor-grade components and semiconductor elements used in active APFC systems continue to create cost pressure for manufacturers.
- Limited awareness of power factor correction benefits among smaller commercial and residential-adjacent end users in certain emerging markets continues to constrain broader category adoption outside core industrial applications.
- For instance, In April 2025, Research published in IEEE Access demonstrated the development of unified power-quality solutions combining power-factor correction with harmonic filtering and other power-quality functions. Such technologies address multiple electrical-quality requirements within a single system, increasing competitive pressure on standalone power-factor correction solutions
- Competition from integrated power quality management platforms that bundle power factor correction with broader energy management and harmonic filtering functionality continues to pressure standalone APFC product offerings.
- The combination of raw material cost volatility, limited end-user awareness in certain segments, and competition from integrated power quality platforms continues to create headwinds for the automatic power factor controller market, even as sustained industrial electrification and energy efficiency regulation support long-term category demand.
How is the Automatic Power Factor Controller Market Segmented?
The Automatic Power Factor Controller Market is segmented on the basis of type, component, installation type, voltage rating, connection type, end user, and sales channel.
- By Type
On the basis of type, the Automatic Power Factor Controller Market is segmented into active APFC and passive APFC. The active APFC segment dominated the market with a 67.30% share in 2025, driven by its use of active components such as diodes and transistors that enable engineers to achieve power factor precision as high as 0.99, making it the preferred choice across commercial, manufacturing, and utility applications.
The passive APFC segment is projected to register a comparatively modest CAGR from 2026 to 2033, supported by continued use in simpler, cost-sensitive applications where precise power factor correction is less critical.
- By Component
On the basis of component, the Automatic Power Factor Controller Market is segmented into capacitors, relays, microcontrollers, displays, switches, and resistors. The capacitors segment dominated the market with a 35.20% share in 2025, reflecting their fundamental role in reactive power compensation across all APFC system configurations.
The microcontrollers segment is expected to witness the fastest CAGR of 5.0% from 2026 to 2033, driven by growing integration of digital monitoring, precision switching logic, and connectivity features into modern APFC systems.
- By Installation Type
On the basis of installation type, the Automatic Power Factor Controller Market is segmented into self-standing panels, wall-mounted, and rack-mounted. The self-standing panels segment dominated the market with a 59.30% share in 2025, reflecting their widespread preference for industrial and commercial installations requiring larger-capacity reactive power compensation.
The rack-mounted segment is anticipated to witness the fastest CAGR of 4.9% from 2026 to 2033, driven by rising demand for space-efficient installation formats in modernized commercial and data center facilities.
- By Voltage Rating
On the basis of voltage rating, the Automatic Power Factor Controller Market is segmented into low voltage, medium voltage, and high voltage. The low voltage segment dominated the market with the largest share in 2025, reflecting its widespread use across commercial buildings and light industrial facilities.
The medium voltage segment is expected to witness the fastest CAGR of 5.1% from 2026 to 2033, driven by rising demand for power quality management in larger industrial and utility-scale installations.
- By Connection Type
On the basis of connection type, the Automatic Power Factor Controller Market is segmented into three-phase and single-phase. The three-phase segment dominated the market with the largest share in 2025, reflecting its widespread use across industrial and commercial electrical systems, which predominantly operate on three-phase power.
The single-phase segment is projected to witness the fastest CAGR of 5.0% from 2026 to 2033, supported by rising adoption of power factor correction in smaller commercial and residential-adjacent applications.
- By End User
On the basis of end user, the Automatic Power Factor Controller Market is segmented into industrial, commercial, utility, and residential. The industrial segment dominated the market with a 45.20% share in 2025, driven by extensive use of large electric motors and heavy equipment that create power factor challenges requiring correction to avoid utility penalties.
The commercial segment is expected to witness the fastest CAGR of 4.8% from 2026 to 2033, driven by rising energy efficiency retrofit investment across commercial buildings and data centers.
- By Sales Channel
On the basis of sales channel, the Automatic Power Factor Controller Market is segmented into direct/OEM and distributors & system integrators. The distributors & system integrators segment dominated the market with the largest share in 2025, reflecting the important role of regional partners in APFC panel installation, configuration, and after-sales support.
The direct/OEM segment is projected to grow fastest with a CAGR of 4.7% from 2026 to 2033, supported by continued large-account relationships between leading automation vendors and enterprise-level industrial customers.
Which Region Holds the Largest Share of the Automatic Power Factor Controller Market?
- North America dominated the Automatic Power Factor Controller Market and accounted for the largest revenue share of 43.20% in 2025, supported by extensive industrial and commercial electrical infrastructure, strong regulatory emphasis on energy efficiency, and high adoption of advanced power quality management technology.
- The region also benefits from a mature industrial base, established utility power factor penalty structures that incentivize correction technology adoption, and strong presence of leading automation vendors. Continued modernization of aging electrical infrastructure is expected to further reinforce North America's leadership position in the global market.
U.S. Automatic Power Factor Controller Market Insight
The U.S. automatic power factor controller market remains anchored by extensive industrial and commercial electrical infrastructure, strong regulatory emphasis on energy efficiency under programs such as ENERGY STAR, and the strong domestic presence of leading vendors including Schneider Electric, Eaton, and General Electric. Continued modernization of aging electrical grid infrastructure supports ongoing replacement and upgrade demand in the country.
Germany Automatic Power Factor Controller Market Insight
The Germany automatic power factor controller market benefits from the country's strong industrial manufacturing base and strict energy efficiency standards under the EU's ErP directive. Continued investment in power quality management technology by established vendors including Siemens supports ongoing category growth in the country.
Asia-Pacific Automatic Power Factor Controller Market Insight
The Asia-Pacific automatic power factor controller market is expected to witness the fastest growth CAGR of 5.2% globally, driven by rapid industrialization, rising awareness of energy conservation, and growing need for power quality optimization across diverse manufacturing sectors in China and India.
India Automatic Power Factor Controller Market Insight
The India automatic power factor controller market continues to benefit from expanding industrial capacity and regulatory frameworks that penalize poor power factor in commercial and industrial electricity consumption. Growing domestic manufacturing presence, led by companies such as Crompton Greaves and Larsen & Toubro, continues to support category growth in the country.
Which are the Top Companies in the Automatic Power Factor Controller Market?
The global automatic power factor controller industry is primarily led by well-established industrial automation and electrical equipment companies, including:
- Schneider Electric SE (France)
- Siemens AG (Germany)
- ABB Ltd (Switzerland)
- Eaton Corporation plc (Ireland)
- General Electric Company (U.S.)
- Rockwell Automation, Inc. (U.S.)
- Emerson Electric Co. (U.S.)
- Mitsubishi Electric Corporation (Japan)
- Crompton Greaves Consumer Electricals Ltd. (India)
- Larsen & Toubro Limited (India)
- STMicroelectronics N.V. (Switzerland)
- AVEVA Group plc (U.K.)
- Fujitsu Limited (Japan)
- Havells India Ltd. (India)
- L&T Electrical & Automation (India)
- Legrand SA (France)
- WEG S.A. (Brazil)
- Epcos AG (TDK) (Germany)
- Vishay Intertechnology, Inc. (U.S.)
- Frako Kondensatoren- und Anlagenbau GmbH (Germany)
What are the Latest Developments in the Automatic Power Factor Controller Market?
- During 2025, Schneider Electric continued to expand its EcoStruxure-ready smart low voltage capacitor bank portfolio, integrating digital monitoring and connectivity features to support predictive maintenance and remote power quality diagnostics.
- During 2024 and 2025, leading vendors including Siemens, ABB, and Eaton continued to invest in hybrid power factor correction technology combining conventional capacitor banks with active harmonic filtering to address power quality challenges from modern non-linear industrial loads.
- During 2025, industry analysis confirmed that active APFC systems continued to hold a dominant 67.30% share of the type segment, reflecting sustained industrial and commercial preference for precision reactive power compensation.
- During 2025, North America continued to represent the largest regional market for automatic power factor controllers, supported by strong regulatory emphasis on energy efficiency and continued modernization of aging electrical infrastructure.
- During 2025, Asia-Pacific manufacturers, including regional players in India and China, continued to expand domestic production capacity for power factor correction equipment in response to rapid industrialization and rising energy conservation awareness.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.













