What is the Automotive Aerodynamic Market Size and Growth Rate?
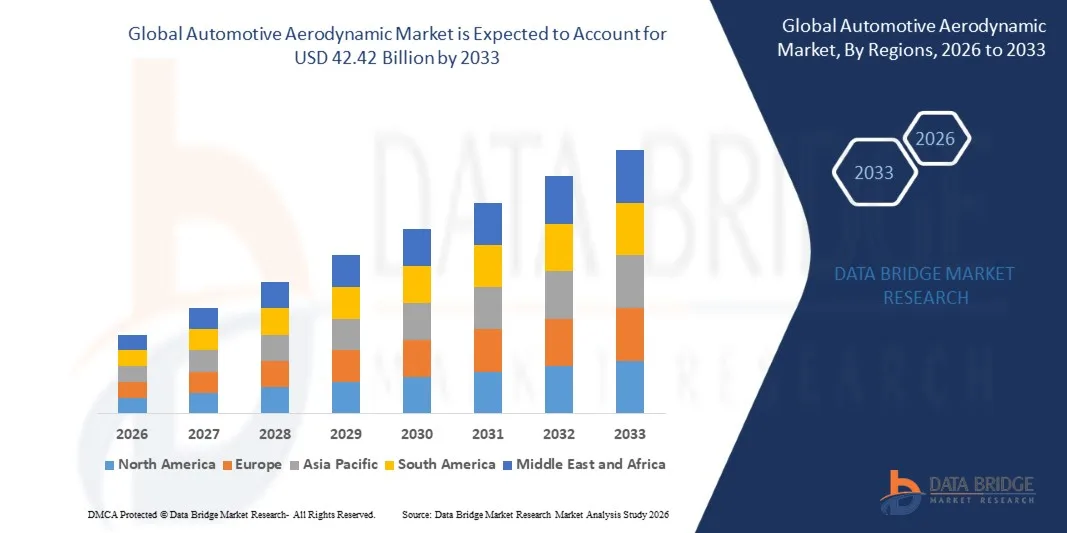
- As per Data Bridge Market Research analysis, the automotive aerodynamic market was valued at USD 29.95 billion in 2025 and is projected to reach USD 42.42 billion by 2033, growing at a CAGR of 4.45% from 2026 to 2033.
- The market is experiencing consistent growth driven by rising demand for fuel-efficient vehicles, increasing electric vehicle adoption, advancements in aerodynamic design technologies, and growing emphasis on vehicle performance and stability.
- The increasing focus on reducing carbon emissions globally, combined with stricter fuel-efficiency regulations and growing demand for extended electric vehicle driving ranges, is compelling automotive manufacturers to adopt advanced aerodynamic solutions. Active and passive aerodynamic systems, including spoilers, diffusers, grille shutters, and air dams, are increasingly integrated into vehicle designs to reduce air resistance, improve energy efficiency, enhance driving stability, and optimize overall vehicle performance.
Market Size & Forecast
- Global Market Value (2025): USD 29.95 Billion
- Expected Market Value (2033): USD 42.42 Billion
- Forecast CAGR (2026–2033): 4.45%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Automotive Aerodynamic Market?
- North America dominated the automotive aerodynamic market with the largest revenue share of 31% in 2025, supported by established automotive manufacturers, strong R&D investments, stringent fuel-efficiency standards, and increasing adoption of advanced aerodynamic technologies.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 5.44% from 2026 to 2033, fueled by expanding automotive production, rising electric vehicle adoption, and increasing demand for energy-efficient vehicle designs.
- The battery electric vehicle segment led the market with a 60% share in 2025, driven by increasing electric vehicle adoption and the importance of aerodynamic efficiency in extending driving range.
- Hybrid electric vehicle are the fastest-growing electric vehicle type, projected to register a CAGR of 8.0%, reflecting the surge in demand for fuel-efficient vehicles that combine internal combustion engines with electric propulsion.
- The passive system segment dominated the mechanism category with a 61.4% revenue share in 2025, led by its cost-effectiveness, simple design, low maintenance requirements, and widespread use of fixed aerodynamic components
- Light-duty vehicles accounted for 81% of the market share in 2025, preferred by high production volumes of passenger cars, sport utility vehicles, and light commercial vehicles.
- The grille shutter segment is the fastest-growing application category, with a CAGR of 6.9%, driven by increasing adoption of intelligent airflow management and improved vehicle efficiency.
Report Scope and Automotive Aerodynamic Market Segmentation
|
Attributes |
Automotive Aerodynamic Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Automotive Aerodynamic Market?
- Automotive manufacturers are increasingly adopting active aerodynamic technologies to improve vehicle efficiency, reduce air resistance, and enhance driving stability across passenger cars, SUVs, and electric vehicles.
- For instance, in January 2024, Hyundai Motor Company and Kia Corporation unveiled Active Air Skirt technology, designed to control airflow around vehicle wheels and reduce aerodynamic resistance. Testing on the Genesis GV60 showed a 2.8% improvement in drag performance, highlighting the growing role of active aerodynamic systems in electric vehicles.
- Active grille shutters, underbody panels, air curtains, and adaptive spoilers are becoming important design elements for controlling airflow and reducing aerodynamic drag.
- Electric vehicle manufacturers are increasingly integrating smooth underbodies, flush door handles, and optimized wheel designs to minimize turbulence and improve driving range without compromising vehicle performance.
- For instance, in September 2024, Audi introduced the A6 Sportback e-tron, achieving a drag coefficient of 0.21 through features including optimized air intakes, aerodynamic wheel designs, and underbody refinements.
- As automakers prioritize energy efficiency, electric driving range, and lower emissions, advanced aerodynamic engineering is expected to remain a central component of vehicle design and performance optimization.
What are the Key Drivers of the Automotive Aerodynamic Market?
- The growing adoption of electric vehicles and stricter vehicle-efficiency requirements has increased demand for advanced aerodynamic technologies that reduce drag, improve energy efficiency, and extend driving range.
- For instance, in January 2024, Hyundai Motor Company and Kia Corporation unveiled Active Air Skirt technology to control airflow around vehicle wheels at high speeds. Testing on the Genesis GV60 demonstrated a 2.8% reduction in aerodynamic drag, with the potential to add approximately 6 km of driving range.
- Automotive OEMs are increasingly integrating active grille shutters, adaptive spoilers, underbody covers, and air curtains to optimize airflow, improve thermal management, and balance aerodynamic efficiency with vehicle performance.
- For instance, in January 2024, Porsche unveiled its all-electric Macan with Porsche Active Aerodynamics, including an adaptive rear spoiler, active cooling flaps, and a sealed underbody, achieving a drag coefficient of 0.25 to support energy efficiency and driving range.
- As automakers increasingly prioritize lower energy consumption, improved driving range, and compliance with emissions requirements, aerodynamic technologies will remain essential to vehicle development and performance optimization.
What Factors are Challenging the Growth of the Automotive Aerodynamic Market?
- Advanced aerodynamic systems require significant investment in computational fluid dynamics (CFD), wind-tunnel testing, prototype development, and specialized engineering expertise.
- For instance, in July 2023, Ford highlighted its advanced rolling-road wind tunnel, capable of simulating road conditions at speeds of up to 200 mph, illustrating the specialized infrastructure required for accurate aerodynamic development.
- These high development costs can limit adoption among smaller automotive manufacturers and suppliers, particularly when advanced aerodynamic components require extensive testing and vehicle-specific integration.
- The high capital investment and recurring validation costs associated with aerodynamic development continue to challenge manufacturers, particularly those operating with limited R&D budgets.
- For instance, in January 2026, research article published in the Journal of the Visualization Society of Japan discussed the complementary use of CFD and wind-tunnel testing in automotive aerodynamic development, highlighting the need for both computational resources and physical testing to assess aerodynamic performance accurately
- These financial and technical barriers can slow the adoption of advanced aerodynamic systems across cost-sensitive vehicle segments, despite increasing demand for fuel-efficient and electric vehicles.
How is the Automotive Aerodynamic Market Segmented?
The automotive aerodynamic market is segmented on the basis of electric vehicle type, mechanism, vehicle type, and application.
- By Electric Vehicle Type
On the basis of electric vehicle type, the automotive aerodynamic market is segmented into battery electric vehicles (BEVs) and hybrid electric vehicles (HEVs). The battery electric vehicle (BEV) segment is expected to dominate the market with an estimated share of 60% in 2025, driven by increasing electric vehicle adoption and the importance of aerodynamic efficiency in extending driving range. Aerodynamic drag directly affects battery energy consumption, particularly at highway speeds. Manufacturers are incorporating streamlined body designs, smooth underbody panels, air curtains, and optimized wheel configurations to minimize resistance. Growing investments in dedicated electric vehicle platforms are accelerating aerodynamic innovation. Increasing consumer demand for longer-range electric vehicles further supports the segment.
The hybrid electric vehicle (HEV) segment is projected to register the fastest growth at an estimated CAGR of 8.0% from 2026 to 2033, supported by demand for fuel-efficient vehicles that combine internal combustion engines with electric propulsion. Aerodynamic improvements help reduce fuel consumption by lowering resistance during driving. Manufacturers are incorporating active grille shutters, underbody panels, rear spoilers, and optimized exterior profiles into hybrid vehicle designs. These technologies complement engine-management and regenerative-braking systems to improve overall efficiency. Growing demand for lower-emission mobility solutions is encouraging automakers to improve hybrid vehicle performance.
- By Mechanism
On the basis of mechanism, the automotive aerodynamic market is segmented into active systems and passive systems. The passive system is estimated to account for 61.4% of the market in 2025 under one market-segmentation estimate. Passive aerodynamic systems include fixed spoilers, diffusers, side skirts, air dams, and underbody panels. These components improve airflow without requiring electronic actuators or control systems. Their relatively straightforward design makes them suitable for a broad range of vehicle models. Automakers can incorporate passive components without adding significant system complexity. Their cost-effectiveness and suitability for mass production support continued demand.
The active system is expected to be the fastest-growing segment, with an estimated CAGR of 9.4% from 2026 to 2033. Active aerodynamic systems adjust airflow according to vehicle speed, cooling requirements, or driving conditions. These systems include active grille shutters, deployable spoilers, and adjustable aerodynamic flaps. They help manufacturers balance drag reduction, thermal management, and vehicle stability. Their integration into electric and premium vehicles is increasing as automakers seek to improve efficiency and performance. Advancements in electronic controls and actuator technology are expected to support further adoption.
- By Vehicle Type
On the basis of vehicle type, the automotive aerodynamic market is segmented into light-duty vehicles and heavy commercial vehicles. The light-duty vehicles segment dominated the market with an estimated share of 81% in 2025, supported by high production volumes of passenger cars, sport utility vehicles, and light commercial vehicles. Automakers incorporate aerodynamic components to improve fuel efficiency, reduce wind noise, and enhance vehicle stability. Growing adoption of electric passenger vehicles is further increasing demand for drag-reduction technologies. Air dams, spoilers, grille shutters, and underbody panels are widely used to optimize airflow. Manufacturers are incorporating aerodynamic improvements into new vehicle platforms to meet efficiency targets.
The heavy commercial vehicles segment is projected to register the fastest growth at an estimated CAGR of 6.0% from 2026 to 2033, driven by the need to reduce fuel consumption and operating costs across freight transportation. Trucks and other heavy commercial vehicles experience substantial aerodynamic resistance because of their large frontal areas. Gap fairings, roof deflectors, side skirts, and underbody panels help streamline airflow around the cab and trailer. Fleet operators are increasingly evaluating aerodynamic upgrades to improve fuel economy over long-distance routes. Emission-reduction initiatives and growing interest in electric trucks are further supporting adoption. Continued focus on operational efficiency is expected to increase demand for aerodynamic solutions in commercial transportation.
- By Application
On the basis of application, the automotive aerodynamic market is segmented into air dams, diffusers, gap fairings, grille shutters, side skirts, spoilers, and wind deflectors. The spoiler segment dominated the market with an estimated share of 39% in 2025, supported by widespread integration across passenger cars, sports vehicles, and electric vehicles. Spoilers help manage airflow at the rear of a vehicle and improve stability by controlling aerodynamic lift. Automakers use fixed and adjustable spoiler designs to balance aerodynamic efficiency, handling, and styling. Growing demand for performance-oriented vehicles is encouraging manufacturers to develop advanced spoiler configurations. Lightweight materials and improved component integration are further enhancing their application.
The grille shutter segment is projected to register the fastest growth at an estimated CAGR of 6.9% from 2026 to 2033, driven by increasing adoption of intelligent airflow management and improved vehicle efficiency. Grille shutters regulate airflow into the engine compartment or cooling system according to operating requirements. Closing the shutters when maximum cooling is unnecessary helps reduce aerodynamic drag. These components can also support thermal management in hybrid and electric vehicle platforms. Advances in electronic controls and vehicle sensors are improving responsiveness to changing driving conditions. Growing emphasis on energy efficiency and aerodynamic optimization is expected to strengthen demand for grille shutter systems.
Which Region Holds the Largest Share of the Automotive Aerodynamic Market?
- North America dominated the automotive aerodynamic market with the largest revenue share of 31% in 2025, supported by established automotive manufacturers, strong R&D investments, stringent fuel-efficiency standards, and increasing adoption of advanced aerodynamic technologies.
- The region also benefits from the presence of major automakers and automotive technology suppliers, increasing adoption of electric vehicles, and stringent vehicle efficiency standards. Growing use of active grille shutters, spoilers, diffusers, and underbody aerodynamic systems to improve fuel economy, vehicle stability, and electric driving range continues to support regional market growth.
U.S. Automotive Aerodynamic Market Insight
The U.S. automotive aerodynamic market is witnessing steady growth due to rising investments in vehicle efficiency, advanced automotive engineering, and electric vehicle development. The country’s established automotive industry, along with increasing adoption of active aerodynamic systems, lightweight materials, and computational fluid dynamics technologies, is driving demand across passenger and commercial vehicle applications. In addition, growing emphasis on reducing fuel consumption, improving vehicle stability, and extending electric vehicle driving range is accelerating the integration of aerodynamic components across vehicle designs.
Asia-Pacific Automotive Aerodynamic Market Insight
The Asia-Pacific automotive aerodynamic market is expected to witness rapid growth, driven by expanding automotive production, increasing electric vehicle adoption, and rising investments in advanced vehicle technologies across countries such as China, Japan, and India. Growing demand for fuel-efficient vehicles, increasing integration of active grille shutters and aerodynamic body components, and expanding automotive manufacturing capabilities are supporting regional market expansion. In addition, rising investments in vehicle electrification, lightweight materials, and aerodynamic research are accelerating the adoption of advanced aerodynamic solutions across passenger and commercial vehicles.
Japan Automotive Aerodynamic Market Insight
The Japan automotive aerodynamic market is witnessing consistent growth due to rising investments in automotive innovation, vehicle efficiency, and advanced engineering technologies. Automotive manufacturers are increasingly incorporating streamlined body designs, active airflow-control systems, spoilers, and underbody aerodynamic components to improve vehicle performance and energy efficiency. Moreover, the growing development of hybrid and electric vehicles, combined with Japan’s focus on lightweight vehicle design and advanced manufacturing technologies, is further contributing to market growth.
China Automotive Aerodynamic Market Insight
The China automotive aerodynamic market is growing rapidly, driven by expanding electric vehicle production, increasing automotive manufacturing capacity, and rising demand for energy-efficient mobility solutions. Growing adoption of active grille shutters, aerodynamic body panels, diffusers, and underbody systems across electric and conventional vehicles is significantly boosting market demand. In addition, rising investments in automotive R&D, growing competition among electric vehicle manufacturers, and continuous advancements in vehicle design technologies are positioning China as a key market for automotive aerodynamic solutions globally.
U.K. Automotive Aerodynamic Market Insight
The U.K. automotive aerodynamic market is experiencing steady growth, supported by rising adoption of advanced vehicle design technologies, increasing electric vehicle development, and continued innovation across automotive and motorsport applications. Growing investments in aerodynamic testing, computational fluid dynamics, and wind tunnel facilities are contributing to market development. Furthermore, increasing use of lightweight materials, active aerodynamic components, and energy-efficient vehicle designs is improving vehicle performance and efficiency, positioning the U.K. as an important innovation hub in the automotive aerodynamic industry.
Germany Automotive Aerodynamic Market Insight
The Germany automotive aerodynamic market is expanding steadily due to the country’s strong automotive manufacturing base, advanced engineering capabilities, and increasing adoption of next-generation vehicle technologies. Automotive manufacturers and suppliers are increasingly incorporating aerodynamic body designs, active grille shutters, spoilers, diffusers, and optimized underbody systems to improve efficiency and driving stability. Continuous advancements in electric vehicle engineering, computational fluid dynamics, and wind tunnel testing, along with the automotive industry's focus on reducing energy consumption and improving vehicle performance, are further driving market growth in Germany.
Which are the Top Companies in Automotive Aerodynamic Market?
The automotive aerodynamic industry is primarily led by well-established companies, including:
- Magna International Inc. (Canada)
- Valeo (France)
- Röchling SE & Co. KG (Germany)
- OPmobility SE (France)
- FORVIA SE (France)
- Samvardhana Motherson International Limited (India)
- SRG Global Inc. (U.S.)
- POLYTEC Holding AG (Austria)
- Plasman Inc. (Canada)
- INOAC CORPORATION (Japan)
- AISIN CORPORATION (Japan)
- DENSO CORPORATION (Japan)
- MAHLE GmbH (Germany)
- Continental AG (Germany)
- ZF Friedrichshafen AG (Germany)
- Robert Bosch GmbH (Germany)
- Brose Fahrzeugteile SE & Co. KG (Germany)
- Webasto SE (Germany)
- Gestamp Automoción, S.A. (Spain)
- Toyota Industries Corporation (Japan)
What are Latest Developments in Automotive Aerodynamic Market?
- In June 2025, Toyota announced the GR Yaris Aero Performance grade, featuring six aerodynamic components developed using motorsport experience and driver feedback. The upgrades include a large cooling duct, front lip spoiler, adjustable rear spoiler, optimized underbody cover, fender ducts, and rear bumper ducts. These features are designed to improve engine cooling, airflow management, high-speed stability, and aerodynamic performance, demonstrating how motorsport engineering is being incorporated into road vehicles.
- In April 2025, Audi introduced the new A6 Sedan, highlighting aerodynamic efficiency as a key element of its design. The vehicle achieved a drag coefficient of 0.23, which Audi described as the lowest for a combustion-engine production model in its history. Its aerodynamic development, combined with adaptive air suspension and other engineering features, aims to improve efficiency, comfort, and long-distance driving performance
- In October 2024, Honda unveiled next-generation technologies for its Honda 0 Series models, including an active aerodynamic system that automatically deploys a front aero deflector according to vehicle speed and other conditions. Positioned beneath the vehicle floor, the system is designed to reduce air resistance while supporting downforce and straight-line stability. The development reflects automakers’ increasing focus on integrating active aerodynamic technologies into future electric vehicles.
- In January 2024, Hyundai Motor and Kia unveiled their Active Air Skirt technology, designed to reduce aerodynamic resistance around the front wheels of electric vehicles during high-speed driving. The system deploys at higher speeds and retracts when it is no longer needed. Testing on the Genesis GV60 indicated a 2.8% improvement in drag performance, with the potential to increase driving range by approximately 6 km. The technology highlights the growing importance of active aerodynamic solutions in improving electric vehicle efficiency and stability
- In January 2021, Opel introduced the new Mokka with an aerodynamically optimized design, incorporating air curtains, an active cooling shutter, refined exterior mirrors, underbody cladding, and a rear roof spoiler. The vehicle achieved a drag coefficient of 0.32, while motorway-speed drag was reduced by 16% compared with its predecessor. These enhancements were developed using computational fluid dynamics and wind-tunnel testing to improve aerodynamic efficiency, fuel economy, and emissions performance.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.