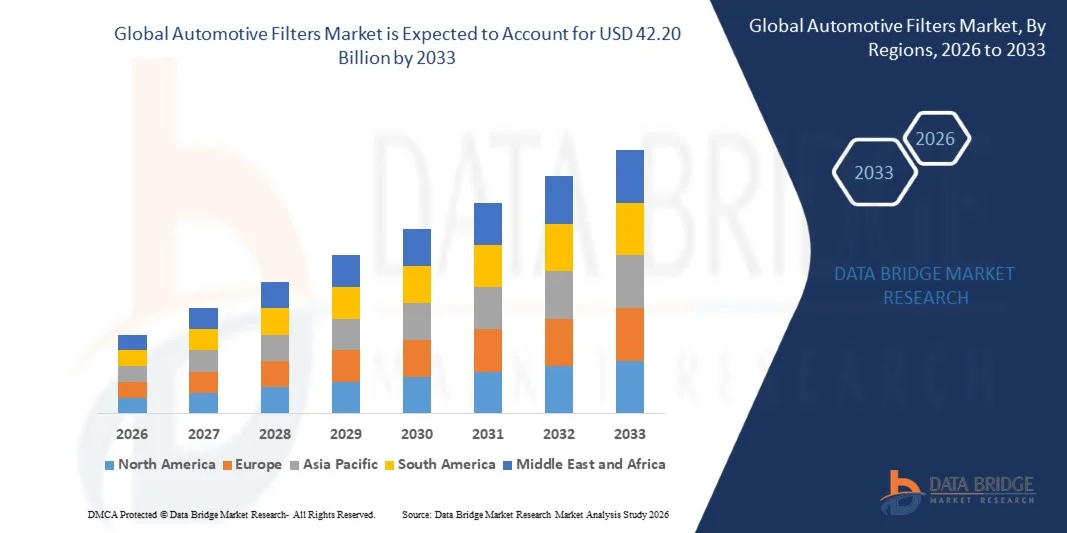
What is the Automotive Filters Market Size and Growth Rate?
- As per Data Bridge Market Research analysis, the automotive filters market was valued at USD 27.50 Billion in 2025 and is projected to reach USD 42.20 Billion by 2033, growing at a CAGR of 5.50% from 2026 to 2033.
- The market registers strong growth driven by rising global vehicle production, growing demand for improved engine efficiency and fuel economy, and stricter environmental regulations mandating reduced particulate and emissions output across passenger and commercial vehicle fleets.
- Rising consumer focus on vehicle performance and durability, expanding adoption of advanced nanofiber filtration media, and growing aftermarket replacement demand from an expanding global vehicle parc together reinforce steady, long-term category growth across both developed and emerging automotive markets.
Market Size & Forecast
- Global Market Value (2025): USD 27.50 Billion
- Expected Market Value (2033): USD 42.20 Billion
- Forecast CAGR (2026–2033): 5.50%
- Leading Region in 2025: Asia-Pacific
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Automotive Filters Market?
- Asia-Pacific dominated the global automotive filters market with the largest revenue share of 48.94% in 2025, driven by the region's robust automotive manufacturing base, rising disposable incomes, and strong demand for passenger vehicles across China, India, and Japan.
- Asia-Pacific holds both the largest market share and the fastest growth trajectory, fueled by expanding vehicle production capacity, rising urbanization, and growing enforcement of vehicle emissions standards across the region.
- The oil filters segment commands 33.80% of the filter type category in 2025, anchored by mandatory replacement at every engine oil service interval across internal combustion engine vehicles, generating the highest filter replacement frequency of any automotive filter category.
- The passenger cars vehicle type segment holds the largest share of the market in 2025, supported by the scale of global passenger vehicle production and the SUV segment's growing share of new vehicle sales.
- The aftermarket sales channel accounts for the majority of unit volume, driven by the sheer scale of the existing global vehicle parc requiring recurring, scheduled filter replacement independent of new vehicle production levels.
- The cabin air filters segment registers the fastest growth among filter types, with demand accelerating at a CAGR of 4.90% from 2025 to 2035, driven by rising urban pollution levels and growing consumer awareness of in-cabin air quality.
- The internal combustion engine (ICE) fuel type segment dominates the market in 2025, while the battery electric vehicle (BEV) segment registers the fastest growth, driven by rising demand for specialized cabin air and battery thermal management filtration systems.
Report Scope and Automotive Filters Market Segmentation
|
Attributes |
Automotive Filters Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Automotive Filters Market?
- Manufacturers are advancing high-efficiency particulate air (HEPA) grade cabin filtration technology to address rising consumer demand for premium in-cabin air quality protection.
- In 2025, Camfil published technical guidance confirming its HEPA-grade automotive cabin media captures at least 99.97% of particles at 0.3 micrometers, a benchmark now referenced across premium cabin filter programs from multiple manufacturers.
- Manufacturers are expanding light commercial vehicle filter portfolios to capture rising demand from e-commerce logistics and last-mile delivery fleets requiring high-frequency, high-reliability filter replacement.
- In September 2022, MANN-Filter expanded its light commercial vehicle air filter portfolio to deliver 95.00% market coverage for vehicle fleets across the European market, and the company continued extending this coverage strategy into 2025 and 2026 to serve growing e-commerce delivery fleet demand.
- Manufacturers commit to expanding HEPA-grade cabin filtration and fleet-focused product coverage as consumer and commercial buyers prioritize air quality and uptime, establishing premium filtration performance as the core innovation trend across the market.
What are the Key Drivers of the Automotive Filters Market?
- Rising vehicle production volumes across major manufacturing economies drive sustained original equipment demand for air, oil, fuel, and cabin filtration systems.
- In September 2024, the India Brand Equity Foundation reported that India produced 2,773,039 vehicles that month, demonstrating the scale of vehicle production growth in a single major emerging market and its corresponding filter demand.
- Stricter environmental regulations mandating reduced particulate and emissions output continue to compel automakers and fleet operators to install higher-efficiency filtration systems across new and existing vehicles.
- In 2025, the top five automotive filter manufacturers, including Mann+Hummel, Atmus, DENSO, MAHLE, and Robert Bosch, collectively held a 48.00% share of the global market, reflecting sustained industry-wide investment in advanced filtration technology to meet tightening emissions standards.
- Rising vehicle production, tightening emissions regulations, and expanding global vehicle parc together sustain durable, multi-year replacement demand across the automotive filters value chain.
Which Factors are Challenging the Growth of the Automotive Filters Market?
- High replacement costs for premium and specialized filtration products limit adoption among price-sensitive vehicle owners, particularly in emerging automotive markets.
- In 2025, industry analysis reported that high replacement costs affect 34.00% of automotive filter users, while 28.00% report limited availability of premium filter materials in certain regional markets.
- Counterfeit and substandard aftermarket filter products continue to circulate in price-sensitive markets, undermining consumer trust and creating safety and performance risks for vehicle owners.
- Rising adoption of battery electric vehicles, which require fewer traditional filtration components than internal combustion engine vehicles, presents a long-term structural headwind for conventional oil and fuel filter demand.
- High replacement costs, counterfeit product circulation, and the long-term structural shift toward electric vehicles together create headwinds that manufacturers address through product innovation and expanded electric-vehicle-specific filtration portfolios.
How is the Automotive Filters Market Segmented?
The automotive filters market is segmented on the basis of filter type, vehicle type, filter media, sales channel, fuel type, material type, filter design, end user, distribution channel, and replacement cycle.
- By Filter Type
On the basis of filter type, the global automotive filters market is segmented into air filters, oil filters, fuel filters, cabin air filters, and transmission filters. The oil filters segment commands 33.80% of the market share in 2025, anchored by mandatory replacement at every engine oil service interval across all internal combustion engine vehicle types, generating the highest filter replacement frequency of any automotive filter category.
The cabin air filters segment registers the fastest growth, with demand accelerating at a CAGR of 4.90% from 2025 to 2035, driven by rising urban pollution levels and growing consumer awareness of in-cabin air quality and allergen filtration performance.
- By Vehicle Type
On the basis of vehicle type, the global automotive filters market is segmented into passenger cars, light commercial vehicles, and heavy commercial vehicles. The passenger cars segment holds a 71.00% share of the market in 2025, supported by the scale of global passenger vehicle production and rising SUV sales that drive higher-capacity filter requirements.
The light commercial vehicles segment registers the fastest growth at a CAGR of 3.40% over the forecast period, driven by rising e-commerce logistics fleets requiring timely, high-frequency filter replacement to maintain fleet uptime.
- By Filter Media
On the basis of filter media, the global automotive filters market is segmented into cellulose fiber, synthetic fiber, combination media, and nanofiber media. The cellulose fiber segment leads the market with a 48.00% share in 2025, reflecting its established cost-effectiveness and widespread compatibility with standard replacement filter formats.
The nanofiber media segment registers the fastest growth at a CAGR of 7.80% from 2026 to 2033, driven by rising OEM adoption of high-efficiency nanofiber technology delivering superior particulate capture with lower airflow restriction.
- By Sales Channel
On the basis of sales channel, the global automotive filters market is segmented into OEM and aftermarket. The aftermarket segment commands 54.00% of the market share in 2025, driven by the sheer scale of the existing global vehicle parc requiring recurring, scheduled filter replacement independent of new vehicle production volumes.
The OEM segment registers the fastest growth at a CAGR of 6.10% from 2026 to 2033, driven by rising integration of advanced filtration systems directly into new vehicle platforms during initial manufacturing.
- By Fuel Type
On the basis of fuel type, the global automotive filters market is segmented into internal combustion engine (ICE), hybrid electric vehicle (HEV), and battery electric vehicle (BEV). The internal combustion engine segment dominates the market with a 78.00% share in 2025, reflecting the continued global majority of ICE vehicle production and the multi-filter requirements of combustion-based powertrains.
The battery electric vehicle (BEV) segment registers the fastest growth at a CAGR of 12.40% from 2026 to 2033, driven by rising demand for specialized cabin air and battery thermal management filtration systems unique to electric vehicle architectures.
- By Material Type
On the basis of material type, the global automotive filters market is segmented into paper filters, foam filters, and metal filters. The paper filters segment dominates the market with a 72.00% share in 2025, reflecting its cost-effectiveness and established, high-volume manufacturing infrastructure across the global filter supply chain.
The metal filters segment registers the fastest growth at a CAGR of 6.70% from 2026 to 2033, driven by rising demand for durable, high-temperature-resistant filtration in heavy commercial vehicle and off-highway applications.
- By Filter Design
On the basis of filter design, the global automotive filters market is segmented into panel filters, cylindrical filters, spin-on filters, and cartridge filters. The spin-on filters segment dominates the market with a 41.00% share in 2025, reflecting its widespread use in oil filtration applications for its ease of installation and replacement.
The cartridge filters segment registers the fastest growth at a CAGR of 6.20% from 2026 to 2033, driven by rising OEM preference for cartridge designs that reduce plastic waste compared with fully disposable spin-on formats.
- By End User
On the basis of end user, the global automotive filters market is segmented into individual vehicle owners, fleet operators, and service centers & garages. The service centers & garages segment dominates the market with a 46.00% share in 2025, reflecting the primary role of professional service networks in scheduled vehicle maintenance and filter replacement.
The fleet operators segment registers the fastest growth at a CAGR of 6.90% from 2026 to 2033, driven by rising commercial fleet sizes and growing adoption of predictive maintenance programs requiring consistent filter replacement schedules.
- By Distribution Channel
On the basis of distribution channel, the global automotive filters market is segmented into authorized dealerships, independent auto parts retailers, and online retail. The independent auto parts retailers segment dominates the market with a 45.00% share in 2025, reflecting broad geographic coverage and competitive pricing relative to authorized dealership networks.
The online retail segment registers the fastest growth at a CAGR of 9.30% from 2026 to 2033, driven by rising consumer comfort with purchasing standardized replacement parts through e-commerce platforms.
- By Replacement Cycle
On the basis of replacement cycle, the global automotive filters market is segmented into every service interval and extended-life/long-life filters. The every service interval segment dominates the market with a 68.00% share in 2025, reflecting standard OEM-recommended maintenance schedules across the majority of the global vehicle parc.
The extended-life/long-life filters segment registers the fastest growth at a CAGR of 6.40% from 2026 to 2033, driven by rising consumer preference for reduced maintenance frequency and total cost of ownership.
Which Region Holds the Largest Share of the Automotive Filters Market?
- Asia-Pacific dominated the automotive filters market and accounted for the largest revenue share of 48.94% in 2025, driven by the region's robust automotive manufacturing base, rising disposable incomes, and strong demand for passenger vehicles across China, India, and Japan.
- The region combines the largest current market share with the fastest regional growth trajectory, supported by expanding vehicle production capacity, rising urbanization, and growing enforcement of vehicle emissions standards across major Asian automotive manufacturing hubs.
China Automotive Filters Market Insight
The China automotive filters market grows rapidly, supported by the country's position as the world's largest vehicle production base and expanding domestic emissions regulations. Domestic and international filter manufacturers expand production capacity to serve both original equipment and aftermarket replacement demand across China's vast vehicle parc.
India Automotive Filters Market Insight
The India automotive filters market expands steadily, driven by rising vehicle production volumes, with the India Brand Equity Foundation reporting 2,773,039 vehicles produced in September 2024 alone. Growing passenger vehicle ownership and expanding service center networks support strong replacement filter demand across India.
U.S. Automotive Filters Market Insight
The U.S. automotive filters market grows steadily, supported by a mature aftermarket distribution network and rising consumer focus on vehicle performance and durability. Leading manufacturers, including Donaldson Company and Cummins, expand nanofiber and high-efficiency filtration product lines to serve both passenger and commercial vehicle segments.
Germany Automotive Filters Market Insight
The Germany automotive filters market grows steadily, anchored by the country's advanced automotive manufacturing base and the presence of leading global filter manufacturers, including Mann+Hummel, Robert Bosch, MAHLE, and Hengst. Stringent European Union emissions regulations continue to drive demand for advanced filtration technology.
Japan Automotive Filters Market Insight
The Japan automotive filters market grows steadily, supported by the country's advanced automotive manufacturing base and strong presence of leading filter manufacturers, including DENSO, IBIDEN, and NGK Insulators. Rising adoption of hybrid and electric vehicle platforms drives demand for specialized filtration systems tailored to alternative powertrains.
Which are the Top Companies in Automotive Filters Market?
The automotive filters industry is primarily led by well-established companies, including:
- Mann+Hummel International GmbH & Co. KG (Germany)
- Robert Bosch GmbH (Germany)
- MAHLE GmbH (Germany)
- DENSO Corporation (Japan)
- Donaldson Company, Inc. (U.S.)
- Cummins Inc. (U.S.)
- Sogefi S.p.A. (Italy)
- NGK Insulators, Ltd. (Japan)
- Hengst SE (Germany)
- K&N Engineering, Inc. (U.S.)
- IBIDEN Co., Ltd. (Japan)
- Hollingsworth & Vose Company (U.S.)
- Fram Group IP LLC (U.S.)
- Purolator, Inc. (U.S.)
- Filtration Group Corporation (U.S.)
What are Latest Developments in Automotive Filters Market?
- In 2025, Camfil published technical guidance confirming its HEPA-grade automotive cabin media captures at least 99.97% of particles at 0.3 micrometers, a benchmark now referenced across premium cabin filter programs from multiple manufacturers.
- In September 2024, the India Brand Equity Foundation reported that India produced 2,773,039 vehicles that month, reflecting robust regional vehicle production growth and corresponding original equipment filter demand.
- In 2025, the top five automotive filter manufacturers, including Mann+Hummel, Atmus, DENSO, MAHLE, and Robert Bosch, collectively held a 48.00% share of the global market, reflecting continued industry-wide consolidation and investment in advanced filtration technology.
- In 2025, industry analysis confirmed that eco-friendly filter adoption increased 42.00% year over year, while demand for cabin air filters in passenger vehicles grew 36.00%, reflecting accelerating consumer and regulatory focus on sustainable, air-quality-focused filtration.
- In 2025, filter manufacturers continued expanding investment in advanced nanofiber filtration technology, with 31.00% of leading manufacturers reporting active nanofiber product development programs aimed at improving filtration efficiency while reducing airflow restriction.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.