What is the Automotive Smart Glass Market Size and Growth Rate?
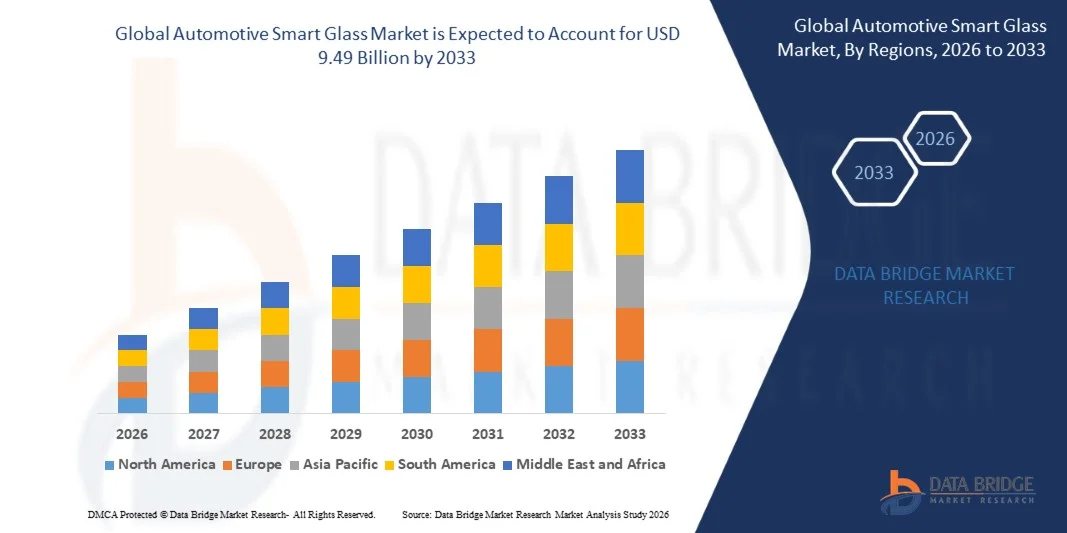
- As per Data Bridge Market Research analysis, the automotive smart glass market was valued at USD 3.40 billion in 2025 and is projected to reach USD 9.49 billion by 2033, growing at a CAGR of 13.70% from 2026 to 2033.
- The market is experiencing consistent growth driven by rising demand for advanced vehicle glazing solutions, rapid adoption of smart glass technologies in panoramic roofs and windows, and expanding applications across premium passenger vehicles, electric vehicles, and luxury automotive segments.
- The increasing demand for enhanced passenger comfort, energy efficiency, glare reduction, and privacy, combined with the growing integration of advanced glazing technologies in modern vehicles, is compelling automotive manufacturers to adopt smart glass solutions. Electrochromic, suspended particle device, and polymer dispersed liquid crystal technologies are increasingly replacing conventional glazing in premium and electric vehicles, offering dynamic light control, improved thermal management, and enhanced cabin experiences.
Market Size & Forecast
- Global Market Value (2025): USD 3.40 Billion
- Expected Market Value (2033): USD 9.49 Billion
- Forecast CAGR (2026–2033): 13.70%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Automotive Smart Glass Market?
- North America dominated the automotive smart glass market with the largest revenue share of 41.92% in 2025, supported by strong adoption of advanced vehicle glazing technologies, premium vehicle penetration, and the presence of established automotive glass manufacturers.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 16.02% from 2026 to 2033, fueled by rapid vehicle production, rising electric vehicle adoption, increasing premiumization, and growing integration of panoramic and smart glazing technologies.
- The internal combustion engine vehicles segment led the market with a 66.52% share in 2025, driven by the large installed base of conventional vehicles and continued incorporation of smart glazing into premium and high-end automotive models
- Battery electric vehicles are the fastest-growing propulsion type, projected to register a CAGR of 17.03%, reflecting the surge in expansion of electric vehicle production and increasing integration of advanced comfort technologies.
- The electrochromic glass segment dominated the technology type category with a 46.05% revenue share in 2025, led by its established automotive applications and ability to dynamically regulate light transmission and glare.
- Sunroof & panoramic roof glass accounted for 73.42% of the market share in 2025, preferred by increasing adoption of large-area glass roofs in premium vehicles and growing consumer demand for enhanced cabin aesthetics and openness
- The smart HUD & display glazing segment is the fastest-growing application category, with a CAGR of 16.44%, driven by the increasing convergence of smart glazing with digital vehicle displays and advanced driver information systems.
Report Scope and Automotive Smart Glass Market Segmentation
|
Attributes |
Automotive Smart Glass Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Automotive Smart Glass Market?
- Automotive manufacturers are increasingly integrating dynamic smart glass across panoramic roofs, sunroofs, side windows, and sun visors to improve passenger comfort, privacy, glare control, and thermal management while enhancing the premium appearance of vehicles.
- For instance, in April 2025, Gauzy announced that Mercedes-Benz incorporated its dual SPD and PDLC smart glass technologies into approximately 75% of the glazing of the Vision V show car, demonstrating the increasing use of multifunctional smart glazing throughout vehicle interiors.
- Advanced smart glass technologies are enabling individualized light and privacy control, allowing occupants to dynamically adjust glass transparency according to sunlight, visibility, and comfort requirements.
- Automotive suppliers are increasingly combining SPD, PDLC, and electrochromic technologies with digital displays and intelligent vehicle systems to create multifunctional glazing solutions.
- For instance, in January 2025, Gentex unveiled a new film-based electrochromic dimmable sunroof technology at CES 2025, alongside dimmable sun visors with integrated displays, highlighting the convergence of smart glass with vehicle electronics and driver information systems.
- As automakers continue to prioritize premium cabin experiences, energy efficiency, EV range optimization, and intelligent vehicle interiors, the adoption of multifunctional smart glass is expected to accelerate, reinforcing dynamic glazing as an important component of next-generation automotive design.
What are the Key Drivers of the Automotive Smart Glass Market?
- The rapid expansion of electric and premium vehicles has significantly increased demand for smart glass capable of controlling solar heat, reducing cabin cooling requirements, and improving passenger comfort.
- For instance, in July 2025, Gauzy and Research Frontiers announced the first customer deliveries of the Cadillac CELESTIQ with serially produced SPD smart glass, featuring a four-zone dimmable roof designed to control light and heat while supporting EV efficiency.
- Automotive OEMs are integrating smart glazing into panoramic roofs, windows, and sun visors to provide dynamic shading, privacy, glare reduction, and thermal management without relying on conventional mechanical shades.
- For instance, in January 2025, Gauzy showcased SPD and PDLC smart glass sunroofs, side windows, and smart sun visors at CES 2025, demonstrating the expansion of smart glazing across multiple vehicle applications.
- With automotive manufacturers increasingly emphasizing vehicle electrification, passenger personalization, and energy-efficient cabin technologies, smart glass will remain an important technology for developing premium and next-generation connected vehicles.
What Factors are Challenging the Growth of the Automotive Smart Glass Market?
- Advanced automotive smart glass requires specialized electrochromic, SPD, or PDLC materials, electronic control systems, and complex glass integration, increasing manufacturing complexity and overall vehicle costs.
- For instance, in September 2024, an article published in Small that electrochromic smart windows face high costs due to expensive tin-doped indium oxide (ITO) and thick electrochromic films, prompting research into lower-cost alternatives
- These higher costs can limit adoption in mass-market vehicles, particularly where manufacturers prioritize affordable glazing solutions and strict cost control.
- The specialized manufacturing requirements, integration complexity, and higher component costs associated with advanced smart glass continue to restrict widespread deployment, particularly in price-sensitive vehicle segments.
- For instance, in June 2025, a study published in Solar Energy Materials and Solar Cells identified high device costs, insufficient product quality, and manufacturing-related issues such as delamination as major barriers limiting the broader commercialization of electrochromic smart glass technologies.
- This cost barrier slows penetration beyond premium and luxury vehicles, limiting broader adoption despite increasing demand for intelligent glazing and enhanced passenger comfort.
How is the Automotive Smart Glass Market Segmented?
The automotive smart glass market is segmented on the basis of propulsion type, technology type, and application.
- By Propulsion Type
On the basis of propulsion type, the automotive smart glass market is segmented into internal combustion engine vehicles, battery electric vehicles, hybrid electric vehicles, plug-in hybrid electric vehicles, and fuel cell electric vehicles. The internal combustion engine vehicles segment dominated the market with a 66.52% share in 2025, owing to the large installed base of conventional vehicles and continued incorporation of smart glazing into premium and high-end automotive models. ICE-powered vehicles continue to represent a substantial portion of global vehicle production and sales, supporting broad demand for advanced glazing solutions. Automotive manufacturers are increasingly integrating smart glass into sunroofs, windows, and mirrors to improve comfort, privacy, glare control, and styling. Established automotive manufacturing and supplier networks also facilitate the integration of smart glass into conventional vehicle platforms.
The battery electric vehicles segment is projected to register the fastest growth at a CAGR of 17.03% from 2026 to 2033, driven by the rapid expansion of electric vehicle production and increasing integration of advanced comfort technologies. Smart glass can help regulate solar heat entering the cabin, supporting improved thermal management in electric vehicles. Better control of cabin temperature can also reduce the energy burden associated with climate-control systems and support vehicle efficiency. EV manufacturers are increasingly using panoramic roofs and large-area glazing as premium design features, creating additional demand for switchable glass. Growing consumer interest in privacy, glare reduction, personalized cabin environments, and digitally controlled vehicle features is further supporting adoption. Smart glass also complements the broader development of connected and intelligent electric vehicle interiors.
- By Technology Type
On the basis of technology type, the automotive smart glass market is segmented into electrochromic glass, suspended particle device (SPD) glass, polymer dispersed liquid crystal (PDLC) glass, thermochromic glass, photochromic glass, hybrid & multi-stack smart glass, and other emerging technologies. The electrochromic glass segment dominated the market with a 46.05% share in 2025, supported by its established automotive applications and ability to dynamically regulate light transmission and glare. The technology provides controlled tint adjustment while maintaining visibility, making it suitable for premium sunroofs, windows, and mirrors. Increasing demand for thermal comfort and solar-control capabilities is strengthening its use across advanced vehicle glazing systems. Improvements in switching performance, durability, and manufacturing processes are also encouraging broader OEM adoption. Automotive suppliers are continuing to improve electrochromic film architectures and module designs to simplify integration into vehicle platforms.
The suspended particle device (SPD) Glass segment is projected to register the fastest growth at a CAGR of 14.63% from 2026 to 2033, driven by its rapid switching performance and suitability for dynamic light and glare management. SPD glass enables quick changes in transparency, making it attractive for panoramic roofs and other large-area automotive glazing applications. The technology gives occupants greater control over sunlight and cabin brightness while supporting a premium interior experience. Increasing adoption of electric and luxury vehicles is creating additional opportunities for advanced switchable glazing technologies. Automotive manufacturers are also exploring SPD solutions for side windows, sunroofs, and other applications where rapid light control is beneficial. Continued improvements in smart-film technology and integration with electronic vehicle control systems are strengthening the commercial potential of SPD glass.
- By Application
On the basis of application, the automotive smart glass market is segmented into sunroof & panoramic roof glass, side windows, rear windows, windshields, rearview & exterior mirrors, smart HUD & display glazing, and other applications. The sunroof & panoramic roof glass segment dominated the market with a 73.42% share in 2025, driven by increasing adoption of large-area glass roofs in premium vehicles and growing consumer demand for enhanced cabin aesthetics and openness. Smart glazing allows vehicle occupants to manage glare and solar heat without compromising the panoramic view provided by large glass roofs. Automotive manufacturers are increasingly using switchable roof glass as a premium differentiation feature across high-end vehicle models. The technology also improves passenger comfort by providing greater control over light entering the cabin. Growing adoption of panoramic roof designs in modern vehicle platforms is further supporting demand for smart roof glazing.
The smart HUD & display glazing segment is projected to register the fastest growth at a CAGR of 16.44% from 2026 to 2033, reflecting the increasing convergence of smart glazing with digital vehicle displays and advanced driver information systems. Smart glazing can help optimize optical conditions for projected information and improve visibility under changing external lighting conditions. Increasing development of augmented-reality head-up displays is creating demand for advanced windshield and glazing technologies capable of supporting sophisticated information presentation. Integration with ADAS and connected vehicle systems is further expanding the functional role of vehicle glazing. Automakers are increasingly focusing on intelligent cockpit designs that combine safety, information, personalization, and visual comfort. Advancements in display-compatible glazing and electronically controlled optical technologies are improving the potential for broader automotive deployment.
Which Region Holds the Largest Share of the Automotive Smart Glass Market?
- North America dominated the automotive smart glass market with the largest revenue share of 41.92% in 2025, supported by strong adoption of advanced vehicle glazing technologies, premium vehicle penetration, and the presence of established automotive glass manufacturers.
- The region also benefits from rapid integration of smart and switchable glass into panoramic roofs, sunroofs, and advanced vehicle glazing, alongside strong demand for ADAS-compatible and digitally enabled automotive systems. Increasing adoption of electric vehicles, premium cabin technologies, and consumer preference for enhanced thermal comfort, glare control, and privacy continue to strengthen North America’s leadership position in the global market.
U.S. Automotive Smart Glass Market Insight
The U.S. automotive smart glass market is witnessing strong growth due to rising demand for advanced panoramic sunroofs, switchable glazing, and premium vehicle interior technologies. The country’s mature automotive industry, strong presence of luxury vehicle manufacturers, and increasing adoption of electric vehicles are driving demand for smart glass solutions. In addition, growing consumer preference for adjustable tinting, solar heat management, glare reduction, and enhanced cabin comfort is accelerating adoption across passenger vehicles. Increasing integration of electronically controlled glazing into next-generation vehicle designs is further supporting market expansion.
Asia-Pacific Automotive Smart Glass Market Insight
The Asia-Pacific automotive smart glass market is expected to witness rapid growth, driven by expanding vehicle production, rising electric vehicle adoption, and increasing incorporation of panoramic and intelligent glazing technologies across China, India, Japan, and South Korea. The region’s large automotive manufacturing base and growing demand for premium vehicle features are supporting market expansion. Increasing investments in advanced automotive components and smart mobility technologies are further strengthening regional demand. Additionally, rising consumer preference for spacious, technology-rich vehicle interiors is accelerating the adoption of dynamic glazing solutions.
Japan Automotive Smart Glass Market Insight
The Japan automotive smart glass market is witnessing consistent growth due to the country’s advanced automotive manufacturing ecosystem, strong focus on vehicle safety and innovation, and increasing adoption of intelligent glazing technologies. Automotive manufacturers are increasingly incorporating advanced glass solutions into passenger vehicles to improve thermal comfort, glare management, and cabin functionality. The growing integration of ADAS and other electronic vehicle technologies is also encouraging the use of sophisticated glazing systems. Moreover, continued emphasis on premium vehicle design and technologically advanced mobility solutions is supporting market growth in Japan.
China Automotive Smart Glass Market Insight
The China automotive smart glass market is growing rapidly, driven by expanding electric vehicle production, increasing adoption of panoramic roofs, and strong demand for technologically advanced vehicle interiors. Automotive manufacturers are increasingly integrating smart glazing into new-energy vehicles to provide improved solar control, thermal comfort, privacy, and cabin aesthetics. The country’s strong domestic automotive and glass manufacturing ecosystem is supporting faster commercialization of electrochromic, SPD, and PDLC technologies. In addition, rising adoption of intelligent vehicle features and growing consumer demand for premium in-cabin experiences are accelerating smart glass deployment across the Chinese automotive industry.
U.K. Automotive Smart Glass Market Insight
The U.K. automotive smart glass market is experiencing steady growth, supported by increasing adoption of premium vehicle technologies, electric vehicles, panoramic roofs, and electronically controlled glazing systems. Vehicle manufacturers are increasingly using electrochromic glass to provide occupants with adjustable roof tinting and improved solar heat management. Growing demand for enhanced passenger comfort, privacy, and sophisticated vehicle interiors is contributing to market expansion. Furthermore, the increasing integration of smart glass with digital vehicle controls is improving the functionality of advanced glazing systems and strengthening their adoption in the U.K. automotive market.
Germany Automotive Smart Glass Market Insight
The Germany automotive smart glass market is expanding steadily due to the country’s strong automotive manufacturing base, advanced engineering capabilities, and increasing integration of intelligent glazing into premium and electric vehicles. German automakers are increasingly incorporating switchable panoramic roofs to provide adjustable transparency, glare protection, thermal insulation, and personalized cabin experiences. Technological advancements in PDLC and other dynamic glazing solutions are supporting wider automotive applications. Moreover, continued focus on electrification, premium interior design, energy efficiency, and digitally controlled vehicle functions is further driving the adoption of smart glass technologies across Germany.
Which are the Top Companies in Automotive Smart Glass Market?
The automotive smart glass industry is primarily led by well-established companies, including:
- AGC Inc. (Japan)
- Asahi India Glass Limited (India)
- Central Glass Co., Ltd. (Japan)
- Corning Incorporated (U.S.)
- Fuyao Glass Industry Group Co., Ltd. (China)
- Gauzy Ltd and Entities (Israel)
- GENTEX CORPORATION (U.S.)
- AGP worldwide operations GmbH (Switzerland)
- KCC GLASS Corporation (South Korea)
- Magna International Inc. (Canada)
- Merck KGaA (Germany)
- Nippon Sheet Glass Co., Ltd. (Japan)
- Research Frontiers Inc. (U.S.)
- Compagnie de Saint-Gobain (France)
- SCHOTT AG (Germany)
- China Shanghai Yaohua Pilkington Glass Group Co., Ltd. (China)
- TAIWAN GLASS IND. CORP. (Taiwan)
- Vitro (Mexico)
- Webasto SE (Germany)
- Xinyi Glass Holdings Limited (Hong Kong)
What are Latest Developments in Automotive Smart Glass Market?
- In April 2025, Gauzy Ltd. announced that Mercedes-Benz had integrated its dual SPD and PDLC smart glass technology into approximately 75% of the glazing of the Vision V show car unveiled at Auto Shanghai 2025. The system combined dynamic shading and privacy functions across the vehicle’s side and quarter windows, while also enabling projection surfaces and an adaptive interior privacy partition. The development demonstrated the expanding use of multifunctional smart glass across next-generation luxury vehicle interiors and exteriors
- In January 2025, Gentex Corporation announced the introduction of a new film-based electrochromic dimmable sunroof glass technology at CES 2025. The company presented the technology for large panoramic sunroofs along with dimmable sun visors incorporating switchable vanity mirrors and transparent displays for driver alerts and notifications. The development highlighted the integration of electronically controlled glazing with advanced vehicle electronics and premium cabin features.
- In October 2024, Gauzy Ltd. announced that Ferrari had selected its SPD smart glass technology for serial production in Ferrari’s first SUV. Gauzy’s SPD Light Control Glass was incorporated into the panoramic roof, marking Ferrari’s first mass-production implementation of smart glass in an automotive design. The development represented a significant expansion of switchable glazing adoption among luxury vehicle manufacturers and demonstrated growing demand for dynamic roof technologies.
- In January 2023, Gauzy announced its collaboration with BMW on the BMW i Vision Dee concept vehicle, featuring SPD and PDLC smart glass technologies throughout the vehicle glazing. The concept demonstrated a smart windshield and individually controlled side windows capable of providing shading, privacy, and transparent display functions. The windshield also served as a platform for a high-contrast head-up display, illustrating the integration of smart glass with digital interfaces and advanced vehicle technologies.
- In September 2021, Gauzy Ltd. showcased advanced SPD and PDLC automotive smart glass applications at the IAA Mobility show in Munich. The company demonstrated active glazing solutions capable of providing shading, glare mitigation, temperature control, infotainment, and vehicle-to-vehicle and vehicle-to-pedestrian messaging functions. The presentation highlighted the potential of smart glass to evolve from conventional glazing into an active vehicle interface supporting comfort, safety, and connected mobility.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.