What is the Chip Scale Electronics Packaging Market Size and Growth Rate?
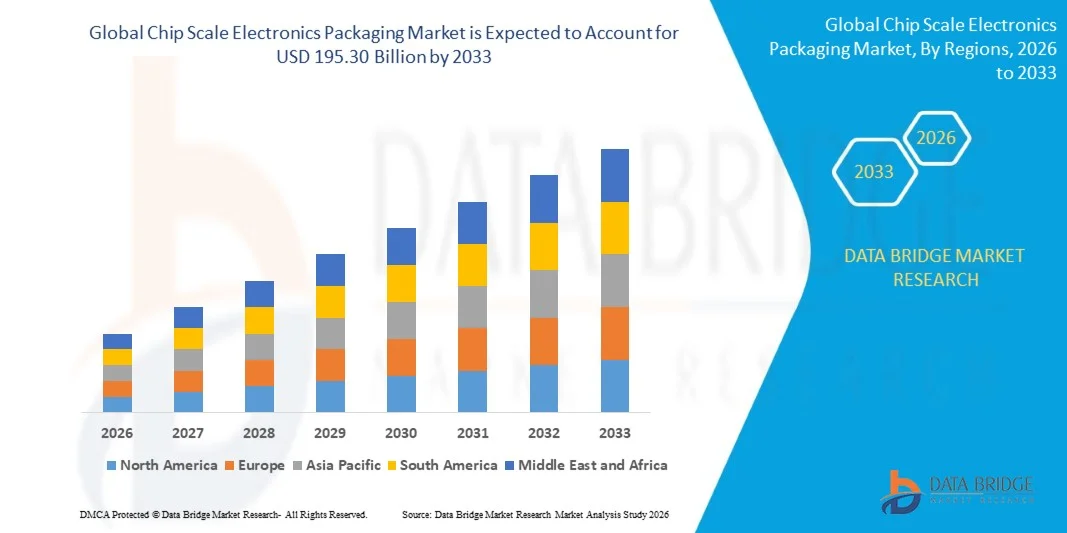
- As per Data Bridge Market Research analysis, the chip scale electronics packaging market was valued at USD 54.12 billion in 2025 and is projected to reach USD 195.30 billion by 2033, growing at a CAGR of 17.40% from 2026 to 2033.
- The market is experiencing consistent growth driven by rising demand for miniaturized and high-performance electronic devices, advancements in semiconductor packaging technologies, and increasing adoption of chip-scale packaging across consumer electronics, automotive, telecommunications, and other applications.
- The increasing adoption of IoT and wireless devices, combined with rising demand for consumer electronics and continued innovation in the electronics industry, is compelling semiconductor manufacturers to adopt compact and efficient chip-scale packaging solutions. These packages enable smaller form factors, improved performance, and efficient integration of semiconductor components, supporting their expanding use across developing and developed markets
Market Size & Forecast
- Global Market Value (2025): USD 54.12 Billion
- Expected Market Value (2033): USD 195.30 Billion
- Forecast CAGR (2026–2033): 17.40%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Chip Scale Electronics Packaging Market?
- North America dominated the chip scale electronics packaging market with the largest revenue share of 35.4% in 2025, supported by the strong presence of leading semiconductor companies, advanced manufacturing capabilities, and increasing investments in domestic semiconductor production and packaging technologies.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 10.2% from 2026 to 2033, fueled by the expansion of semiconductor manufacturing, rising demand for consumer electronics, and increasing investments in advanced chip-scale packaging technologies.
- The wafer level chip scale package segment led the market with a 45% share in 2025, driven by its compact footprint, short electrical pathways, and efficient wafer-level manufacturing
- Fan-out chip scale package are the fastest-growing package type, projected to register a CAGR of 9.0%, reflecting the surge in demand for high-density interconnections and advanced miniaturized semiconductor packages.
- The plastic segment dominated the material type category with a 55% revenue share in 2025, led by its cost-effectiveness, lightweight characteristics, electrical insulation properties, and suitability for high-volume semiconductor packaging.
- Consumer electronics accounted for 40% of the market share in 2025, preferred by the extensive use of CSP technologies in smartphones, tablets, wearables, and other compact electronic devices.
- The automotive segment is the fastest-growing application category, with a CAGR of 9.2%, driven by increasing electronic content in vehicles, vehicle electrification, and growing adoption of advanced driver-assistance systems
Report Scope and Chip Scale Electronics Packaging Market Segmentation
|
Attributes |
Chip Scale Electronics Packaging Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, geographically represented company-wise production and capacity, network layouts of distributors and partners, detailed and updated price trend analysis and deficit analysis of supply chain and demand. |
What is the Key Trend in the Chip Scale Electronics Packaging Market?
- Semiconductor manufacturers are increasingly adopting fan-out wafer-level packaging, heterogeneous integration, and advanced wafer-level packaging to achieve smaller form factors, higher I/O density, improved power efficiency, and greater performance in AI, mobile, and high-performance computing applications.
- For instance, in October 2024, Amkor Technology and TSMC announced a collaboration to bring advanced packaging and testing capabilities to Arizona, including TSMC’s Integrated Fan-Out (InFO) and Chip on Wafer on Substrate (CoWoS) technologies, to support high-performance computing, AI, and communications applications.
- Increasing integration of chiplets, redistribution layers, and 3D stacking is enabling manufacturers to integrate multiple semiconductor components within compact packages while improving bandwidth and system-level performance.
- Advanced packaging is also expanding beyond smartphones into AI accelerators, data-center processors, automotive electronics, networking equipment, and high-performance computing systems, increasing demand for compact and high-density package architectures.
- For instance, in May 2025, ASE Technology announced its FOCoS-Bridge with Through-Silicon Via (TSV) packaging technology, which reduces power loss by 3× while increasing I/O density and thermal dissipation for AI and high-performance computing applications, demonstrating the industry's shift toward high-density fan-out and heterogeneous chip integration.
- As semiconductor designs continue moving toward heterogeneous integration, higher I/O density, and smaller package footprints, the adoption of advanced chip-scale packaging is expected to accelerate, reinforcing wafer-level, fan-out, and 3D packaging as important technologies for next-generation electronics.
What are the Key Drivers of the Chip Scale Electronics Packaging Market?
- The rapid growth of AI, high-performance computing, 5G, and connected devices has significantly increased demand for compact semiconductor packages capable of delivering higher bandwidth, improved power efficiency, and greater system-level integration.
- For instance, in January 2025, NVIDIA CEO Jensen Huang stated that demand for TSMC’s advanced packaging remained strong as NVIDIA transitioned its latest Blackwell AI chips toward CoWoS-L packaging, with TSMC increasing capacity to meet the growing requirements of AI computing.
- Consumer electronics, automotive manufacturers, and data-center technology companies are increasingly integrating chip-scale and wafer-level packaging to reduce device size, improve electrical performance, and support increasingly complex semiconductor architectures.
- For instance, in May 2026, Amkor Technology announced additional land in Arizona to expand its advanced semiconductor packaging and test footprint, citing rising demand for advanced packaging and the growing requirements of AI and high-performance computing applications.
- With electronics manufacturers increasingly prioritizing miniaturization, higher performance, and efficient heterogeneous integration, demand for chip-scale electronics packaging will remain strong across next-generation computing, communications, automotive, and consumer electronics applications.
Which Factors are Challenging the Growth of the Chip Scale Electronics Packaging Market?
- Advanced chip-scale and wafer-level packaging requires significant investment in specialized manufacturing equipment, materials, process control, and high-precision inspection, increasing production costs and raising barriers for smaller packaging manufacturers.
- For instance, in May 2025, Semiconductor Engineering reported that advanced multi-die packaging faces challenges from die-to-RDL misalignment, changing warpage profiles, and coefficient-of-thermal-expansion (CTE) mismatch, which complicate manufacturing and reliability as package structures become more heterogeneous
- The increasing complexity of multi-die integration, fine-pitch redistribution layers, and 3D structures creates challenges related to yield, thermal management, warpage, reliability, and manufacturing consistency.
- For instance, in September 2025, NIST highlighted that advanced semiconductor packaging faces mechanical stress, distortion, electrical interference, environmental effects, and failure mechanisms, while the industry still requires improved material characterization and standardized measurement methods to control costly packaging failures.
- The high capital requirements and technical complexity associated with advanced packaging continue to restrict adoption among smaller manufacturers, while material characterization, metrology, and process-standardization challenges can further increase development time and production costs.
How is the Chip Scale Electronics Packaging Market Segmented?
The chip scale electronics packaging market is segmented on the basis of package type, material, application, and end user.
- By Package Type
On the basis of package type, the chip scale electronics packaging market is segmented into flip chip chip scale package, wire bonding chip scale package, wafer level chip scale package, fan-in chip scale package, fan-out chip scale package, and others. The wafer level chip scale package segment dominated the market with 45% share in 2025, owing to its compact footprint, short electrical pathways, and efficient wafer-level manufacturing. WLCSP is extensively used in smartphones, sensors, RF components, and other space-constrained electronic devices. The technology reduces package size and weight while maintaining strong electrical performance and supporting high-volume production. Its compatibility with miniaturized consumer electronics has strengthened its position as a leading CSP architecture
The fan-out chip scale package segment is projected to register the fastest growth at a CAGR of 9.0% during forecast period, driven by increasing demand for high-density interconnections and advanced miniaturized semiconductor packages. Fan-out packaging enables more I/O connections than conventional fan-in structures without substantially increasing package dimensions. It is increasingly used in smartphones, IoT devices, high-performance computing, and advanced automotive electronics. The technology also provides improved electrical and thermal characteristics by shortening interconnect paths. Growing semiconductor complexity and heterogeneous integration requirements are encouraging manufacturers to invest in fan-out manufacturing capabilities.
- By Material
On the basis of material, the chip scale electronics packaging market is segmented into plastic, metal, glass, and others. The plastic segment dominated the market with 55% share in 2025, supported by its cost-effectiveness, lightweight characteristics, electrical insulation properties, and suitability for high-volume semiconductor packaging. Plastic-based packaging materials are extensively used in consumer electronics where manufacturers prioritize compact dimensions and economical production. They also provide flexibility in molding complex package geometries and integrating semiconductor components into small devices. Increasing production of smartphones, wearables, IoT devices, and other portable electronics is supporting demand for plastic packaging materials. Improvements in molding compounds and encapsulation technologies are further enhancing package reliability and thermal performance.
The glass segment is projected to witness the fastest growth at a CAGR of 8.5% during forecast period, supported by increasing demand for advanced packaging substrates and high-performance semiconductor applications. Glass provides excellent dimensional stability and low electrical loss, making it attractive for high-density interconnect architectures. Its favorable coefficient of thermal expansion can also support improved reliability in advanced semiconductor packages. Growing adoption of glass-based substrates and interposers is being encouraged by increasing requirements for high-bandwidth and high-density electronic integration. Demand from AI, high-performance computing, telecommunications, and advanced consumer electronics is creating additional opportunities for glass-based packaging technologies.
- By Application
On the basis of application, the chip scale electronics packaging market is segmented into consumer electronics, aerospace & defense, automotive, telecommunication, and others. The consumer electronics segment dominated the market with 40% share in 2025, supported by the extensive use of CSP technologies in smartphones, tablets, wearables, and other compact electronic devices. Consumer electronics manufacturers continuously require smaller packages to accommodate increasing functionality within limited device footprints. CSP technologies provide reduced package size, shorter electrical paths, and efficient integration of semiconductor components. The rapid replacement cycle of smartphones and other portable electronics also generates sustained demand for compact semiconductor packages. Increasing adoption of IoT-enabled consumer devices is further expanding the addressable market for CSP solutions.
The automotive segment is projected to register the fastest growth at a CAGR of 9.2% during forecast period, driven by increasing electronic content in vehicles, vehicle electrification, and growing adoption of advanced driver-assistance systems. CSP technologies enable automotive manufacturers to integrate semiconductor components into increasingly compact electronic control units and sensor systems. The expansion of electric vehicles is increasing demand for power management, sensing, connectivity, and control electronics. Automotive applications also require packaging technologies capable of delivering reliability under temperature, vibration, and other demanding operating conditions. Increasing integration of radar, cameras, connectivity modules, and ADAS processors is creating additional demand for compact semiconductor packages.
- By End User
On the basis of end user, the chip scale electronics packaging market is segmented into original equipment manufacturers, original design manufacturers, and electronics manufacturing services providers. The original equipment manufacturers segment dominated the market with an 45% share in 2025, supported by the direct control these companies have over semiconductor specifications, product architecture, and packaging requirements. OEMs increasingly specify compact and high-performance CSP solutions to meet the miniaturization and functionality requirements of finished electronic products. Major electronics and semiconductor manufacturers use CSP technologies across consumer electronics, automotive, telecommunications, and industrial applications. Their large production volumes provide stable demand for advanced packaging solutions and encourage long-term relationships with packaging suppliers. OEMs also influence package selection through product roadmaps and performance requirements.
The electronics manufacturing services providers segment is projected to witness the fastest growth at a CAGR of 8.0% during forecast period, supported by increasing outsourcing of electronics assembly, testing, and manufacturing activities. EMS providers increasingly manage component procurement and assembly for OEMs and ODMs, creating indirect demand for CSP technologies. Their ability to serve multiple customers across consumer electronics, telecommunications, industrial, and automotive markets provides diversified demand for compact semiconductor packages. The growing complexity of electronic products is also encouraging OEMs to rely on specialized EMS companies with advanced manufacturing capabilities. EMS providers can consolidate packaging requirements across multiple product programs, improving manufacturing efficiency and supply-chain utilization.
Which Region Holds the Largest Share of the Chip Scale Electronics Packaging Market?
- North America dominated the chip scale electronics packaging market with the largest revenue share of 35.4% in 2025, supported by the strong presence of leading semiconductor companies, advanced manufacturing capabilities, and increasing investments in domestic semiconductor production and packaging technologies
- The region also benefits from increasing investments in domestic semiconductor manufacturing, growing adoption of advanced packaging solutions, and strong demand from consumer electronics, automotive, telecommunications, and high-performance computing applications. Government initiatives supporting semiconductor production and the presence of established technology companies continue to strengthen North America’s leadership position in the global market.
U.S. Chip Scale Electronics Packaging Market Insight
The U.S. chip scale electronics packaging market is witnessing strong growth due to rising investments in advanced semiconductor packaging, domestic chip manufacturing, and next-generation electronics technologies. The country’s mature semiconductor ecosystem, along with increasing adoption of advanced packaging solutions for AI, IoT, automotive, and telecommunications applications, is driving market demand. In addition, government initiatives supporting domestic semiconductor production and the expansion of packaging and testing capabilities are accelerating the adoption of chip scale packaging technologies across the U.S.
Asia-Pacific Chip Scale Electronics Packaging Market Insight
The Asia-Pacific chip scale electronics packaging market is expected to witness rapid growth, driven by the strong presence of semiconductor manufacturers, expanding electronics production, and rising investments in advanced packaging infrastructure across countries such as China, Japan, and South Korea. Growing demand for compact and high-performance electronic devices, increasing adoption of advanced packaging technologies, and government support for semiconductor manufacturing are supporting regional market expansion. In addition, the growing presence of major semiconductor and packaging companies is accelerating chip scale packaging adoption across consumer electronics, automotive, telecommunications, and other applications.
Japan Chip Scale Electronics Packaging Market Insight
The Japan chip scale electronics packaging market is witnessing consistent growth due to rising investments in semiconductor manufacturing, advanced packaging technologies, and high-performance electronic components. Semiconductor manufacturers, electronics companies, and technology suppliers are increasingly adopting chip scale packaging solutions to support miniaturization, improved performance, and efficient device integration. Moreover, Japan’s established semiconductor materials and equipment ecosystem, along with growing demand for advanced electronic devices, is further contributing to market growth.
China Chip Scale Electronics Packaging Market Insight
The China chip scale electronics packaging market is growing rapidly, driven by expanding semiconductor manufacturing capabilities, increasing electronics production, and strong demand for compact and high-performance electronic devices. Growing investments in domestic semiconductor infrastructure and advanced packaging technologies are significantly boosting market demand across consumer electronics, automotive, telecommunications, and other applications. In addition, government support for semiconductor self-sufficiency and the increasing presence of domestic packaging manufacturers are positioning China as a major growth market for chip scale electronics packaging.
U.K. Chip Scale Electronics Packaging Market Insight
The U.K. chip scale electronics packaging market is experiencing steady growth, supported by increasing investments in semiconductor technologies, advanced electronic systems, and high-value applications. Growing demand for compact and reliable packaging solutions across automotive, telecommunications, aerospace, and consumer electronics applications is contributing to market development. Furthermore, increasing efforts to strengthen domestic semiconductor capabilities and improve supply-chain resilience are supporting the adoption of advanced chip packaging technologies in the U.K.
Germany Chip Scale Electronics Packaging Market Insight
The Germany chip scale electronics packaging market is expanding steadily due to the country’s strong automotive manufacturing base, advanced semiconductor ecosystem, and increasing demand for high-performance electronic components. Automotive manufacturers, semiconductor companies, and technology suppliers are increasingly utilizing advanced packaging solutions to support vehicle electronics, industrial systems, and next-generation mobility applications. Continuous investments in semiconductor manufacturing, advanced packaging capabilities, and automotive electronics, along with Germany’s strong research and engineering infrastructure, are further driving market growth.
Which are the Top Companies in Chip Scale Electronics Packaging Market?
The chip scale electronics packaging industry is primarily led by well-established companies, including:
- Amkor Technology, Inc. (U.S.)
- Intel Corporation (U.S.)
- Taiwan Semiconductor Manufacturing Company Limited (Taiwan)
- ASE Technology Holding Co., Ltd. (Taiwan)
- Jiangsu Changjiang Electronics Technology Co., Ltd. (China)
- TongFu Microelectronics Co., Ltd. (China)
- Powertech Technology Inc. (Taiwan)
- King Yuan ELECTRONICS CO., LTD. (Taiwan)
- ChipMOS TECHNOLOGIES INC. (Taiwan)
- Unisem (M) Berhad (Malaysia)
- UTAC Holdings Ltd (Singapore)
- Siliconware Precision Industries Co., Ltd. (Taiwan)
- NEPES Corporation (South Korea)
- Samsung Electronics Co., Ltd. (South Korea)
- SK HYNIX INC. (South Korea)
- JCET Group Co., Ltd. (China)
- Tianshui Huatian Technology Co., Ltd. (China)
- Hana Micron Inc. (South Korea)
- Chipbond Technology Corporation (Taiwan)
- Carsem (M) Sdn. Bhd. (Malaysia)
What are Latest Developments in Chip Scale Electronics Packaging Market?
- In May 2025, Advanced Semiconductor Engineering, Inc. (ASE) announced its FOCoS-Bridge with Through Silicon Via (TSV) packaging technology, designed to support next-generation AI and high-performance computing applications. The technology uses TSV to create shorter signal paths, enabling higher I/O density, improved thermal dissipation, and greater energy efficiency. The development strengthens ASE’s advanced fan-out packaging portfolio for chiplet and high-bandwidth memory integration.
- In October 2024, Amkor Technology and TSMC announced a memorandum of understanding to collaborate on advanced packaging and testing capabilities in Arizona. The partnership will utilize technologies including TSMC’s Integrated Fan-Out (InFO) and Chip on Wafer on Substrate (CoWoS) to support high-performance computing, communications, and other advanced semiconductor applications. The collaboration is expected to strengthen the U.S. semiconductor packaging ecosystem and provide customers with a more integrated manufacturing solution.
- In May 2023, TSMC showcased new developments in its 3DFabric advanced packaging platform, including an expanded CoWoS solution designed to accommodate more processors and high-bandwidth memory within a single package. TSMC also introduced SoIC-P microbump technology for three-dimensional chip stacking and an updated 3Dblox design language to simplify complex 3D IC designs. These developments highlight the growing role of advanced packaging in high-performance computing and AI applications.
- In October 2022, ASE announced advancements to its Fan-Out Chip on Substrate (FOCoS) packaging technology under the VIPack platform, introducing FOCoS-CF and FOCoS-CL solutions for high-performance computing applications. The development enables multi-chip and chiplet integration while improving electrical performance and board-level reliability, addressing growing requirements for high-density, high-speed, and low-latency interconnects in networking and artificial intelligence applications.
- In June 2022, ASE introduced VIPack, an advanced packaging platform designed to enable vertically integrated package solutions. The platform combines high-density redistribution-layer fan-out technologies, fan-out chip-on-substrate, fan-out bridge, system-in-package, and TSV-based 2.5D and 3D IC technologies. The launch was aimed at addressing growing requirements for higher performance, functionality, power efficiency, and multi-chip integration across AI, 5G, HPC, IoT, and automotive applications.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Chip Scale Electronics Packaging Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Chip Scale Electronics Packaging Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Chip Scale Electronics Packaging Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.