What is the Coated and Encapsulated Fertilizers Market Size and Growth Rate?
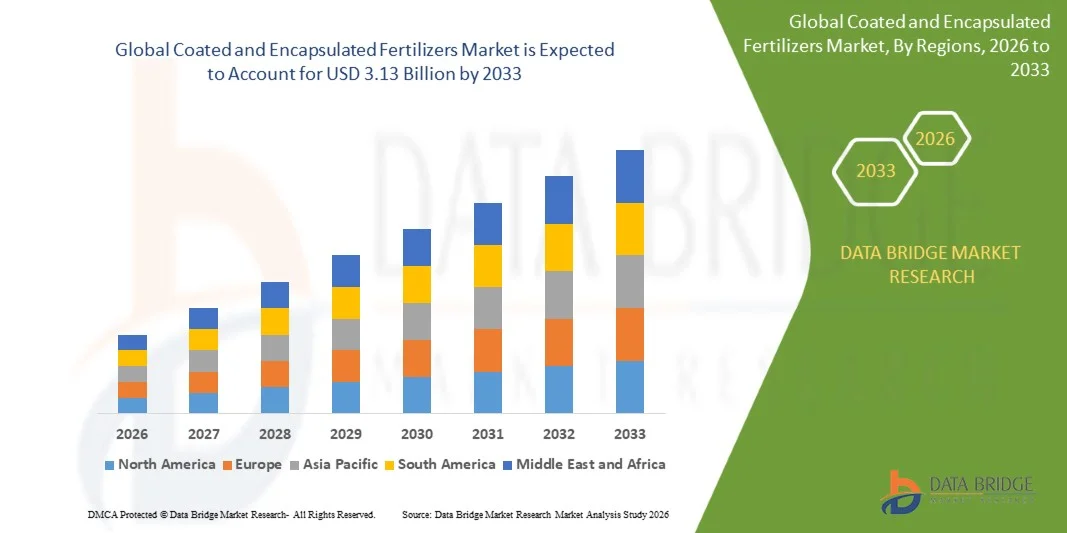
- As per Data Bridge Market Research analysis, the coated and encapsulated fertilizers market was valued at USD 1.95 billion in 2025 and is projected to reach USD 3.13 billion by 2033, growing at a CAGR of 6.10% from 2026 to 2033.
- The market is experiencing consistent growth driven by increasing demand for nutrient-use efficiency, growing adoption of controlled-release fertilizer technologies, rising focus on reducing nutrient losses, and the need to improve crop productivity while optimizing fertilizer application.
- The increasing emphasis on sustainable agriculture, combined with concerns regarding nitrogen losses through leaching, volatilization, and runoff, is encouraging fertilizer manufacturers and agricultural producers to adopt coated and encapsulated fertilizer products. These technologies regulate nutrient release according to crop requirements, improve nutrient-use efficiency, reduce the frequency of fertilizer applications, and support more efficient nutrient management across agricultural applications.
Market Size & Forecast
- Global Market Value (2025): USD 1.95 Billion
- Expected Market Value (2033): USD 3.13 Billion
- Forecast CAGR (2026–2033): 6.10%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Coated and Encapsulated Fertilizers Market?
- North America dominated the coated and encapsulated fertilizers market, supported by established precision agriculture practices, strong adoption of controlled-release fertilizer technologies, and increasing focus on nutrient-use efficiency. North America accounted for 35.7% of the broader controlled-release fertilizers market in 2025, according to IMARC.
- Asia-Pacific is expected to be the fastest-growing region for controlled-release fertilizer technologies, registering a CAGR of 6.4%, driven by rising food demand, government support for sustainable fertilizers, expansion of high-value crops, advancements in coating technologies, and increasing adoption of precision nutrient-management practices.
- The agricultural segment dominated the coated and encapsulated fertilizers market, accounting for 63% of the market share, driven by increasing use across large-scale farms, commercial agriculture, and specialty crops requiring controlled nutrient delivery.
- The non-agricultural segment is expected to register the fastest growth during the forecast period, supported by increasing use of coated and encapsulated fertilizers in turf management, landscaping, nurseries, ornamental horticulture, and home gardening applications.
- The coated and encapsulated fertilizers segment accounted for 41.3% of the broader controlled-release fertilizers market in 2026, making it the largest type segment. Its leading position is supported by controlled nutrient release, improved nutrient-use efficiency, and reduced nutrient losses through leaching and volatilization.
- Time-release systems represented the largest function segment in the broader controlled-release fertilizers market, accounting for 40.1% in 2026, as these systems provide nutrients progressively over an extended period and reduce the frequency of fertilizer applications.
- Advanced polymer/resin-coated fertilizers accounted for 48.3% of the product-tier segment in 2026, supported by their ability to provide greater control over nutrient-release patterns and their adoption across multiple crop types and agricultural applications.
Report Scope and Coated and Encapsulated Fertilizers Market Segmentation
|
Attributes |
Coated and Encapsulated Fertilizers Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include import export analysis, production capacity overview, production consumption analysis, price trend analysis, climate change scenario, supply chain analysis, value chain analysis, raw material/consumables overview, vendor selection criteria, PESTLE Analysis, Porter Analysis, and regulatory framework. |
What is the Key Trend in the Coated and Encapsulated Fertilizers Market?
- Fertilizer manufacturers and researchers are increasingly developing advanced coated and encapsulated fertilizer systems that regulate nutrient release according to crop requirements, supporting improved nutrient-use efficiency and reducing nutrient losses through leaching and volatilization.
- For instance, in May 2025, research published in ACS Sustainable Chemistry & Engineering demonstrated biodegradable shellac coatings applied to urea fertilizer granules to create controlled-release fertilizers with tunable nutrient-release properties, supporting the development of sustainable coating technologies.
- Controlled nutrient release enables fertilizers to provide nutrients progressively over extended periods, helping synchronize nutrient availability with crop demand and reducing the frequency of fertilizer applications.
- For instance, in August 2025, research published in Chemical Engineering Journal Advances developed a nano-biochar dispersed PVA/PVP matrix-encapsulated slow-release fertilizer that provided controlled nitrogen release over 60 days and reduced nutrient leaching compared with commercial fertilizers.
- Fertilizer producers and researchers are also developing biodegradable and bio-based coating materials to address environmental concerns associated with persistent synthetic polymer residues while maintaining controlled nutrient-release performance.
- For instance, in June 2025, research published in ACS Applied Polymer Materials developed a castor-based biopolyurethane coating modified with ZIF-8 for controlled-release fertilizer, extending the controlled-release period to 112 days and supporting more precise nutrient delivery.
- As agriculture increasingly emphasizes precision nutrient management, sustainable fertilizer use, and improved nutrient-use efficiency, the development of coated and encapsulated fertilizers with advanced polymer, resin, sulfur, and bio-based coatings is expected to continue, supporting more controlled nutrient delivery across agricultural and non-agricultural applications.
What are the Key Drivers of the Coated and Encapsulated Fertilizers Market?
- The increasing focus on nutrient-use efficiency, precision nutrient management, and reduction of nutrient losses is increasing demand for coated and encapsulated fertilizers that synchronize nutrient release with crop requirements.
- For instance, in August 2025, research published in Chemical Engineering Journal Advances demonstrated that a nano-biochar-based encapsulated slow-release fertilizer provided controlled nitrogen release over 60 days and reduced leaching compared with commercial fertilizers.
- Fertilizer manufacturers and researchers are developing polymer-coated, bio-based, and encapsulated formulations to provide more consistent nutrient availability and extend nutrient-release periods.
- For instance, in May 2025, research published in ACS Sustainable Chemistry & Engineering developed biodegradable shellac-coated urea fertilizers with tunable controlled-release properties, demonstrating the continued development of sustainable coating materials.
- With agricultural production increasingly emphasizing sustainable inputs, precision nutrient management, and improved fertilizer efficiency, coated and encapsulated fertilizers are gaining relevance as technologies for controlled nutrient delivery and reduction of nutrient losses.
Which Factors are Challenging the Growth of the Coated and Encapsulated Fertilizers Market?
- Coated and encapsulated fertilizers introduce technical and economic challenges related to coating durability, nutrient-release consistency, production complexity, environmental conditions, and higher manufacturing costs compared with conventional fertilizers.
- For instance, in October 2025, a review published in Industrial Crops and Products identified higher production costs, insufficient synchronization with plant nutrient uptake, stability requirements, and environmental implications of synthetic polymer-based fertilizers as key barriers to wider controlled-release fertilizer adoption.
- These technical requirements can increase production complexity because manufacturers must control coating thickness, polymer-to-fertilizer ratios, coating uniformity, and nutrient-release characteristics across fertilizer granules.
- For instance, a 2025 review of coated urea fertilizers identified coating uniformity and the optimization of coating processes, including fluidized-bed technologies, as important considerations for achieving consistent nutrient-release performance at larger production scales.
- The use of conventional synthetic polymer coatings also creates environmental concerns because some coating materials can persist in soil after nutrient release, increasing concerns regarding polymer residues and microplastic accumulation.
- For instance, in March 2025, research published in the Journal of Hazardous Materials demonstrated that polymer-coated controlled-release fertilizers can generate microplastics through osmotic pressure, wet-dry cycles, soil abrasion, surface wear, and compression forces.
- These production, performance, cost, and environmental requirements continue to create barriers to widespread adoption, as manufacturers must develop coating technologies that provide predictable nutrient release, adequate durability, competitive costs, and improved biodegradability across diverse soil and climatic conditions.
How is the Coated and Encapsulated Fertilizers Market Segmented?
The coated and encapsulated fertilizers market is segmented on the basis of type, end use, mode of application, nutrient type, and coating material.
- By Type
On the basis of type, the coated and encapsulated fertilizers market is segmented into slow-release fertilizers and nitrogen stabilizers (N-stabilizers). The slow-release fertilizers segment dominated the market with a 63.0% share in 2025, supported by its ability to regulate nutrient release according to crop requirements and improve nutrient-use efficiency. Slow-release formulations can reduce nutrient losses through leaching, volatilization, and runoff while reducing the frequency of fertilizer applications. Advances in polymer, resin, and sulfur coating technologies are improving nutrient-release consistency. Increasing adoption of precision nutrient-management practices is supporting demand for slow-release fertilizer technologies.
The nitrogen stabilizers segment is projected to register the fastest growth at a CAGR of 6.8% from 2026 to 2033, driven by increasing emphasis on nitrogen-use efficiency and reduction of nitrogen losses. Nitrification inhibitors and urease inhibitors can slow nitrogen transformation and reduce losses from agricultural soils. Increasing concerns regarding nitrogen runoff, volatilization, and greenhouse gas emissions are supporting adoption of nitrogen-management technologies. Manufacturers are developing stabilized fertilizer formulations to improve nitrogen availability to crops. Growing emphasis on sustainable nutrient management is expected to support the segment during the forecast period.
- By End Use
On the basis of end use, the coated and encapsulated fertilizers market is segmented into agricultural and non-agricultural. The agricultural segment dominated the market with a 63.0% share in 2025, supported by extensive use across field crops, horticultural crops, specialty crops, and commercial farming operations. Controlled-release fertilizers provide nutrients progressively during crop growth and can reduce fertilizer application frequency. Their use is particularly relevant in intensive agricultural systems where nutrient-use efficiency is an important consideration. Increasing food production requirements are encouraging growers to improve fertilizer utilization. Adoption of precision agriculture practices is also supporting demand for controlled nutrient delivery.
The non-agricultural segment is projected to register the fastest growth at a CAGR of 6.2% from 2026 to 2033, driven by increasing use in turf management, landscaping, nurseries, ornamental horticulture, and home gardening. Coated fertilizers provide extended nutrient availability while reducing the frequency of applications in managed landscapes. Growing investment in landscaping and recreational turf is creating additional opportunities. Increasing demand for efficient nutrient-management solutions in non-crop applications is supporting segment growth. These applications are expected to expand as demand for low-maintenance and efficient fertilization solutions increases.
- By Mode of Application
On the basis of mode of application, the coated and encapsulated fertilizers market is segmented into fertigation, foliar, soil, and other modes of application. The soil segment dominated the market with a 38.0% share in 2025, supported by the widespread use of coated fertilizer granules directly in agricultural soils. Soil-applied coated fertilizers can release nutrients gradually according to environmental conditions and crop requirements. The application method is compatible with conventional fertilizer-spreading practices and precision agriculture equipment. Farmers can reduce fertilizer application frequency through extended-release formulations. Increasing adoption of controlled-release granular fertilizers is supporting demand for soil application.
The fertigation segment is projected to register the fastest growth at a CAGR of 7.4% from 2026 to 2033, driven by increasing adoption of irrigation-based nutrient management and precision agriculture. Fertigation enables nutrients to be delivered together with irrigation water, supporting targeted nutrient distribution. Controlled-release formulations can complement fertigation strategies by improving nutrient availability throughout the crop cycle. Increasing use of drip and sprinkler irrigation is creating additional opportunities for efficient nutrient delivery. Growing emphasis on water and fertilizer-use efficiency is expected to support adoption of fertigation.
- By Nutrient Type
On the basis of nutrient type, the coated and encapsulated fertilizers market is segmented into nitrogen, phosphorus, potassium, and other nutrients. The nitrogen segment dominated the market with a 55.0% share in 2025, supported by extensive use of nitrogen fertilizers across agricultural production. Nitrogen is essential for vegetative growth, crop development, and yield formation. Coating and encapsulation technologies help control nitrogen release and reduce losses caused by volatilization, leaching, and runoff. Urea is widely used as a base material for controlled-release nitrogen fertilizer formulations. Increasing focus on nitrogen-use efficiency is supporting demand for coated and encapsulated nitrogen fertilizers.
The phosphorus segment is projected to register the fastest growth at a CAGR of 6.6% from 2026 to 2033, supported by increasing efforts to improve phosphorus-use efficiency and reduce nutrient losses. Controlled-release phosphorus formulations can provide nutrients progressively and improve nutrient availability to crops. Researchers and manufacturers are developing coating systems that regulate phosphorus dissolution and release. Increasing concerns regarding phosphorus runoff and water-quality impacts are encouraging more efficient phosphorus management. Adoption of precision nutrient-management practices is expected to create additional demand for controlled-release phosphorus fertilizers.
- By Coating Material
On the basis of coating material, the coated and encapsulated fertilizers market is segmented into polymer coatings, sulfur coatings, resin coatings, and other coating materials. The polymer coatings segment dominated the market with a 69.6% share in 2025, supported by its ability to provide controlled and predictable nutrient-release characteristics. Polymer coatings can be engineered to regulate nutrient release according to coating thickness, material properties, soil temperature, and moisture conditions. Manufacturers are developing advanced polymer systems to improve coating uniformity and release performance. Increasing demand for precision nutrient delivery is supporting adoption of polymer-coated fertilizers.
The polymer-sulfur-coated segment is projected to register the fastest growth at a CAGR of 8.2% from 2026 to 2033, driven by demand for controlled nitrogen release and sulfur supplementation. Polymer-sulfur coatings can provide controlled nutrient release while supplying sulfur to crops. Advances in coating technologies are improving nutrient-delivery consistency. Increasing demand for efficient fertilizer technologies and improved nutrient-use efficiency is expected to support growth of polymer-sulfur-coated products.
Which Region Holds the Largest Share of the Coated and Encapsulated Fertilizers Market?
- North America dominated the coated and encapsulated fertilizers market with the largest revenue share of 35.7% in 2025, supported by strong adoption of controlled-release fertilizers, precision agriculture practices, high-value crop production, and increasing emphasis on nutrient-use efficiency.
- The region also benefits from established agricultural infrastructure, widespread adoption of polymer-coated fertilizer technologies, and increasing demand for products that reduce nutrient losses and application frequency. Polymer-coated formulations accounted for a substantial share of the North American controlled-release fertilizer market in 2025, reflecting their established use across row crops, horticulture, and managed turf.
U.S. Coated and Encapsulated Fertilizers Market Insight
The U.S. coated and encapsulated fertilizers market is witnessing strong growth due to increasing adoption of precision agriculture, efficient nutrient-management practices, and controlled-release fertilizer technologies. Growing demand for polymer-coated fertilizers across field crops, turf, horticulture, and specialty crop applications is supporting market expansion. In addition, increasing emphasis on reducing nutrient losses, improving fertilizer-use efficiency, and optimizing fertilizer application is accelerating interest in coated and encapsulated fertilizer solutions across the country.
Asia-Pacific Automotive In-Wheel Motors Market Insight
The Asia-Pacific coated and encapsulated fertilizers market is expected to witness rapid growth, driven by rising food demand, expanding agricultural production, increasing adoption of precision farming, and growing emphasis on efficient nutrient management across countries such as China, India, and Japan. Increasing adoption of polymer-coated and controlled-release fertilizers, together with expanding horticultural production and investments in advanced fertilizer technologies, is supporting regional market expansion. The presence of large agricultural markets and growing efforts to improve fertilizer-use efficiency are further creating opportunities for coated and encapsulated fertilizer technologies.
Japan Automotive In-Wheel Motors Market Insight
The Japan coated and encapsulated fertilizers market is witnessing consistent growth due to advanced agricultural technologies, high-value horticultural production, and increasing emphasis on efficient nutrient management. Controlled-release fertilizer technologies are relevant to Japan's intensive agricultural and horticultural systems, where precise nutrient delivery can support crop productivity and reduce fertilizer losses. Increasing development and adoption of advanced coating technologies are supporting market opportunities. Japan's established agricultural infrastructure and focus on smart farming practices are further supporting demand for coated and encapsulated fertilizer solutions.
China Automotive In-Wheel Motors Market Insight
The China coated and encapsulated fertilizers market is growing steadily, driven by expanding agricultural production, increasing adoption of precision farming, and growing emphasis on improving fertilizer-use efficiency. Growing use of controlled-release and coated fertilizers across field crops and horticultural applications is supporting market demand. In addition, China's large agricultural base, expanding fertilizer production capabilities, and increasing focus on reducing nutrient losses are strengthening adoption of coated and encapsulated fertilizer technologies.
U.K. Automotive In-Wheel Motors Market Insight
The U.K. coated and encapsulated fertilizers market is experiencing steady development, supported by increasing emphasis on sustainable agriculture, nutrient-use efficiency, and reduction of nutrient losses. Controlled-release and coated fertilizer technologies provide opportunities to improve nutrient availability while reducing fertilizer application frequency. Increasing attention to environmentally responsible fertilizer formulations is also supporting the development of advanced coating materials. Furthermore, the focus on sustainable agricultural practices is encouraging the adoption of efficient nutrient-delivery technologies.
Germany Automotive In-Wheel Motors Market Insight
The Germany coated and encapsulated fertilizers market is expanding steadily due to the country's advanced agricultural sector, increasing focus on precision nutrient management, and growing demand for sustainable fertilizer technologies. Coated and controlled-release fertilizers can support efficient nutrient delivery while reducing nutrient losses from agricultural soils. Increasing development of biodegradable and environmentally compatible coating materials is creating additional opportunities across the German and broader European fertilizer industry. Moreover, the focus on sustainable fertilizer use and environmental protection is encouraging manufacturers to advance coating technologies for controlled nutrient release.
Which are the Top Companies in Coated and Encapsulated Fertilizers Market?
The coated and encapsulated fertilizers industry is primarily led by well-established companies, including:
- ICL Group Ltd. (Israel)
- Kingenta Ecological Engineering Group Co., Ltd. (China)
- Haifa Group (Israel)
- Yara International ASA (Norway)
- Nutrien Ltd. (Canada)
- The Mosaic Company (U.S.)
- EuroChem Group AG (Switzerland)
- Koch Industries, Inc. (U.S.)
- OCI Global (Netherlands)
- CF Industries Holdings, Inc. (U.S.)
- Compo Expert GmbH (Germany)
- SQM S.A. (Chile)
- Israel Chemicals Ltd. (Israel)
- E. I. du Pont de Nemours and Company (U.S.)
- Smart Fertilizer Management Ltd. (Israel)
- Florikan ESA LLC (U.S.)
- Harrell's LLC (U.S.)
- Pursell Agri-Tech, LLC (U.S.)
- Knox Fertilizer Company, Inc. (U.S.)
- J.R. Simplot Company (U.S.)
What are Latest Developments in Coated and Encapsulated Fertilizers Market?
- In March 2025, Haifa Group announced a USD 34.45million investment in a new Multicote production plant in southern France. The facility is being developed to produce controlled-release fertilizers using a newly developed biodegradable coating. The company stated that the coating was designed to maintain nutrient-release performance while addressing environmental requirements related to fertilizer coating materials. The development highlights the industry's shift toward biodegradable coating technologies for controlled-release fertilizers.
- In May 2025, research published in ACS Sustainable Chemistry & Engineering demonstrated the use of biodegradable shellac coatings on urea fertilizer granules to develop controlled-release fertilizers with tunable nutrient-release properties. The research investigated shellac as a biodegradable coating material and demonstrated its potential for regulating nutrient release from urea granules. The development highlights continued research into bio-based coating materials for controlled-release fertilizer applications.
- In May 2025, research published in Science of the Total Environment introduced a screening approach for identifying biodegradable polymers suitable for fertilizer coatings. The study assessed commercially available biodegradable polymers based on technical performance and commercial viability and identified polycaprolactone, biodegradable polyurethane, and natural rubber as promising candidates for fertilizer coating applications. The research supports the development of more commercially viable biodegradable coating technologies.
- In March 2025, research published in Industrial Crops and Products developed a fully bio-based polyurethane coating for controlled-release fertilizers using materials derived primarily from castor oil and lysine. The study evaluated the coating's nutrient-release characteristics and biodegradation behavior in soil, highlighting the potential of bio-based polyurethane systems as alternatives to conventional fertilizer coatings.
- In August 2025, research published in Chemical Engineering Journal Advances demonstrated a nano-biochar dispersed PVA/PVP matrix encapsulated slow-release fertilizer. The formulation was designed to regulate nitrogen release from urea and demonstrated controlled nitrogen release together with reduced nutrient leaching compared with commercial fertilizers in soil testing. The development highlights the growing use of encapsulation and bio-based materials for precision nutrient delivery.
- In November 2023, Nutrien and CoteX Technologies announced a memorandum of understanding to explore commercialization of a biodegradable controlled-release fertilizer coating for large-acreage crops in North America. The coating technology was designed to enable gradual nutrient release while reducing environmental impacts associated with conventional fertilizer coatings. The collaboration highlighted increasing industry interest in commercially scalable and environmentally compatible fertilizer coating technologies.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.