What is the Computer Vision AI Camera Market Size and Growth Rate?
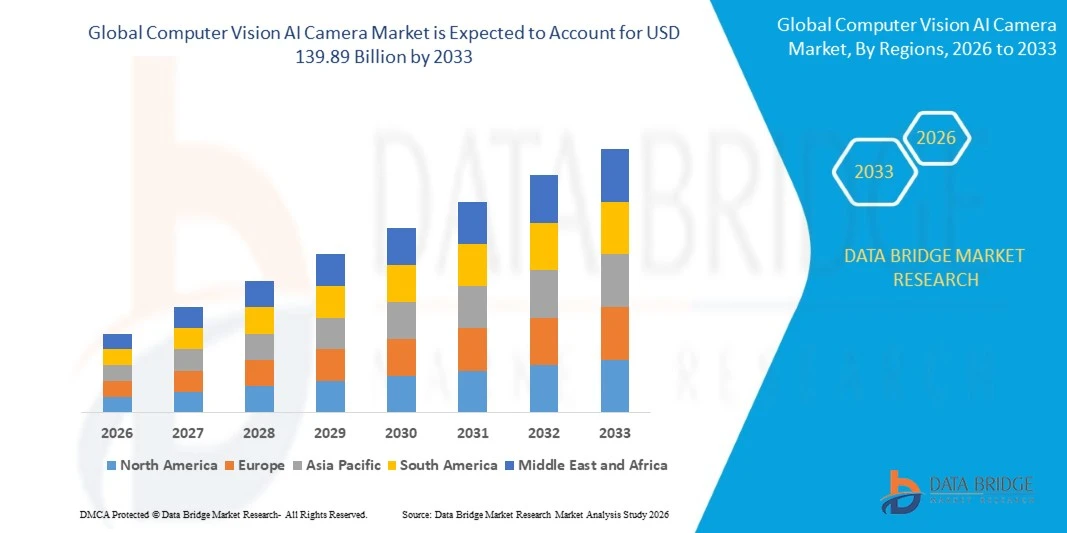
- As per Data Bridge Market Research analysis, the computer vision AI camera market was valued at USD 26.02 billion in 2025 and is projected to reach USD 139.89 billion by 2033, growing at a CAGR of 23.40% from 2026 to 2033.
- The market is experiencing rapid growth driven by rising demand for intelligent video analytics, increasing deployment of edge AI processors, and expanding applications across public safety, retail, manufacturing, transportation, healthcare, and smart city sectors.
- The increasing shift from passive video recording toward real-time detection, classification, and automated response, combined with growing integration of AI cameras with cloud platforms, video management systems, and robotic and industrial equipment, is supporting market adoption. Computer vision technology is being applied across surveillance and security, edge AI processing, industrial inspection, traffic management, and retail analytics, offering users greater situational awareness and faster decisions from video surveillance data.
Market Size & Forecast
- Global Market Value (2025): USD 26.02 Billion
- Expected Market Value (2033): USD 139.89 Billion
- Forecast CAGR (2026–2033): 23.40%
What are the Major Takeaways of the Computer Vision AI Camera Market?
- Asia-Pacific dominated the computer vision AI camera market with the largest revenue share of 39.84% in 2025, supported by large-scale electronics manufacturing, extensive video surveillance deployments, and strong adoption of AI-enabled cameras across smart city and industrial applications.
- Middle East and Africa is expected to be the fastest-growing region at a CAGR of 26.45% from 2026 to 2033, fueled by smart city programs, large infrastructure projects, and rising investments in public safety and security.
- The standalone AI cameras segment led the market with a 63.28% share in 2025, driven by large-scale deployments of AI-enabled security, traffic, and retail cameras.
- Embedded AI camera modules are the fastest-growing product type, projected to register a CAGR of 26.37%, reflecting the surge in demand for compact vision modules in robots, drones, vehicles, and industrial equipment.
- The edge-based segment dominated the processing mode category with a 52.46% revenue share in 2025, led by demand for low-latency analytics, bandwidth savings, and data privacy.
- Surveillance & security accounted for 44.13% of the market share in 2025, preferred by increasing requirements for automated threat detection, perimeter protection, and real-time alerts.
- The industrial inspection & quality control segment is the fastest-growing application category, with a CAGR of 26.02%, driven by increasing automation of defect detection, process monitoring, and workplace safety.
Report Scope and Computer Vision AI Camera Market Segmentation
|
Attributes |
Computer Vision AI Camera Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, geographically represented company-wise production and capacity, network layouts of distributors and partners, detailed and updated price trend analysis and deficit analysis of supply chain and demand. |
What is the Key Trend in the Computer Vision AI Camera Market?
- Computer vision AI cameras are increasingly evolving from simple video-capture devices into intelligent edge perception platforms, combining image sensors, dedicated AI accelerators, and vision-language models to detect, classify, and interpret events directly on the device.
- For instance, in May 2025, according to Ambarella’s fiscal first-quarter 2026 earnings call, the company said its third-generation AI accelerator supports leading generative AI models from 500 million to 34 billion parameters, and announced development of a new edge AI infrastructure SoC family to aggregate multiple camera endpoints, highlighting the shift toward generative AI at the edge.
- On-device analytics is reducing dependence on continuous cloud connectivity and central servers, lowering latency and bandwidth requirements while improving data privacy for security, industrial, and retail deployments.
- Camera platforms are also being designed as scalable fleets, where silicon, software, and fleet management tools work together so that AI features can be developed once and deployed across entire product portfolios.
- For instance, in March 2026, according to Qualcomm Technologies, the company presented its AI camera platform at ISC West 2026, combining AI-enhanced image processing such as color night vision at 4K and 30 frames per second, vision transformer and language model support on select platforms, and the Qualcomm Insight Platform for generative AI-native video security.
- As edge AI processors, multimodal models, 3D sensing, and fleet-management software continue to advance, computer vision AI cameras are expected to expand beyond security into robotics, industrial automation, retail analytics, and intelligent human–machine interaction.
What are the Key Drivers of the Computer Vision AI Camera Market?
- Rising security, safety, and automation requirements across cities, factories, retail stores, and transport networks are increasing demand for cameras that can analyze video automatically rather than simply record it.
- For instance, in February 2026, according to Hanwha Vision’s 2025 results, AI cameras accounted for 49% of its network camera sales in the fourth quarter of 2025, up 14 percentage points from a year earlier, while its security business revenue grew 10% and operating profit rose 52%.
- Falling costs and rising performance of edge AI processors are enabling manufacturers to embed deep learning into mainstream camera models, expanding adoption from premium installations to entry-level and mid-range products.
- For instance, in July 2025, according to Hikvision, its DeepinViewX-Series bullet cameras, powered by Guanlan large-scale AI models, were reported to deliver 90% fewer false alarms and 50% fewer repeated alarms than traditional AI cameras, with up to 140 meters of daytime detection range, supporting adoption in perimeter protection.
- With organizations increasingly seeking automated detection, real-time alerts, and lower operating costs, computer vision AI cameras can support faster incident response, improved operational visibility, and integration with video management and enterprise software platforms.
What Factors Are Challenging the Growth of the Computer Vision AI Camera Market?
- Computer vision AI cameras require the integration of image sensors, AI accelerators, memory, connectivity, cybersecurity, and trained models, increasing device complexity and engineering cost compared with conventional network cameras.
- For instance, in February 2025, according to the European Commission, the prohibitions under the EU AI Act began to apply from 2 February 2025, restricting real-time remote biometric identification in publicly accessible spaces for law enforcement to narrow exceptions, while guidelines on prohibited practices followed on 4 February 2025, adding compliance considerations for camera analytics.
- These hardware, regulatory, and data-governance requirements can increase development timelines and create challenges related to privacy, model accuracy across lighting and weather conditions, bias, and consistent performance across diverse deployment environments.
- The need for secure firmware, encrypted communications, and regular updates also creates technical challenges, since connected AI cameras are exposed to cyber threats and must meet varying data-protection requirements across regions.
- For instance, in January 2025, according to Hanwha Vision, its European cybersecurity research found a worrying gap between users’ perception that their video systems are protected against cyberattacks and their failure to implement simple measures to keep them secure, highlighting security risks that can constrain adoption of connected AI cameras.
- The combination of higher hardware complexity, regulatory scrutiny, cybersecurity exposure, and the need for reliable recognition performance can constrain adoption among cost-sensitive users and public-sector buyers, particularly where conventional cameras and manual monitoring already satisfy basic surveillance requirements.
How is the Computer Vision AI Camera Market Segmented?
The computer vision AI camera market is segmented on the basis of product, processing mode, application, and end user.
- By Product
On the basis of product, the computer vision AI camera market is segmented into standalone AI cameras and embedded AI camera modules. The standalone AI cameras segment dominated the market with 63.28% share in 2025, supported by large-scale deployments in security, traffic, retail, and industrial facilities. These cameras integrate image sensors, processors, and analytics in a single device, reducing the need for separate servers. They are increasingly used for object detection, license plate recognition, people counting, and behavior analysis. Improvements in edge AI chipsets, low-light imaging, and cybersecurity features are strengthening demand. Compatibility with video management systems also supports upgrades of existing installations.
The embedded AI camera modules segment is projected to register the fastest growth at a CAGR of 26.37% from 2026 to 2033, driven by increasing demand for compact vision modules in robots, drones, vehicles, smart appliances, and industrial equipment. Modules enable device makers to add perception capabilities without designing complete camera systems. Depth sensing, global shutter sensors, and low-power AI processors are expanding use cases in robotics and automation. Standard interfaces and software development kits shorten development cycles. Growth of physical AI and autonomous machines is further increasing demand for tightly integrated vision hardware and software.
- By Processing Mode
On the basis of processing mode, the computer vision AI camera market is segmented into edge-based, cloud-based, and hybrid. The edge-based segment dominated the market with 52.46% share in 2025, supported by demand for low-latency analytics, reduced bandwidth consumption, and stronger data privacy. Running AI models directly on the camera allows events to be detected and alarms to be triggered without relying on network or remote server resources. Dedicated neural processing units are making on-device inference more efficient and affordable. Edge processing also supports deployments in locations with limited connectivity. Vendors are increasingly offering open application platforms for third-party analytics.
The hybrid segment is projected to register the fastest growth at a CAGR of 25.81% from 2026 to 2033, driven by increasing demand for architectures that combine on-camera detection with cloud-based search, training, and fleet management. Organizations can run time-critical analytics locally while using the cloud for model updates, long-term storage, and cross-site analysis. Generative AI features such as natural-language video search often require more compute than a single camera provides. Edge servers and AI boxes can add intelligence to existing infrastructure without full camera replacement. Flexible deployment helps meet differing privacy and data-residency requirements.
- By Application
On the basis of application, the computer vision AI camera market is segmented into surveillance & security, industrial inspection & quality control, traffic management, and others. The surveillance & security segment dominated the application category with 44.13% share in 2025, supported by increasing requirements for automated threat detection, perimeter protection, and real-time alerting. AI cameras reduce false alarms by distinguishing people, vehicles, and objects of interest from environmental noise. They help operators monitor large numbers of cameras with fewer personnel. Forensic search and event classification shorten investigation times. Public-sector and commercial security programs continue to upgrade from conventional cameras to analytics-enabled devices.
The industrial inspection & quality control segment is projected to register the fastest growth at a CAGR of 26.02% from 2026 to 2033, driven by increasing automation of defect detection, process monitoring, and workplace safety compliance. AI cameras can inspect products at production-line speeds and flag anomalies that are difficult to detect manually. Integration with programmable controllers and manufacturing execution systems allows inspection results to trigger corrective actions. Deep learning models can be retrained for new products with limited data. Labor shortages and rising quality expectations are further supporting adoption in electronics, automotive, food, and logistics operations.
- By End User
On the basis of end user, the computer vision AI camera market is segmented into Government & Public Safety, Retail, Manufacturing, Transportation & Logistics, Healthcare, and Others. The government & public safety segment dominated the end-user category with 33.71% share in 2025, supported by large-scale investments in city surveillance, border security, critical infrastructure protection, and emergency response. AI cameras enable automated alerts, vehicle and object recognition, and crowd monitoring across wide areas. Integration with command-and-control centers improves response coordination. Regulatory frameworks governing biometric use and data protection remain important considerations for deployment, particularly in Europe and other privacy-sensitive jurisdictions.
The manufacturing segment is projected to register the fastest growth at CAGR of 25.64% from 2026 to 2033, driven by increasing adoption of machine vision for inspection, robot guidance, safety monitoring, and predictive maintenance. Factories are deploying AI cameras to monitor production lines, detect defects, verify assembly steps, and identify unsafe behavior. Embedded camera modules and 3D depth sensing are expanding applications in autonomous mobile robots and bin-picking systems. Edge analytics keeps sensitive production data on-site. Growing investment in smart-factory and physical AI initiatives is creating additional opportunities for connected vision solutions.
Which Region Holds the Largest Share of the Computer Vision AI Camera Market?
- Asia-Pacific dominated the computer vision AI camera market with the largest revenue share of 39.84% in 2025, supported by large-scale electronics manufacturing, extensive video surveillance deployments, and strong adoption of AI-enabled cameras across smart city and industrial applications.
- The region also benefits from the presence of leading camera and semiconductor manufacturers, supportive government programs for public safety and smart infrastructure, and rapidly growing demand from retail, transportation, and manufacturing sectors. Increasing use of AI cameras for traffic management, industrial inspection, and public security continues to strengthen Asia-Pacific’s position in the global market.
U.S. Computer Vision AI Camera Market Insight
The U.S. computer vision AI camera market is witnessing strong growth due to rising adoption of intelligent video analytics, edge AI processors, and cloud-connected security platforms across commercial, retail, transportation, and public safety applications. The country’s leading semiconductor and software ecosystem, along with increasing integration of AI cameras with video management systems and enterprise applications, is driving demand for advanced detection and analytics solutions. In addition, growing emphasis on loss prevention, workplace safety, smart infrastructure, and cybersecurity-compliant devices is accelerating adoption of AI cameras across professional and commercial environments.
Asia-Pacific Computer Vision AI Camera Market Insight
The Asia-Pacific computer vision AI camera market is expected to witness rapid growth, driven by large-scale smart city projects, expanding electronics manufacturing, and increasing investments in public safety and industrial automation across countries such as China, India, and Japan. Growing demand for intelligent traffic management, retail analytics, and factory inspection is supporting regional market expansion. In addition, the region’s strong camera and semiconductor manufacturing ecosystem and increasing adoption of AI-enabled devices across government, transportation, and enterprise applications are accelerating demand for computer vision AI cameras.
Japan Computer Vision AI Camera Market Insight
The Japan computer vision AI camera market is witnessing consistent growth due to rising investments in factory automation, robotics, and advanced image sensing technologies. Manufacturers, transportation operators, retailers, and infrastructure managers are increasingly adopting AI cameras for inspection, monitoring, and safety applications. Moreover, strong demand for precision, reliability, compact device design, and high image quality, supported by the country’s leadership in image sensors and optical components, is further contributing to market growth in Japan.
China Computer Vision AI Camera Market Insight
The China computer vision AI camera market is growing rapidly, driven by large-scale video surveillance infrastructure, extensive electronics manufacturing, and increasing adoption of AI-enabled cameras across public security, transportation, retail, and industrial applications. Growing use of large AI models and edge processors within camera products is significantly boosting market demand. In addition, strong domestic manufacturing capabilities, competitive pricing, and rapid adoption of smart city and smart factory programs are positioning China as a key growth market for computer vision AI camera solutions across Asia-Pacific.
U.K. Computer Vision AI Camera Market Insight
The U.K. computer vision AI camera market is experiencing steady growth, supported by increasing adoption of intelligent video analytics in transport hubs, retail, healthcare, and public spaces. Local authorities, enterprises, and infrastructure operators are increasingly utilizing AI cameras to improve incident detection, crowd management, and operational efficiency. Furthermore, growing integration of AI cameras with cloud platforms and video management software, together with attention to privacy and data-protection compliance, is supporting wider adoption of computer vision AI camera solutions in the U.K.
Germany Computer Vision AI Camera Market Insight
The Germany computer vision AI camera market is expanding steadily due to the country’s strong industrial base, advanced automation ecosystem, and increasing adoption of machine vision and intelligent security solutions. Manufacturing companies, automotive suppliers, logistics operators, and public institutions are increasingly utilizing AI cameras for quality inspection, safety monitoring, and process optimization. Continuous advancements in edge AI, industrial imaging, and connected devices, along with Germany’s focus on precision engineering and data protection, are further driving market growth in the country.
Which are the Top Companies in Computer Vision AI Camera Market?
The computer vision AI camera industry is primarily led by well-established companies, including:
- Hangzhou Hikvision Digital Technology Co., Ltd. (China)
- Zhejiang Dahua Technology Co., Ltd. (China)
- Axis Communications AB (Sweden)
- Hanwha Vision Co., Ltd. (South Korea)
- Sony Group Corporation (Japan)
- Ambarella, Inc. (U.S.)
- NVIDIA Corporation (U.S.)
- Qualcomm Incorporated (U.S.)
- Intel Corporation (U.S.)
- Google LLC (U.S.)
- Motorola Solutions, Inc. (U.S.)
- Honeywell International Inc. (U.S.)
- Robert Bosch GmbH (Germany)
- Panasonic Holdings Corporation (Japan)
- Cognex Corporation (U.S.)
- Teledyne Technologies Incorporated (U.S.)
- Basler AG (Germany)
- Huawei Technologies Co., Ltd. (China)
- Canon Inc. (Japan)
- e-con Systems (India)
What are Latest Developments in Computer Vision AI Camera Market?
- In December 2025, Axis Communications announced that it would present next-generation intelligent security technologies at Intersec Dubai 2026, including the AXIS Q6358-LE 4K PTZ camera built on the ARTPEC-9 platform, the AXIS Q3558-LVE 8MP outdoor camera, and the AXIS P3277-LVE dome camera, all featuring AI-powered analytics at the edge alongside built-in cybersecurity and forensic wide dynamic range imaging.
- In January 2026, Ambarella showcased its CV7 edge AI vision system-on-chip at CES 2026, positioned for security cameras, industrial automation hardware, robots, drones, and next-generation vehicles. The 8K-capable SoC joins the company’s CV72, CV75, and N1 families, targeting consumer and enterprise camera developers that need advanced video analytics, higher image quality, and stronger on-device AI performance.
- In February 2026, e-con Systems launched the DepthVista Helix 3D CW iToF camera, a depth camera engineered for reliable 3D perception in robotics and industrial automation. Target applications include autonomous mobile robots, pick-and-place, bin-picking, palletization and depalletization robots, and industrial safety systems, extending embedded vision modules into physical AI use cases beyond conventional security cameras.
- In March 2026, Qualcomm Technologies presented its AI camera platform strategy at ISC West 2026, built on silicon, software, and fleet operations. The platform includes AI-infused image signal processing with color night vision at 4K and 30 frames per second, vision transformer and language model support on select platforms, and the Qualcomm Insight Platform for generative AI-native video security.
- In May 2026, Hanwha and Ambarella signed a long-term agreement for sourcing and co-development of Ambarella edge AI technology across Hanwha’s video security, robotics, industrial automation, and life sciences products. The agreement is valued at more than USD 800 million in potential revenue over a period exceeding ten years, and Ambarella cited an installed base of over 46 million AI units.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Computer Vision Ai Artificial Intelligence Camera Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Computer Vision Ai Artificial Intelligence Camera Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Computer Vision Ai Artificial Intelligence Camera Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.