What is the Data Center Blade Market Size and Growth Rate?
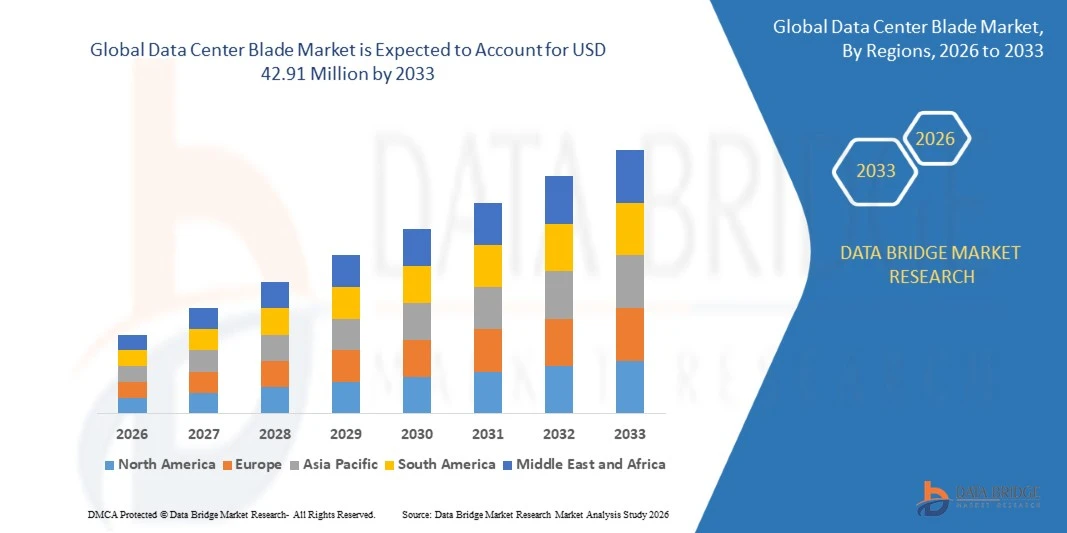
- As per Data Bridge Market Research analysis, the data center blade market was valued at USD 23.36 billion in 2025 and is projected to reach USD 42.91 billion by 2033, growing at a CAGR of 7.90% from 2026 to 2033.
- The market is experiencing consistent growth driven by rising demand for energy-efficient data center infrastructure, increasing adoption of cloud computing and virtualization, and expanding applications across artificial intelligence, high-performance computing, and enterprise IT infrastructure.
- The growing volume of data generated by digital services, combined with increasing demand for scalable computing infrastructure, is compelling enterprises, cloud service providers, and colocation operators to adopt advanced blade server solutions. Modular blade systems are gaining traction as organizations seek to optimize space utilization, simplify server management, and improve computing density while supporting evolving workloads associated with AI, big data analytics, and digital transformation.
Market Size & Forecast
- Global Market Value (2025): USD 23.36 Billion
- Expected Market Value (2033): USD 42.91 Billion
- Forecast CAGR (2026–2033): 7.90%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Data Center Blade Market?
- North America dominated the data center blade market with the largest revenue share of 38.5% in 2025, supported by advanced data center infrastructure, strong cloud computing adoption, and substantial investments in hyperscale facilities.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 9.2% from 2026 to 2033, fueled by rapid digitalization, expanding cloud infrastructure, and rising data center investments in China, India, and Japan.
- The Tier 3 segment led the market with a 42.5% share in 2025, driven by its balance between infrastructure reliability, operational efficiency, and investment requirements
- Tier 4 are the fastest-growing data center type, projected to register a CAGR of 9.1%, reflecting the surge in demand for fault-tolerant infrastructure and uninterrupted computing operations.
- The installation and support services segment dominated the service type category with a 43.8% revenue share in 2025, led by the technical requirements associated with blade server deployment, configuration, maintenance, and troubleshooting
- IT and telecom accounted for 36.7% of the market share in 2025, preferred by extensive investments in cloud computing, telecommunications infrastructure, and enterprise data processing.
- The healthcare segment is the fastest-growing vertical category, with a CAGR of 10.2%, driven by increasing digitalization of medical services and rising demand for secure data processing.
Report Scope and Data Center Blade Market Segmentation
|
Attributes |
Data Center Blade Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Data Center Blade Market?
- Data center operators are increasingly adopting high-density blade server systems to optimize rack space, improve computing efficiency, and support growing workloads associated with artificial intelligence, cloud computing, and virtualization.
- For instance, in December 2025, Supermicro announced its 6U SuperBlade system with direct liquid cooling and air-cooling options, delivering up to 50% space savings and 93% cable reduction compared with traditional 1U servers.
- Modular blade server architectures enable organizations to consolidate computing resources, simplify infrastructure management, and improve scalability as processing requirements increase.
- Cloud service providers and enterprise data centers are prioritizing advanced cooling technologies and power-efficient server designs to manage rising thermal demands from increasingly dense computing environments.
- For instance, in May 2025, Supermicro announced improvements to its Direct Liquid Cooling (DLC-2) technology, targeting up to 40% lower data center power consumption and up to 20% lower total cost of ownership compared with air-cooled installations.
- As AI adoption and cloud workloads continue to expand, demand for high-density server architectures, efficient cooling, and scalable computing platforms is expected to strengthen, reinforcing blade servers' role in modern data center infrastructure.
What are the Key Drivers of the Data Center Blade Market?
- The rapid expansion of cloud computing, artificial intelligence, and enterprise virtualization has increased demand for high-density blade server systems capable of processing growing workloads while optimizing data center space and infrastructure efficiency.
- For instance, in February 2025, Lenovo introduced its next-generation ThinkSystem V4 servers powered by Intel Xeon 6 processors, delivering up to 6.1 times higher compute performance than previous-generation CPUs and supporting advanced AI workloads.
- Enterprises, hyperscale operators, and cloud service providers are integrating scalable server infrastructure to improve workload consolidation, simplify management, and support increasing demands for reliable computing performance.
- For instance, in March 2025, Dell Technologies expanded its Dell AI Factory with NVIDIA, introducing advanced infrastructure solutions, including the PowerEdge XE8712, which supports up to 144 NVIDIA B200 GPUs per rack for accelerated AI computing and complex high-performance computing workloads.
- As organizations accelerate digital transformation and AI deployment, demand for scalable, high-density computing infrastructure is expected to increase, supporting adoption of advanced blade and modular server technologies.
What Factors are Challenging the Growth of the Data Center Blade Market?
- Data center blade systems require substantial upfront investment in server chassis, compatible components, networking infrastructure, and specialized power and cooling systems.
- For instance, in July 2024, Lenovo Press published an analysis explaining that rising processor power requirements, which had increased from approximately 150 W to 400 W or more, were making it increasingly difficult for traditional blade chassis to meet power and cooling demands
- These high costs can limit adoption among small and medium-sized enterprises and organizations seeking flexible, cost-effective alternatives to traditional blade server architectures.
- Increasing processor power requirements and evolving workload demands can further complicate thermal management, infrastructure upgrades, and long-term compatibility with existing data center facilities.
- For instance, in July 2024, Lenovo Press reported that blade server shipments declined by 88% between 2015 and 2023, including a 43% decline from 2022 to 2023, citing IDC Server Tracker data and highlighting the shrinking market and reduced vendor investment.
- The capital expenditure, cooling complexity, and potential vendor dependency associated with blade server deployments continue to challenge adoption, particularly among budget-conscious organizations, encouraging some buyers to consider alternative server architectures.
How is the Data Center Blade Market Segmented?
The data center blade market is segmented on the basis of data center type, service type, vertical, and end user.
- By Data Center Type
On the basis of data center type, the data center blade market is segmented into Tier 1, Tier 2, Tier 3, and Tier 4. The Tier 3 segment dominated the market with an estimated 42.5% share in 2025, owing to its balance between infrastructure reliability, operational efficiency, and investment requirements. Tier 3 facilities incorporate redundant power and cooling components to support continuous IT operations during planned maintenance. These facilities are widely adopted by enterprises, cloud service providers, and colocation operators that require high availability. Blade servers are suitable for Tier 3 environments because they enable centralized management, high computing density, and efficient resource utilization. Growing demand for cloud computing and enterprise applications is further supporting adoption.
The Tier 4 segment is projected to register the fastest growth at an estimated CAGR of 9.1% from 2026 to 2033, driven by increasing demand for fault-tolerant infrastructure and uninterrupted computing operations. Tier 4 facilities incorporate multiple independent and physically isolated distribution paths for power and cooling. These environments are particularly important for mission-critical workloads in financial services, healthcare, and large-scale cloud computing. Blade servers support high-density computing requirements in these facilities while enabling centralized hardware management. Growing investments in artificial intelligence and business-critical digital services are increasing demand for highly resilient infrastructure.
- By Service Type
On the basis of service type, the data center blade market is segmented into consulting services, installation and support services, and professional services. The installation and support services segment dominated the market with an estimated 43.8% share in 2025, owing to the technical requirements associated with blade server deployment, configuration, maintenance, and troubleshooting. These services help organizations integrate blade servers with existing networking, storage, power, and cooling infrastructure. Service providers also assist with hardware replacement, firmware updates, and performance monitoring. Increasing complexity in data center environments is strengthening demand for specialized technical support. Enterprises rely on these services to minimize downtime and maintain consistent computing performance.
The consulting services segment is projected to register the fastest growth at an estimated CAGR of 9.4% from 2026 to 2033, driven by rising demand for data center modernization, infrastructure optimization, and technology planning. Organizations increasingly require expert guidance to determine whether blade servers are suitable for their computing workloads and existing facilities. Consulting services help evaluate power requirements, cooling capacity, server consolidation opportunities, and total cost of ownership. Increasing adoption of artificial intelligence and hybrid cloud infrastructure is also encouraging enterprises to reassess their server architectures. Consultants support capacity planning, vendor evaluation, and migration strategies to improve infrastructure efficiency.
- By Vertical
On the basis of vertical, the data center blade market is segmented into IT and telecom, BFSI, public sector, healthcare, energy, manufacturing, media and entertainment, and others. The IT and telecom segment dominated the market with an estimated 36.7% share in 2025, supported by extensive investments in cloud computing, telecommunications infrastructure, and enterprise data processing. IT companies and telecom operators require high-density computing platforms to manage growing volumes of digital traffic and business applications. Blade servers provide centralized administration, efficient space utilization, and scalable processing capacity. Increasing deployment of virtualization and cloud-native applications is further supporting adoption. The expansion of telecommunications networks and digital services is increasing infrastructure requirements among telecom operators.
The healthcare segment is projected to register the fastest growth at an estimated CAGR of 10.2% from 2026 to 2033, driven by increasing digitalization of medical services and rising demand for secure data processing. Hospitals, diagnostic laboratories, and healthcare technology providers are generating growing volumes of electronic health records, medical imaging, and clinical data. Blade servers can support centralized applications, data management, and computing-intensive medical research. The growing adoption of artificial intelligence in diagnostics and medical imaging is increasing demand for powerful computing infrastructure. Healthcare organizations are also investing in systems that support interoperability and reliable access to critical information.
- By End User
On the basis of end user, the data center blade market is segmented into small-size organizations, medium-size organizations, and large-size organizations. The large-size organization segment dominated the market with an estimated 57.6% share in 2025, owing to substantial IT infrastructure requirements, larger computing workloads, and greater capacity for technology investments. Large enterprises operate complex applications that require reliable, scalable, and efficiently managed server infrastructure. Blade servers help consolidate computing resources and simplify administration across extensive IT environments. These systems are particularly relevant for financial institutions, multinational corporations, telecommunications companies, and cloud service providers. Increasing adoption of enterprise resource planning, virtualization, and artificial intelligence is strengthening demand.
The medium-size organization segment is projected to register the fastest growth at an estimated CAGR of 9.0% from 2026 to 2033, driven by growing digital transformation initiatives and increasing demand for scalable IT infrastructure. Medium-sized businesses are expanding their use of cloud-connected applications, data analytics, and enterprise management systems. Blade servers can help consolidate workloads and improve computing density where physical space is limited. As business operations become more data-intensive, these organizations are evaluating infrastructure that supports future capacity expansion. Managed infrastructure services and flexible financing options may improve accessibility for medium-sized enterprises. Increasing cybersecurity requirements and demand for reliable business applications are also encouraging infrastructure upgrades.
Which Region Holds the Largest Share of the Data Center Blade Market?
- North America dominated the data center blade market with the largest revenue share of 38.5% in 2025, supported by advanced data center infrastructure, strong cloud computing adoption, and substantial investments in hyperscale facilities.
- The region also benefits from increasing adoption of artificial intelligence, widespread enterprise virtualization, and growing demand for high-density computing infrastructure across IT and telecommunications, BFSI, and healthcare applications. Rising investments in hyperscale data centers, energy-efficient server technologies, and advanced cooling systems continue to strengthen North America’s leadership position in the global market.
U.S. Data Center Blade Market Insight
The U.S. data center blade market is witnessing strong growth due to rising investments in hyperscale data centers, cloud computing infrastructure, and artificial intelligence technologies. The country’s mature technology ecosystem, along with the presence of major cloud service providers and server manufacturers, is driving demand across enterprise, telecommunications, and financial services applications. In addition, growing emphasis on computing efficiency, infrastructure scalability, and advanced server management is accelerating blade server adoption across large enterprises and data center operators.
Asia-Pacific Data Center Blade Market Insight
The Asia-Pacific data center blade market is expected to witness rapid growth, driven by increasing digitalization, expanding cloud infrastructure, and rising investments in data center facilities across countries such as China, India, and Japan. Growing demand for high-performance computing, enterprise virtualization, and AI-enabled applications is supporting regional market expansion. In addition, increasing internet penetration, expanding telecommunications networks, and rising adoption of scalable server infrastructure are accelerating blade server deployment across commercial and industrial sectors.
Japan Data Center Blade Market Insight
The Japan data center blade market is witnessing consistent growth due to rising investments in digital infrastructure, cloud computing, and advanced enterprise IT systems. Businesses, telecommunications operators, and financial institutions are increasingly adopting blade servers to improve computing density, simplify infrastructure management, and support business-critical applications. Moreover, increasing integration of artificial intelligence, growing demand for reliable data processing, and the country’s focus on digital transformation are further contributing to market growth.
China Data Center Blade Market Insight
The China data center blade market is growing rapidly, driven by expanding cloud computing infrastructure, increasing data generation, and rising investments in artificial intelligence and digital services. Growing adoption of high-density server systems across telecommunications, financial services, and technology companies is significantly boosting market demand. In addition, government support for digital infrastructure development, expanding enterprise computing requirements, and rapid advancements in cloud technologies are positioning China as a key market for data center blade solutions.
U.K. Data Center Blade Market Insight
The U.K. data center blade market is experiencing steady growth, supported by rising adoption of cloud services, enterprise virtualization, and advanced data center infrastructure. Increasing investments in high-performance computing and demand for efficient server consolidation are contributing to market growth across financial services, telecommunications, and technology sectors. Furthermore, the growing use of AI-enabled applications and increasing emphasis on energy-efficient computing infrastructure are supporting blade server adoption among U.K. enterprises and data center operators.
Germany Data Center Blade Market Insight
The Germany data center blade market is expanding steadily due to the country’s strong industrial base, advanced technology ecosystem, and increasing adoption of digital enterprise solutions. Manufacturing companies, financial institutions, telecommunications operators, and cloud service providers are increasingly utilizing blade servers to support data-intensive applications and centralized IT operations. Continuous investments in cloud infrastructure, industrial digitalization, and AI computing, along with growing emphasis on operational efficiency and reliable data processing, are further driving market growth in Germany.
Which are the Top Companies in Data Center Blade Market?
The data center blade industry is primarily led by well-established companies, including:
- Cisco Systems, Inc. (U.S.)
- Dell Inc. (U.S.)
- Hewlett Packard Enterprise Company (U.S.)
- Lenovo (China)
- FUJITSU LIMITED (Japan)
- Huawei Technologies Co., Ltd. (China)
- International Business Machines Corporation (U.S.)
- NEC Corporation (Japan)
- Oracle Corporation (U.S.)
- Super Micro Computer, Inc. (U.S.)
- GIGA-BYTE TECHNOLOGY CO., LTD. (Taiwan)
- Inspur Electronic Information Industry Co., Ltd. (China)
- Quanta Computer Inc. (Taiwan)
- Wistron Corporation (Taiwan)
- Advantech Co., Ltd. (Taiwan)
- ASUSTeK Computer Inc. (Taiwan)
- Acer Inc. (Taiwan)
- ZTE Corporation (China)
- H3C Technologies Co., Limited (China)
- Silicom Ltd. (Israel)
What are Latest Developments in Data Center Blade Market?
- In August 2025, Giga Computing, a subsidiary of GIGABYTE, announced the launch of its first B-series blade servers, including the B343-C40 and B343-X40. The systems feature a compact chassis supporting multiple independent server nodes, shared power supplies, and centralized chassis management. Designed for enterprise, edge, and cloud workloads, the products incorporate recycled materials in selected components, highlighting the industry's focus on computing density, operational efficiency, and sustainable server infrastructure
- In June 2024, Supermicro announced its expanded X14 server portfolio featuring Intel Xeon 6 processors, including updated SuperBlade systems designed for AI, high-performance computing, cloud, and enterprise workloads. The new platforms emphasize high computing density, improved performance per watt, and support for advanced cooling technologies. This development reflects increasing demand for server infrastructure that can accommodate demanding workloads while improving data center efficiency.
- In May 2023, Supermicro showcased its X13 SuperBlade systems featuring fourth-generation Intel Xeon Scalable processors at COMPUTEX 2023. The systems incorporated shared power, cooling, networking, and chassis management components to improve computing density and reduce cabling requirements. Designed for artificial intelligence, data analytics, high-performance computing, cloud, and enterprise workloads, the development highlighted continued innovation in modular server infrastructure for modern data centers.
- In March 2022, Supermicro announced support for third-generation AMD EPYC processors featuring AMD 3D V-Cache technology across its advanced server portfolio, including SuperBlade systems. The development targeted technical computing applications requiring enhanced processing performance, including engineering simulations, scientific research, and data-intensive workloads. By expanding processor options for blade infrastructure, the announcement demonstrated ongoing efforts to improve server performance and support demanding enterprise computing requirements
- In March 2021, Supermicro announced the availability of its server portfolio powered by AMD EPYC 7003 Series processors, including SuperBlade systems for cloud data centers, enterprise computing, and artificial intelligence workloads. The company reported improved benchmark performance for its SuperBlade platform, demonstrating the potential of newer processor architectures to accelerate demanding workloads. This development reflected continued investment in higher-performance, energy-conscious server infrastructure for modern data center environments.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.