What is the Food Microencapsulation Market Size and Growth Rate?
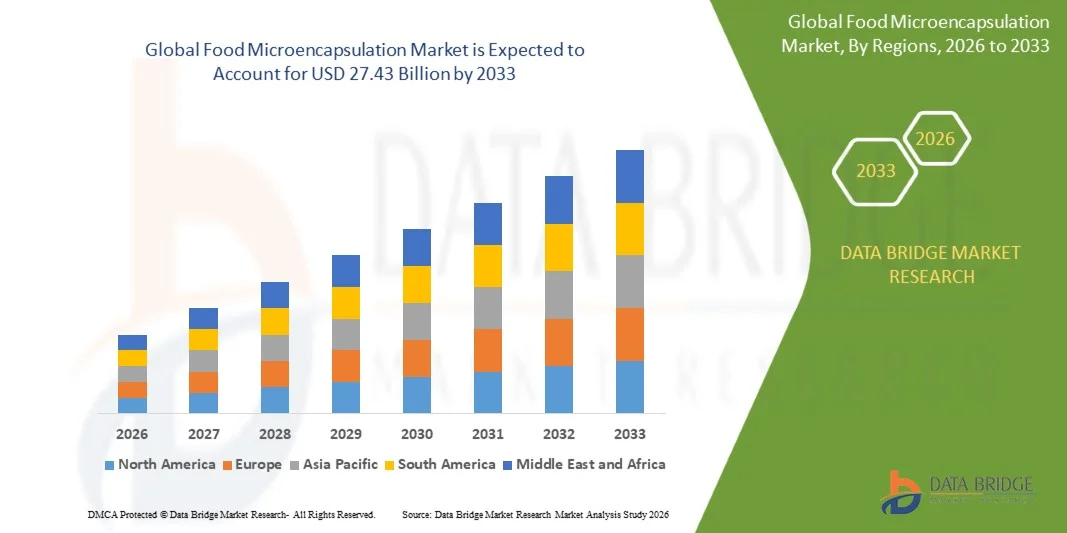
- As per Data Bridge Market Research analysis, the food microencapsulation market was valued at USD 14.70 billion in 2025 and is projected to reach USD 27.43 billion by 2033, growing at a CAGR of 8.30% from 2026 to 2033.
- The market is experiencing consistent growth driven by increasing demand for functional and fortified food products, rising adoption of microencapsulation technologies to improve the stability, shelf life, solubility, and controlled release of sensitive ingredients, and growing use of encapsulated vitamins, minerals, probiotics, omega-3 fatty acids, flavors, and essential oils across food and beverage applications.
- The increasing demand for nutrient-enriched and clean-label food products, combined with growing consumer preference for functional foods and beverages, is encouraging food manufacturers to adopt advanced microencapsulation solutions. Product innovation across dairy products, bakery and confectionery, beverages, functional foods, dietary supplements, and snacks is further supporting market growth, while improvements in spray drying, coacervation, emulsion-based encapsulation, and other encapsulation technologies are expanding the range of ingredients that can be effectively incorporated into food formulations.
Market Size & Forecast
- Global Market Value (2025): USD 14.70 Billion
- Expected Market Value (2033): USD 27.43 Billion
- Forecast CAGR (2026–2033): 8.30%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Food Microencapsulation Market?
- North America dominated the Food Microencapsulation market with the largest revenue share of 32.4% in 2025, supported by strong demand for functional and fortified foods, advanced food processing capabilities, high adoption of encapsulation technologies, and the presence of established food, nutraceutical, and ingredient manufacturers. The region also benefits from increasing incorporation of encapsulated probiotics, vitamins, omega-3 fatty acids, flavors, and other sensitive ingredients into food and beverage formulations.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 9.2% from 2026 to 2033, fueled by increasing consumption of functional foods and beverages, rising disposable incomes, expanding food processing industries, growing awareness of nutritional products, and increasing adoption of advanced food ingredient technologies across China, India, Japan, South Korea, and other emerging economies.
- The spray drying segment led the technology category with a 41.6% share in 2025, driven by its cost-effectiveness, scalability, high encapsulation efficiency, and widespread use for protecting sensitive food ingredients such as flavors, vitamins, probiotics, enzymes, and omega-3 fatty acids. Spray drying remains one of the most extensively used microencapsulation techniques in food and beverage manufacturing.
- The liposomal encapsulation segment is the fastest-growing technology category, projected to register a CAGR of 10.1% from 2026 to 2033, reflecting increasing demand for improved bioavailability, controlled delivery, and enhanced stability of sensitive nutritional and bioactive compounds in functional foods, beverages, and nutraceutical applications.
- The functional foods segment accounted for 29.8% of the application category in 2025, supported by rising consumer demand for nutrient-enriched products, growing use of probiotics, vitamins, minerals, omega-3 fatty acids, and other bioactive ingredients, and increasing emphasis on improving ingredient stability and bioavailability through microencapsulation.
- Polysaccharides accounted for 36.7% of the shell material segment in 2025, supported by their favorable film-forming properties, compatibility with food formulations, ability to protect sensitive active ingredients, and broad application in spray-dried and other encapsulation systems. Materials such as maltodextrin, starch derivatives, alginate, and other carbohydrate-based polymers are widely used as encapsulating agents.
- The probiotics segment is the fastest-growing core-material category, with a CAGR of 10.4% from 2026 to 2033, driven by increasing consumer interest in digestive and gut-health products and the need to protect probiotic microorganisms from moisture, oxygen, temperature, and processing conditions while improving their stability and viability in food products.
Report Scope and Food Microencapsulation Market Segmentation
|
Attributes |
Food Microencapsulation Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, pricing analysis, brand share analysis, consumer survey, demography analysis, supply chain analysis, value chain analysis, raw material/consumables overview, vendor selection criteria, PESTLE Analysis, Porter Analysis, and regulatory framework. |
What is the Key Trend in the Food Microencapsulation Market?
- Food microencapsulation manufacturers are increasingly focusing on the encapsulation of sensitive and bioactive ingredients, including probiotics, vitamins, minerals, omega-3 fatty acids, enzymes, flavors, and essential oils, to improve stability, protect ingredients from environmental conditions, and enhance their incorporation into food formulations.
- For instance, in 2025, ingredient manufacturers continued to expand solutions for encapsulated nutrients and functional ingredients, supporting their use across functional foods, beverages, dietary supplements, and other food applications.
- Product innovation is increasingly focused on improving the controlled release, bioavailability, taste masking, and stability of active ingredients through advanced microencapsulation technologies.
- Spray drying remains widely used for food microencapsulation because of its scalability, relatively efficient processing, and suitability for encapsulating flavors, oils, vitamins, probiotics, and other sensitive ingredients.
- Food microencapsulation companies are also developing plant-based and clean-label encapsulation systems using materials such as starches, maltodextrin, gums, proteins, and other food-compatible wall materials to address changing formulation requirements.
- As manufacturers continue to combine functional ingredients with advanced delivery technologies, improved stability, controlled release, and enhanced bioavailability are expected to remain important components of the global Food Microencapsulation market.
What are the Key Drivers of the Food Microencapsulation Market?
- The increasing consumer demand for functional and fortified food products is supporting the adoption of microencapsulation technologies for incorporating vitamins, minerals, probiotics, omega-3 fatty acids, enzymes, and other bioactive ingredients into food and beverage formulations.
- The growing consumption of probiotic and gut-health products is encouraging manufacturers to use microencapsulation to protect sensitive probiotic cultures from moisture, oxygen, temperature, and processing conditions.
- Manufacturers are also expanding their use of encapsulated flavors, essential oils, and other sensitive ingredients to improve stability, reduce undesirable taste or odor, and support consistent flavor delivery in processed food and beverage products.
- The increasing demand for improved shelf life and ingredient stability is further encouraging the adoption of microencapsulation, particularly for ingredients that are sensitive to oxidation, light, heat, and moisture.
- For instance, food ingredient manufacturers are developing encapsulated systems designed to protect functional compounds during processing and storage while enabling their effective incorporation into finished food products.
- Technological developments in spray drying, coacervation, emulsion-based encapsulation, fluidized bed coating, extrusion, and liposomal encapsulation are also expanding the range of food ingredients that can be microencapsulated.
- With manufacturers continuing to focus on functional nutrition, ingredient protection, controlled release, and improved product stability, the increasing adoption of microencapsulation across food and beverage applications is expected to support continued market growth.
Which Factors are Challenging the Growth of the Food Microencapsulation Market?
- Food microencapsulation manufacturers face challenges associated with high processing costs, complex formulation requirements, specialized equipment, and the need to maintain consistent encapsulation efficiency during large-scale production.
- The selection of suitable wall materials and processing conditions can increase formulation complexity, as manufacturers need to balance encapsulation efficiency, ingredient compatibility, particle size, stability, release characteristics, and sensory properties.
- The need for specialized production equipment and technical expertise can increase capital and operating requirements, particularly for small and medium-sized food manufacturers seeking to adopt advanced encapsulation technologies.
- Food microencapsulation companies also face challenges in maintaining the stability and performance of encapsulated ingredients throughout food processing, storage, transportation, and final product preparation.
- In addition, regulatory requirements for food ingredients, functional compounds, additives, and encapsulating materials can vary across countries, potentially increasing product development, testing, and compliance requirements.
- Manufacturers must also balance improved ingredient functionality with clean-label requirements, cost considerations, sensory characteristics, and consumer acceptance, which can complicate the development and commercialization of microencapsulated food products.
- As the technology becomes more widely adopted, the ability to achieve cost-efficient large-scale production while maintaining encapsulation performance, food safety, regulatory compliance, and product quality is expected to remain a key challenge for market participants.
How is the Food Microencapsulation Market Segmented?
The food microencapsulation market is segmented on the basis of technology, core material, shell material, application, and end use.
- By Technology
On the basis of technology, the Food Microencapsulation market is segmented into spray drying, coacervation, fluidized bed coating, emulsion, extrusion, liposomal encapsulation, and others. The spray drying segment dominated the market with a 41.62% share in 2025, supported by its scalability, cost-effectiveness, high processing efficiency, and suitability for encapsulating sensitive food ingredients such as flavors, vitamins, probiotics, enzymes, and omega-3 fatty acids. Spray drying enables manufacturers to improve ingredient stability, protect active compounds from environmental conditions, and facilitate their incorporation into a wide range of food and beverage formulations.
The liposomal encapsulation segment is projected to register the fastest growth at a 10.18% CAGR during the forecast period, driven by increasing demand for enhanced bioavailability, controlled delivery, and improved stability of sensitive nutritional and bioactive compounds. Growing applications in functional foods, beverages, dietary supplements, and nutraceutical formulations are further supporting adoption of liposomal encapsulation technologies.
- By Core Material
On the basis of core material, the Food Microencapsulation market is segmented into vitamins, minerals, probiotics, enzymes, omega-3 fatty acids, flavors, essential oils, organic acids, and others. The vitamins segment dominated the market with a 24.76% share in 2025, supported by increasing demand for fortified foods and beverages and the widespread use of microencapsulation to protect vitamins from oxidation, heat, light, moisture, and other environmental conditions. Encapsulation also supports improved handling, controlled release, and incorporation of vitamins into different food formulations.
The probiotics segment is projected to register the fastest growth at a 10.42% CAGR during the forecast period, driven by increasing consumer interest in gut health, digestive wellness, and functional nutrition. Microencapsulation helps protect probiotic microorganisms against processing, storage, moisture, oxygen, and acidic environments, supporting improved viability and stability throughout the product lifecycle.
- By Shell Material
On the basis of shell material, the Food Microencapsulation market is segmented into polysaccharides, proteins, lipids, gums and resins, emulsifiers, and others. The polysaccharides segment dominated the market with a 36.74% share in 2025, supported by the broad availability, food compatibility, film-forming properties, and functional characteristics of carbohydrate-based encapsulating materials. Maltodextrin, starch derivatives, alginate, and other polysaccharide-based materials are widely used to protect sensitive ingredients and improve their stability during processing and storage.
The protein segment is projected to register the fastest growth at a 9.76% CAGR during the forecast period, driven by increasing demand for protein-based functional foods and the favorable emulsification, gelation, and film-forming properties of proteins. The growing use of proteins as encapsulating materials for bioactive compounds, flavors, oils, and nutritional ingredients is further supporting segment growth.
- By Application
On the basis of application, the Food Microencapsulation market is segmented into functional foods, bakery and confectionery, dairy products, beverages, dietary supplements, snacks and savory products, and others. The functional foods segment dominated the market with a 29.82% share in 2025, supported by increasing consumer demand for nutrient-enriched and health-oriented food products. Microencapsulation enables the incorporation of probiotics, vitamins, minerals, omega-3 fatty acids, enzymes, and other bioactive compounds while improving stability, taste masking, and controlled release.
The beverages segment is projected to register the fastest growth at a 9.86% CAGR during the forecast period, driven by increasing demand for fortified beverages, functional drinks, sports nutrition products, and probiotic beverages. Microencapsulation enables manufacturers to incorporate sensitive nutrients, flavors, oils, and bioactive compounds while minimizing undesirable sensory effects and improving ingredient stability.
- By End Use
On the basis of end use, the Food Microencapsulation market is segmented into food and beverage manufacturers, nutraceutical companies, dietary supplement producers, and others. The food and beverage manufacturers segment dominated the market with a 52.64% share in 2025, supported by the extensive adoption of microencapsulation technologies for improving ingredient stability, extending shelf life, protecting sensitive compounds, and incorporating functional ingredients into mainstream food and beverage products.
The nutraceutical companies segment is projected to register the fastest growth at a 10.06% CAGR during the forecast period, driven by increasing demand for functional ingredients, targeted nutrient delivery, probiotics, omega-3 fatty acids, vitamins, and other bioactive compounds. Growing emphasis on bioavailability, controlled release, and protection of sensitive ingredients is encouraging nutraceutical manufacturers to adopt microencapsulation technologies across product development and formulation.
Which Region Holds the Largest Share of the Food Microencapsulation Market?
- North America dominated the Food Microencapsulation market with the largest revenue share of 32.4% in 2025, supported by strong demand for functional and fortified food products, widespread adoption of advanced food processing technologies, and increasing use of microencapsulation for vitamins, probiotics, omega-3 fatty acids, flavors, enzymes, and other sensitive food ingredients.
- The region also benefits from well-developed food processing infrastructure, strong research and development capabilities, and the presence of major food ingredient and technology companies. Increasing consumer interest in functional foods, clean-label products, nutritional enrichment, and improved ingredient stability is further encouraging manufacturers to expand the use of Food Microencapsulation technologies across food and beverage applications.
U.S. Food Microencapsulation Market Insight
The U.S. Food Microencapsulation market is witnessing strong growth due to increasing demand for functional foods, fortified beverages, dietary supplements, and nutraceutical products. The country's advanced food processing industry, established research and development ecosystem, and strong presence of food ingredient manufacturers support the adoption of microencapsulation technologies for probiotics, vitamins, minerals, omega-3 fatty acids, flavors, essential oils, and enzymes. In addition, growing consumer interest in health and wellness, clean-label formulations, improved nutrient delivery, and extended product stability is encouraging manufacturers to incorporate Food Microencapsulation technologies into new product development.
Asia-Pacific Food Microencapsulation Market Insight
The Asia-Pacific Food Microencapsulation market is expected to witness rapid growth, driven by rising disposable incomes, urbanization, increasing health awareness, and growing demand for functional and fortified food products across countries such as China, India, and Japan. Expansion of food processing industries, nutraceutical manufacturing, modern retail, and convenience-oriented food consumption is increasing the adoption of microencapsulation technologies. In addition, manufacturers are increasingly using microencapsulation for probiotics, vitamins, omega-3 fatty acids, flavors, essential oils, and other bioactive ingredients to improve stability, sensory characteristics, and incorporation into food and beverage formulations.
Japan Food Microencapsulation Market Insight
The Japan Food Microencapsulation market is witnessing consistent growth due to strong demand for functional foods, nutritionally enriched products, probiotics, and high-quality food formulations. Consumers increasingly seek products offering health and wellness benefits, supporting the use of microencapsulation for vitamins, minerals, probiotics, omega-3 fatty acids, and other bioactive ingredients. Moreover, Japan's advanced food processing industry, strong research and development capabilities, and emphasis on product quality and technological innovation provide opportunities for manufacturers to develop microencapsulated ingredients with improved stability, controlled release, and enhanced functionality.
China Food Microencapsulation Market Insight
The China Food Microencapsulation market is growing rapidly, driven by increasing urbanization, rising disposable incomes, expanding food processing industries, and growing consumer interest in functional and fortified foods. Increasing demand for probiotics, vitamins, omega-3 fatty acids, flavors, and other nutritional ingredients is supporting the adoption of microencapsulation technologies across food and beverage applications. In addition, expansion of nutraceutical manufacturing, modern retail, and innovative food product development is encouraging manufacturers to use microencapsulation to improve ingredient stability, protect sensitive compounds, and enhance the nutritional and sensory characteristics of finished products.
U.K. Food Microencapsulation Market Insight
The U.K. Food Microencapsulation market is experiencing steady growth, supported by established food processing industries, increasing demand for functional and fortified foods, and growing adoption of advanced ingredient delivery technologies. Consumers are showing increasing interest in products containing probiotics, vitamins, minerals, omega-3 fatty acids, and other health-oriented ingredients, encouraging manufacturers to adopt microencapsulation for improved stability and controlled delivery. Furthermore, strong research and development capabilities and the presence of established food ingredient manufacturers provide opportunities for the expansion of Food Microencapsulation technologies across food, beverage, nutraceutical, and dietary supplement applications.
Germany Food Microencapsulation Market Insight
The Germany Food Microencapsulation market is expanding steadily due to a well-established food processing industry, strong technological capabilities, and increasing consumer interest in functional and nutritionally enriched food products. Food manufacturers are increasingly adopting microencapsulation technologies to protect sensitive ingredients, improve shelf stability, mask undesirable flavors, and facilitate the incorporation of vitamins, probiotics, omega-3 fatty acids, flavors, and other bioactive compounds into food formulations. Continuous investment in food technology, ingredient innovation, and sustainable formulation solutions is also supporting the diversification and adoption of Food Microencapsulation technologies across the country.
Which are the Top Companies in Food Microencapsulation Market?
The food microencapsulation industry is primarily led by well-established companies, including:
- BASF SE (Germany)
- Kerry Group plc (Ireland)
- Givaudan SA (Switzerland)
- International Flavors & Fragrances Inc. (U.S.)
- DSM-Firmenich AG (Switzerland)
- Ingredion Incorporated (U.S.)
- Cargill, Incorporated (U.S.)
- Tate & Lyle PLC (U.K.)
- Roquette Frères (France)
- Symrise AG (Germany)
- Balchem Corporation (U.S.)
- Encapsys LLC (U.S.)
- Lycored Corp. (Israel)
- Sensient Technologies Corporation (U.S.)
- Brenntag SE (Germany)
- Azelis Group NV (Belgium)
- FMC Corporation (U.S.)
- Capsugel (U.S.)
- Frutarom Industries Ltd. (Israel)
What are Latest Developments in Food Microencapsulation Market?
- In September 2025, BASF SE expanded its food ingredient solutions with innovations focused on nutritional ingredients and functional food applications, supporting the development of food formulations requiring improved ingredient stability, delivery, and protection of sensitive compounds. The development reflects the increasing adoption of advanced ingredient technologies in functional foods, beverages, and dietary supplement applications.
- In April 2025, Kerry Group plc advanced its ingredient solutions portfolio with technologies supporting functional nutrition, taste enhancement, and improved ingredient performance in food and beverage formulations. The development highlights the growing use of encapsulation and delivery technologies to improve the stability, sensory characteristics, and functionality of sensitive food ingredients.
- In March 2025, DSM-Firmenich AG continued to expand its nutritional ingredient and health solutions, supporting the incorporation of vitamins, probiotics, omega-3 fatty acids, and other bioactive ingredients into food, beverage, and dietary supplement formulations. Such innovations are supporting demand for technologies that protect sensitive ingredients and improve their performance throughout processing and storage.
- In February 2025, Ingredion Incorporated expanded its food ingredient solutions for functional and specialty food applications, including technologies designed to improve formulation stability, texture, and ingredient performance. The development demonstrates the continued focus of food ingredient manufacturers on advanced formulation technologies for clean-label, fortified, and functional food products.
- In January 2025, Givaudan SA continued to develop ingredient and flavor solutions aimed at improving taste, stability, and sensory performance across food and beverage applications. The increasing integration of advanced delivery technologies for flavors and other sensitive ingredients is supporting product innovation and broader adoption of microencapsulation solutions in food formulations.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Food Microencapsulation Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Food Microencapsulation Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Food Microencapsulation Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.