What is the Industrial Water Treatment Chemical Market Size and Growth Rate?
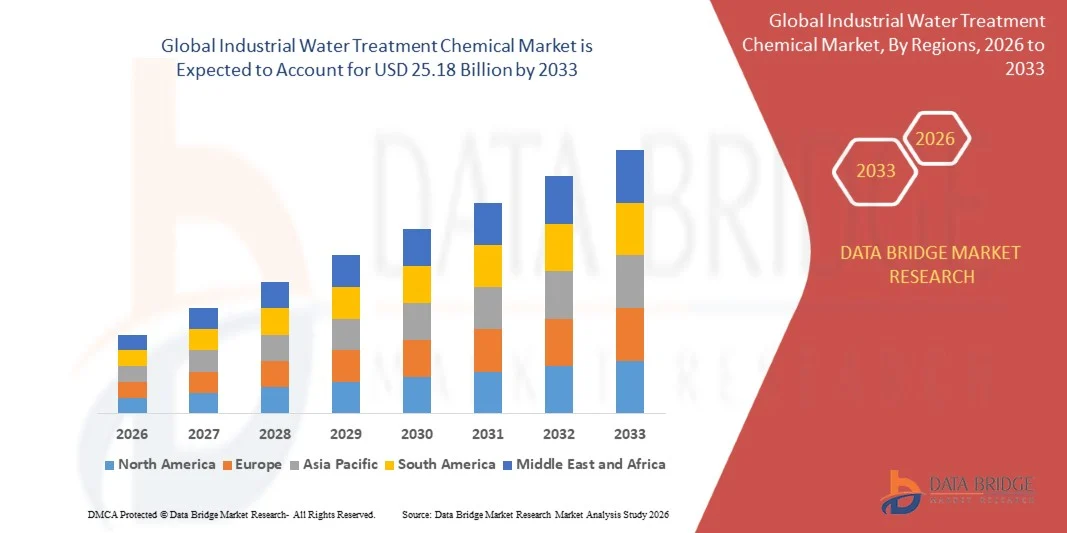
- As per Data Bridge Market Research analysis, the industrial water treatment chemical market was valued at USD 16.04 billion in 2025 and is projected to reach USD 25.18 billion by 2033, growing at a CAGR of 5.80% from 2026 to 2033.
- The market is experiencing steady growth driven by tightening discharge regulations, increasing industrial water reuse, and expanding demand from power, semiconductor, data center, food, and chemical operations.
- The increasing shift toward water reuse, zero liquid discharge, and efficient cooling and boiler operations, combined with growing industrialization and stricter environmental limits, is supporting market adoption. Treatment chemicals are being applied across cooling towers, boilers, effluent plants, and ultrapure water systems, offering plants greater protection from scale, corrosion, and fouling through industrial water treatment chemicals, coagulants and flocculants, and corrosion and scale inhibitors programs.
Market Size & Forecast
- Global Market Value (2025): USD 16.04 Billion
- Expected Market Value (2033): USD 25.18 Billion
- Forecast CAGR (2026–2033): 5.80%
- Leading Region in 2025: Asia-Pacific
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Industrial Water Treatment Chemical Market?
- Asia-Pacific dominated the industrial water treatment chemical market with the largest revenue share of 39.60% in 2025, supported by rapid industrialization, large power and chemical sectors, and tightening effluent rules in China and India.
- Asia-Pacific is also expected to be the fastest-growing region at a CAGR of 6.90% from 2026 to 2033, fueled by industrial expansion, semiconductor investment, and rising water scarcity.
- The coagulants & flocculants segment led the market with a 31.40% share in 2025, driven by its role in clarification, solids removal, and wastewater compliance.
- Biocides & disinfectants are the fastest-growing product type, projected to register a CAGR of 6.70%, reflecting rising demand for microbial control in cooling systems, data centers, and reuse applications.
- The cooling water segment dominated the application category with a 35.20% revenue share in 2025, led by large cooling tower use in power, chemical, and data center facilities.
- Power generation accounted for 26.40% of the market share in 2025, preferred for heavy boiler and cooling water treatment needs and strict reliability requirements.
- The electronics & semiconductors segment is the fastest-growing end-use industry, with a CAGR of 8.40%, driven by ultrapure water demand, fab expansion, and strict contamination limits.
Report Scope and Industrial Water Treatment Chemical Market Segmentation
|
Attributes |
Industrial Water Treatment Chemical Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, geographically represented company-wise production and capacity, network layouts of distributors and partners, detailed and updated price trend analysis and deficit analysis of supply chain and demand. |
What is the Key Trend in the Industrial Water Treatment Chemical Market?
- Industrial water treatment chemicals are increasingly evolving from standalone products into integrated, digitally monitored service programs, combining chemistry, sensors, remote dosing, and performance guarantees for high-value customers.
- For instance, in June 2026, Kemira acquired the industrial water treatment business of Clear Water Technologies, expanding its North American boiler and cooling-tower treatment services and strengthening its customer support capabilities.
- Ultrapure water and semiconductor applications are gaining attention, as chip fabrication and advanced electronics require very low contaminant levels and specialized treatment technologies.
- Service-led consolidation is increasing, as suppliers expand local reach, application engineering, and digital monitoring, while buyers compare programs on total cost of ownership, water savings, compliance support, and uptime.
- For instance, in December 2025, according to Ecolab’s Form 10-Q, the company completed the acquisition of Ovivo Electronics, a provider of ultrapure water technologies for semiconductor manufacturing, recording about USD 1.2 billion of goodwill and strengthening its high-tech water position, while also adding specialized engineering expertise
- As water scarcity, data center growth, semiconductor investment, and digital monitoring continue to advance, industrial water treatment chemicals are expected to expand beyond basic scale and corrosion control into integrated reuse, cooling, and high-purity water solutions.
What are the Key Drivers of the Industrial Water Treatment Chemical Market?
- Tightening discharge regulations and rising water costs have significantly increased industrial investment in treatment programs that protect equipment, reduce water use, and support reuse.
- For instance, in May 2025, Ecolab launched its 3D TRASAR Technology for Direct-to-Chip Liquid Cooling, enabling real-time monitoring of coolant concentration, temperature, pH, and flow rates to improve cooling-system reliability and operational efficiency in high-performance data centers.
- Power plants, refineries, chemical producers, food processors, and electronics manufacturers are adopting advanced chemistries to prevent scale and corrosion, control microbes, improve efficiency, and meet environmental permits.
- For instance, in June 2025, Solenis announced an agreement to acquire NCH Corporation, expanding its footprint in localized industrial water treatment programs, reflecting service-led consolidation in the sector and the growing importance of local service coverage.
- With data center, semiconductor, and power investments growing and regulators tightening limits, industrial water treatment chemicals can gain wider visibility, qualification, and recurring orders across cooling, boiler, and wastewater applications.
What Factors are Challenging the Growth of the Industrial Water Treatment Chemical Market?
- Industrial water treatment chemicals depend on petrochemical and mineral raw materials and energy-intensive production, which exposes suppliers to commodity cost swings and supply disruptions.
- For instance, in April 2026, according to Ecolab’s first-quarter results, commodity costs were expected to increase by high-single digits starting in the second quarter and remain high through the end of the year, requiring an energy surcharge and pricing actions, showing how input costs can affect suppliers’ profit margins.
- These cost pressures can squeeze margins and slow contract renewals, while competition from membrane, thermal, and other physical treatment technologies may limit chemical use in some applications.
- Environmental limits on phosphorus, certain biocides, and heavy metals, along with difficulty handling chemicals safely, further restrict growth, requiring suppliers to invest in greener formulations, safe dosing systems, and registrations that may increase development costs.
- For instance, in July 2026, according to Ecolab’s second-quarter supplemental data, Paper and Heavy Water sales continued to act as a headwind to overall growth, highlighting how weakness in some heavy industries can reduce demand for treatment chemicals and weak plant utilization.
- The combination of raw material volatility, regulatory limits on key chemistries, competing physical technologies, and cyclical industrial demand can constrain growth among cost-sensitive buyers and smaller suppliers.
How is the Industrial Water Treatment Chemical Market Segmented?
The industrial water treatment chemical market is segmented on the basis of product type, application, end-use industry, and form.
- By Product Type
On the basis of product type, the industrial water treatment chemical market is segmented into coagulants & flocculants, corrosion & scale inhibitors, biocides & disinfectants, and pH adjusters & others. The coagulants & flocculants segment dominated the market with 31.40% share in 2025, supported by its role in clarification, solids removal, and wastewater compliance. Aluminum, iron, and polymer-based products aggregate fine particles so they can settle or be filtered. They are widely used in pulp and paper, metals, mining, and municipal-type industrial effluent plants. Large volumes and regulatory requirements keep demand steady. Improved polymers and blends also help reduce sludge and dosing, strengthening the segment’s leadership. Operators also rely on technical service teams to select the right dose and product for changing water quality.
The biocides & disinfectants segment is projected to register the fastest growth at a CAGR of 6.70% from 2026 to 2033, driven by rising demand for microbial control in cooling systems, data centers, and reuse applications. Biofilm and Legionella control are important for safety and efficiency. Non-oxidizing and oxidizing programs are being tailored to different water conditions. Reuse of treated effluent increases the need for reliable disinfection. Regulatory review of active ingredients remains an important consideration. Suppliers are also developing lower-toxicity and faster-degrading actives to meet stricter rules.
- By Application
On the basis of application, the industrial water treatment chemical market is segmented into cooling water, boiler water, wastewater, and process water. The cooling water segment dominated the market with 35.20% share in 2025, supported by large cooling tower use in power, chemical, and data center facilities. Chemicals prevent scale, corrosion, and biological growth that reduce heat transfer. Plants run higher cycles of concentration to save water, which raises treatment needs. Service contracts and monitoring support recurring demand. Established programs from major suppliers continue to reinforce the segment’s leadership. Plants also benefit from remote monitoring that tracks conductivity, pH, and corrosion in real time.
The process water segment is projected to register the fastest growth at a CAGR of 7.60% from 2026 to 2033, driven by growth in ultrapure water for semiconductors, pharmaceuticals, and food production. These uses require very low levels of ions, particles, and organics. Treatment programs combine membranes, ion exchange, and specialty chemicals. New fabs and advanced manufacturing sites are expanding demand. Technical expertise and strict quality control are key requirements. Growing demand for water reuse inside plants also raises the importance of advanced treatment steps.
- By End-Use Industry
On the basis of end-use industry, the industrial water treatment chemical market is segmented into power generation, oil & gas, chemicals, food & beverage, electronics & semiconductors, and others. The power generation segment dominated the end-use category with 26.40% share in 2025, supported by heavy boiler and cooling water treatment needs and strict reliability requirements. Plants use chemicals to protect turbines, boilers, and heat exchangers. Water scarcity encourages reuse and higher cycles of concentration. Established maintenance programs continue to reinforce this segment's leadership. Combined cycle plants and flexible generation also change water chemistry needs and drive new treatment programs.
The electronics & semiconductors segment is projected to register the fastest growth at a CAGR of 8.40% from 2026 to 2033, driven by ultrapure water demand, fab expansion, and strict contamination limits. Chip makers need ultra-clean water for rinsing, cooling, and process steps. Supply chain security programs are supporting new plant construction. Suppliers are acquiring specialized technology to serve this market. High capital intensity and strict specifications remain important considerations. Rapid growth in advanced packaging and memory production is also adding to the need for tailored water programs.
- By Form
On the basis of form, the industrial water treatment chemical market is segmented into liquid and dry. The liquid segment dominated the market with 68.30% share in 2025, supported by ease of dosing, fast dissolution, and compatibility with automated feed systems. Liquid products are widely used for corrosion inhibitors, biocides, and polymers. They reduce handling and dust. Bulk delivery and on-site storage fit large facilities. Established supply networks continue to reinforce this segment's leadership. Reliable supply and technical support also help customers manage product changes across multiple sites.
The dry segment is projected to register the fastest growth at a CAGR of 6.20% from 2026 to 2033, driven by lower transport costs, longer shelf life, and demand in remote or developing regions. Powdered coagulants, polymers, and softening agents are easy to store and ship. Smaller plants value flexibility and lower freight costs. Improved dissolution systems are reducing handling issues. Dust control and worker safety remain important considerations. Producers are also offering blends that combine several functions in one easy-to-handle product.
Which Region Holds the Largest Share of the Industrial Water Treatment Chemical Market?
- Asia-Pacific dominated the industrial water treatment chemical market with the largest revenue share of 39.60% in 2025, supported by rapid industrialization, large power and chemical sectors, and tightening effluent rules in China and India.
- The region also benefits from large power, chemical, steel, and textile sectors, rapid construction of new plants, and a growing base of local chemical manufacturers. Increasing environmental enforcement and water scarcity continue to strengthen Asia-Pacific’s position in the global market. Rapid growth in electronics and data centers also adds new demand for cooling and high-purity water programs.
Japan Industrial Water Treatment Chemical Market Insight
The Japan industrial water treatment chemical market is witnessing consistent growth due to a strong electronics and chemical industry, high quality expectations, and leading domestic water technology firms. Manufacturers and utilities are increasingly adopting high-purity and efficient treatment programs. Moreover, strong demand for reliable operations, water saving, and technological innovation is further contributing to market growth in Japan. Close cooperation between suppliers and manufacturers also supports tailored treatment programs.
China Industrial Water Treatment Chemical Market Insight
The China industrial water treatment chemical market is growing rapidly, driven by massive industrial output, strict environmental enforcement, and large investments in power and semiconductor capacity. Growing wastewater reuse targets are significantly boosting market demand. In addition, strong domestic chemical producers, government water programs, and expanding industrial parks are positioning China as a key growth market across Asia-Pacific. Large-scale investment in industrial water reuse also supports demand for advanced chemicals and services.
Europe Industrial Water Treatment Chemical Market Insight
Europe’s Industrial Water Treatment Chemical Market is witnessing steady growth, driven by stringent environmental regulations, increasing industrial wastewater treatment requirements, and rising demand for water recycling. Coagulants, flocculants, corrosion inhibitors, antiscalants, and biocides are widely used across power generation, chemicals, manufacturing, and food processing industries. Germany remains a key market due to its strong industrial base, while Spain and Nordic countries present emerging opportunities. Growing adoption of sustainable formulations, advanced treatment technologies, and digital chemical dosing is expected to support future market expansion.
U.K. Industrial Water Treatment Chemical Market Insight
The U.K. industrial water treatment chemical market is experiencing steady growth, supported by strict environmental permitting, a mature chemicals and food sector, and focus on water efficiency. Industrial operators are increasingly adopting reuse and monitoring technologies. Furthermore, net-zero goals, water stress in some regions, and demand for specialized service providers are supporting wider adoption of treatment chemicals in the U.K. Growing interest in digital water management also supports adoption among large industrial users.
Germany Industrial Water Treatment Chemical Market Insight
The Germany industrial water treatment chemical market is expanding steadily due to the country’s strong chemical, automotive, and machinery industries, strict environmental standards, and advanced engineering. Industrial users and utilities are increasingly utilizing efficient, low-phosphorus, and safer chemistries. Continuous innovation in treatment technology, strict EU rules, and Germany’s focus on resource efficiency are further driving market growth in the country. Strong research and development capacity also helps suppliers bring improved products to market quickly.
Which are the Top Companies in Industrial Water Treatment Chemical Market?
The industrial water treatment chemical industry is primarily led by well-established companies, including:
- Ecolab Inc. (U.S.)
- Veolia Environnement S.A. (France)
- Kemira Oyj (Finland)
- Solenis LLC (U.S.)
- BASF SE (Germany)
- Kurita Water Industries Ltd. (Japan)
- SNF Group (France)
- Dow Inc. (U.S.)
- LANXESS AG (Germany)
- Italmatch Chemicals S.p.A. (Italy)
- Buckman Laboratories International, Inc. (U.S.)
- Innospec Inc. (U.S.)
- Thermax Limited (India)
- Ashland Inc. (U.S.)
- Chemtrade Logistics Income Fund (Canada)
- Nouryon Chemicals Holding B.V. (Netherlands)
- Accepta Ltd. (U.K.)
- Hydrite Chemical Co. (U.S.)
- Shandong Taihe Water Treatment Technologies Co., Ltd. (China)
- Evonik Industries AG (Germany)
What are Latest Developments in Industrial Water Treatment Chemical Market?
- In July 2026, Ecolab reported second-quarter results showing accelerating growth in Food & Beverage, Institutional, and Light Water, while headwinds from Paper and Heavy Water continued to ease. The company also expected the CoolIT Systems acquisition to close during the third quarter of 2026. The results highlight continued strength in service-led and high-tech water markets.
- In June 2026, Solenis partnered with Dow through Dow’s Coolant Care Network to provide coolant monitoring, fluid management, and reliability services for data centers using direct-to-chip liquid cooling systems.
- In May 2026, Dorf-Ketal entered India’s industrial water treatment sector by acquiring the water treatment business of Vasu Chemicals LLP, expanding its portfolio into industrial water management solutions.
- In March 2026, Ecolab entered into an agreement to acquire CoolIT Systems, a data center liquid cooling company, for USD 4.75 billion from funds managed by KKR. The acquisition is intended to create an end-to-end fluid management and cooling platform for AI data centers. The deal is expected to broaden Ecolab’s role in data center cooling beyond chemistry.
- In December 2025, Ecolab completed the acquisition of Ovivo Electronics, a leading provider of ultrapure water technologies for semiconductor manufacturing. The acquisition expands Ecolab’s Global High-Tech business and its capabilities in electronics water treatment. The deal also strengthens Ecolab’s position in a fast-growing, high-purity market.
- In October 2025, Kemira acquired Water Engineering, Inc., adding regional capabilities in industrial water treatment programs and services. The acquisition reflects continued consolidation in the sector as suppliers seek local reach and application expertise. The deal also adds engineering capacity and customer relationships in regional markets.
- In June 2025, Solenis announced an agreement to acquire NCH Corporation, expanding its footprint in localized industrial water treatment programs. The combination creates a larger platform delivering water treatment chemicals across many countries. The deal highlights how larger suppliers are using acquisitions to broaden service coverage.
- In May 2025, Ecolab launched its 3D TRASAR Technology for Direct-to-Chip Liquid Cooling, enabling real-time monitoring of coolant concentration, temperature, pH, and flow rates to improve cooling-system reliability and operational efficiency in high-performance data centers.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Industrial Water Treatment Chemical Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Industrial Water Treatment Chemical Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Industrial Water Treatment Chemical Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.