What is the Mining Remanufacturing Components Market Size and Growth Rate?
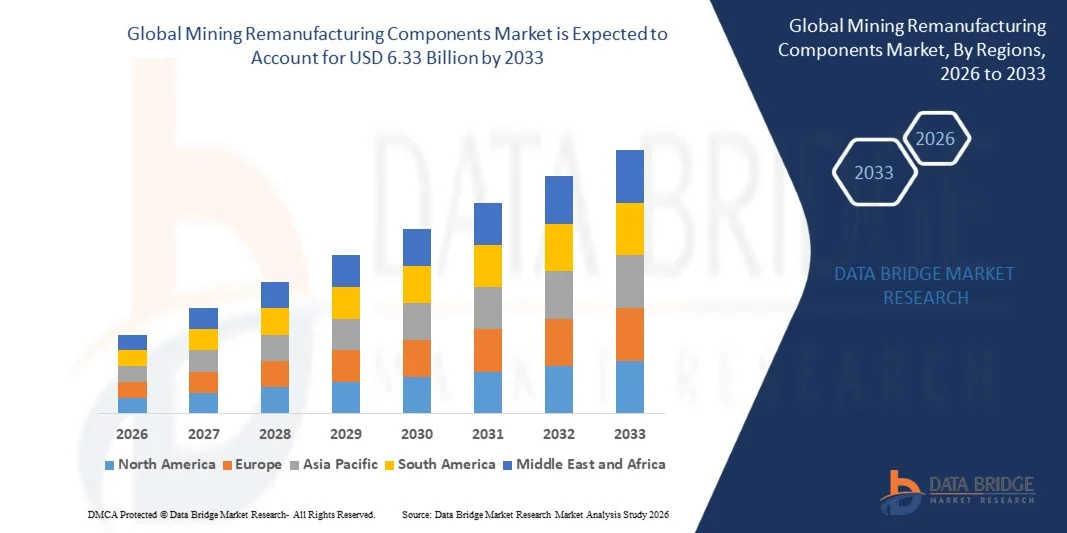
- As per Data Bridge Market Research analysis, the mining remanufacturing components market was valued at USD 4.73 billion in 2025 and is projected to reach USD 6.33 billion by 2033, growing at a CAGR of 3.70% from 2026 to 2033.
- The market is experiencing steady growth driven by rising demand for cost-effective alternatives to new heavy equipment components amid volatile commodity price cycles, growing mining company emphasis on total cost of ownership reduction, and increasing adoption of circular economy practices that extend the operational life of capital-intensive mining machinery.
- The growing emphasis on minimizing unplanned equipment downtime, reducing capital expenditure on new machinery, and improving fleet sustainability metrics is compelling mining companies to increasingly integrate remanufactured components into their maintenance and equipment replacement strategies. OEM-certified remanufacturing programs are increasingly complementing independent aftermarket remanufacturers, offering mining companies engineered-to-original-specification components backed by manufacturer warranties.
- The growing sophistication of remanufacturing processes, incorporating advanced inspection, testing, and quality certification protocols, is narrowing the perceived performance gap between remanufactured and new components, further supporting broader mining industry acceptance of remanufactured parts across increasingly critical equipment applications.
Market Size & Forecast
- Global Market Value (2025): USD 4.73 Billion
- Expected Market Value (2033): USD 6.33 Billion
- Forecast CAGR (2026–2033): 3.70%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Mining Remanufacturing Components Market?
- North America dominated the global mining remanufacturing components market with the largest revenue share of 34.62% in 2025, supported by extensive established mining equipment fleets, mature OEM-certified remanufacturing infrastructure, and strong mining industry emphasis on total cost of ownership optimization.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 5.8% from 2026 to 2033, fueled by rapidly expanding mining operations, growing equipment fleet age requiring component overhaul, and increasing adoption of remanufacturing practices across China, Australia, and India.
- The engines component segment led the market with a 28.74% share in 2025, driven by the high cost and technical complexity of engine replacement, making remanufacturing a particularly compelling economic alternative to new component procurement.
- The hydraulic pumps & cylinders segment is the fastest-growing component type, projected to register a CAGR of 5.4%, reflecting increasing wear-related failure rates of hydraulic systems in heavy excavation equipment and growing availability of specialized hydraulic remanufacturing capabilities.
- The haul trucks equipment type segment dominated the equipment category with a 31.68% revenue share in 2025, led by the massive scale and high replacement cost of haul truck drivetrain and engine components across large surface mining operations.
- Surface mining accounted for 68.42% of the market share among mining types in 2025, preferred due to its larger equipment fleets and higher overall equipment utilization rates driving more frequent component wear and remanufacturing demand.
- The OEM-certified remanufacturers sales channel segment is the fastest-growing category, with a CAGR of 5.1%, driven by growing mining company preference for warranty-backed, engineered-to-specification remanufactured components over independent aftermarket alternatives.
- The transmissions & drivetrain components segment accounted for a substantial share of overall demand in 2025, reflecting the critical role of drivetrain reliability in maintaining continuous haul truck and heavy equipment operation across mining sites.
- The mining companies end-user segment held a 71.24% share in 2025, supported by direct ownership of large equipment fleets and continuous need for cost-effective component replacement to maintain operational uptime.
Report Scope and Mining Remanufacturing Components Market Segmentation
|
Attributes |
Mining Remanufacturing Components Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Mining Remanufacturing Components Market?
- Mining equipment OEMs are increasingly expanding their certified remanufacturing programs to cover a broader range of components and equipment models, offering mining companies an integrated pathway to reduce fleet maintenance costs while maintaining OEM-backed quality assurance and warranty coverage.
- For instance, in March 2025, Caterpillar expanded its Cat Reman program to include additional hydraulic component models for its largest haul truck platforms, providing mining customers with OEM-certified remanufactured alternatives for previously new-only replacement parts.
- Growing integration of predictive maintenance and condition-monitoring technology into mining equipment fleets is enabling more precise identification of components approaching end-of-service-life, allowing mining companies to proactively schedule remanufactured component replacement before unplanned failures occur.
- Remanufacturing facilities are increasingly adopting advanced inspection and testing technologies, including automated dimensional scanning and non-destructive testing methods, to ensure remanufactured components meet or exceed original equipment performance specifications.
- For instance, in February 2025, Komatsu expanded its remanufacturing facility capabilities with new automated component inspection technology, improving quality consistency and reducing turnaround time for remanufactured drivetrain components.
- Growing collaboration between mining companies and remanufacturing providers on core exchange programs, where worn components are returned in exchange for remanufactured replacements at reduced cost, is streamlining the logistics and economics of component replacement across large, geographically distributed mining equipment fleets.
- As mining companies continue to prioritize total cost of ownership reduction, equipment fleet sustainability, and supply chain resilience, the adoption of remanufactured mining components is expected to steadily increase, reinforcing their role as an established alternative to new component procurement across the global mining equipment maintenance ecosystem.
What are the Key Drivers of the Mining Remanufacturing Components Market?
- The persistent volatility in commodity prices affecting mining company capital budgets has significantly increased demand for cost-effective component replacement alternatives that allow operators to maintain equipment fleets without committing to full new component procurement costs.
- For instance, in April 2025, Sandvik expanded its remanufacturing service offerings for underground mining equipment to help mining customers manage equipment lifecycle costs more effectively amid fluctuating commodity price cycles affecting capital expenditure budgets.
- The aging global mining equipment fleet, with substantial numbers of haul trucks, excavators, and drilling rigs now well past their initial component service life, is driving sustained demand for remanufactured replacement components across both surface and underground mining operations.
- For instance, in December 2024, Komatsu Mining expanded distribution of its remanufactured drivetrain components to additional mining customers operating aging equipment fleets across North America and Australia, supporting continued fleet operation without full equipment replacement.
- The growing corporate emphasis on environmental, social, and governance reporting among major mining companies is increasingly favoring remanufactured components, as remanufacturing typically requires significantly less raw material and energy input compared to manufacturing new components, supporting sustainability metric improvement alongside cost savings.
- With ongoing commodity price volatility, aging global mining equipment fleets, and growing emphasis on sustainable, circular economy maintenance practices, remanufactured mining components will remain an important cost-management tool across the global mining industry.
Which Factors are Challenging the Growth of the Mining Remanufacturing Components Market?
- The remanufacturing process requires specialized technical expertise, testing capabilities, and quality controls, creating barriers for smaller providers serving complex mining equipment.
- For instance, in September 2024, Liebherr highlighted its Reman program and exchange-component services for mining equipment at MINExpo 2024, emphasizing component reliability and performance under demanding mining conditions. This demonstrates the technical and quality requirements associated with mining-component remanufacturing.
- Reliability concerns can also limit adoption of non-OEM or remanufactured components, particularly where equipment uptime is critical. In March 2024, Weir Minerals emphasized that component quality and performance are essential for maintaining mining-equipment productivity, noting concerns around the guaranteed performance and longevity of replicated parts.
How is the Mining Remanufacturing Components Market Segmented?
The mining remanufacturing components market is segmented on the basis of component type, equipment type, mining type, sales channel, end user, and mineral type.
- By Component Type
On the basis of component type, the global mining remanufacturing components market is segmented into engines, transmissions & drivetrain components, hydraulic pumps & cylinders, axles & final drives, turbochargers, electrical & electronic components, and others. The engines segment dominated the market with a 28.74% share in 2025, owing to the high cost and technical complexity of engine replacement, making remanufacturing a particularly compelling economic alternative to new component procurement. These components remain the preferred remanufacturing target for mining companies seeking the greatest cost savings relative to new part procurement.
The hydraulic pumps & cylinders segment is projected to register the fastest growth at a CAGR of 5.4% from 2026 to 2033, driven by increasing wear-related failure rates of hydraulic systems in heavy excavation equipment and growing availability of specialized hydraulic remanufacturing capabilities among both OEM and independent providers.
- By Equipment Type
On the basis of equipment type, the global mining remanufacturing components market is segmented into haul trucks, excavators & shovels, wheel loaders, dozers, drilling rigs, draglines, and others. The haul trucks segment led the market with a 31.68% share in 2025, supported by the massive scale and high replacement cost of haul truck drivetrain and engine components across large surface mining operations requiring continuous high-utilization equipment operation.
The excavators & shovels segment is expected to experience the fastest growth at a CAGR of 5.2% from 2026 to 2033, driven by rising demand for remanufactured hydraulic and undercarriage components as excavator and shovel fleets continue to age across major surface mining operations globally.
- By Mining Type
On the basis of mining type, the global mining remanufacturing components market is segmented into surface mining and underground mining. The surface mining segment dominated the market with a share of 68.42% in 2025 due to its larger equipment fleets and higher overall equipment utilization rates driving more frequent component wear and remanufacturing demand. the continued global dominance of surface mining methods for coal and metal ore extraction is reinforcing this segment’s leading position.
The underground mining segment is expected to witness the fastest CAGR of 4.6% from 2026 to 2033, driven by this growth is fueled by increasing underground mining activity as easily accessible surface deposits become depleted, requiring specialized remanufactured components suited to the unique operating conditions of underground equipment.
- By Sales Channel
On the basis of sales channel, the global mining remanufacturing components market is segmented into OEM-certified remanufacturers and independent/aftermarket remanufacturers. The OEM-certified remanufacturers segment dominated the market with a share of 56.83% in 2025 due to mining companies’ preference for warranty-backed, engineered-to-specification remanufactured components that maintain full compatibility with original equipment systems. established OEM service networks and quality assurance reputation continue to reinforce this segment’s leading position.
The OEM-certified remanufacturers segment is also expected to witness the fastest CAGR of 5.1% from 2026 to 2033, driven by growing mining company preference for warranty-backed, engineered-to-specification remanufactured components over independent aftermarket alternatives, particularly for critical drivetrain and engine components.
- By End User
On the basis of end user, the global mining remanufacturing components market is segmented into mining companies, equipment rental companies, and contract miners. The mining companies segment dominated the market with a share of 71.24% in 2025 due to their direct ownership of large equipment fleets and continuous need for cost-effective component replacement to maintain operational uptime. the widespread adoption of remanufactured components within mining company maintenance and reliability programs is reinforcing this segment’s leading position.
The equipment rental companies segment is expected to witness the fastest CAGR of 5.3% from 2026 to 2033, driven by growing demand for remanufactured components among rental fleet operators seeking to maintain competitive rental rates while ensuring reliable equipment performance for mining customers.
- By Mineral Type
On the basis of mineral type, the global mining remanufacturing components market is segmented into coal, metal ores, and industrial minerals. The metal ores segment dominated the market with a share of 47.62% in 2025 due to sustained global demand for iron ore, copper, and gold driving continuous heavy equipment operation and component wear across major metal ore mining regions. the widespread scale of global metal ore mining operations continues to reinforce this segment’s leading position.
The metal ores segment is also expected to witness the fastest CAGR of 4.8% from 2026 to 2033, driven by rising global demand for battery and infrastructure metals including copper, supporting continued expansion of metal ore mining equipment fleets requiring ongoing component maintenance and remanufacturing support.
Which Region Holds the Largest Share of the Mining Remanufacturing Components Market?
- North America dominated the mining remanufacturing components market and accounted for the largest revenue share of 34.62% in 2025, supported by extensive established mining equipment fleets, mature OEM-certified remanufacturing infrastructure, and strong mining industry emphasis on total cost of ownership optimization.
- The region also benefits from a well-established network of OEM and independent remanufacturing facilities, extensive mining industry experience with remanufactured component quality and reliability, and continued investment in remanufacturing technology by leading equipment manufacturers headquartered in the region. Continued focus on mining fleet cost management continues to strengthen North America’s leadership position in the global market.
U.S. Mining Remanufacturing Components Market Insight
The U.S. mining remanufacturing components market holds the largest share within North America, driven by extensive domestic coal and metal ore mining operations, well-established OEM remanufacturing infrastructure, and strong mining industry familiarity with remanufactured component quality and cost benefits. Rising mining company focus on total cost of ownership reduction and fleet sustainability metrics is further supporting market growth. Additionally, continued investment by leading domestic equipment manufacturers in remanufacturing facility capacity is reinforcing the country’s position as a key market for mining remanufacturing components.
Canada Mining Remanufacturing Components Market Insight
Canada’s mining remanufacturing components market is expanding as mining operators seek to reduce maintenance costs, extend equipment lifecycles, and minimize downtime. Demand is supported by aging mining fleets, rising equipment costs, and growing emphasis on sustainability and circular-economy practices. Key opportunities include remanufactured engines, transmissions, hydraulic cylinders, axles, and drivetrain components. Canada’s established mining industry supports adoption, while core availability, reverse logistics, component quality, and remote mine locations remain key challenges.
Asia-Pacific Mining Remanufacturing Components Market Insight
The Asia-Pacific mining remanufacturing components market is expected to witness rapid growth, driven by rapidly expanding mining operations, growing equipment fleet age requiring component overhaul, and increasing adoption of remanufacturing practices across the region. Rising government support for circular economy and sustainable industrial practices is supporting regional market expansion. Additionally, the growing presence of both international and domestic remanufacturing facilities is accelerating market adoption across the region.
China Mining Remanufacturing Components Market Insight
The China mining remanufacturing components market is growing rapidly, driven by extensive domestic coal and metal ore mining operations, rising government support for circular economy and industrial sustainability initiatives, and growing adoption of remanufacturing practices among domestic mining equipment manufacturers. Growing adoption of remanufactured components across large-scale state-owned and private mining operations is significantly boosting market demand. In addition, rising domestic remanufacturing technical capabilities are positioning China as one of the fastest-growing markets for mining remanufacturing components globally.
India Mining Remanufacturing Components Market Insight
The India mining remanufacturing components market is witnessing robust growth, driven by expanding domestic coal and iron ore mining operations, rising government investment in mining sector modernization, and growing awareness of remanufacturing as a cost-effective equipment maintenance strategy. Increasing adoption of remanufactured components among both public and private mining operators is supporting market expansion. Additionally, the entry of international remanufacturing service providers is further accelerating market adoption across the country.
Which are the Top Companies in Mining Remanufacturing Components Market?
The mining remanufacturing components industry is primarily led by well-established companies, including:
- Caterpillar Inc. (U.S.)
- Komatsu Ltd. (Japan)
- Liebherr Group (Germany)
- Hitachi Construction Machinery Co., Ltd. (Japan)
- Sandvik AB (Sweden)
- Epiroc AB (Sweden)
- Terex Corporation (U.S.)
- HD Hyundai Infracore (formerly Doosan Infracore) (South Korea)
- SANY Group (China)
- XCMG Construction Machinery Co., Ltd. (China)
- Volvo Construction Equipment (Volvo Group) (Sweden)
- Metso Outotec Corporation (Finland)
- Wirtgen Group (John Deere) (Germany)
- Deere & Company (U.S.)
- Weir Group PLC (U.K.)
- FLSmidth & Co. A/S (Denmark)
- Komatsu Mining Corp. (formerly Joy Global) (U.S.)
- Zoomlion Heavy Industry Science & Technology Co., Ltd. (China)
- Cummins Inc. (U.S.)
- Bosch Rexroth AG (Germany)
What are Latest Developments in Mining Remanufacturing Components Market?
- In September 2025, Caterpillar expanded its Cat Reman facility network with a new dedicated large-engine remanufacturing center, increasing capacity to service the largest ultra-class mining haul truck engine platforms for global mining customers.
- In January 2025, Komatsu Mining expanded its remanufactured drivetrain component product line to include additional models compatible with aging underground mining equipment fleets across North America and Australia.
- In November 2025, Sandvik introduced an expanded remanufacturing warranty program for its underground drilling equipment components, offering mining customers extended coverage periods to build confidence in remanufactured component reliability.
- In November 2024, Liebherr expanded its remanufacturing service capabilities for large mining excavator hydraulic systems, addressing growing demand from surface mining customers seeking cost-effective alternatives to new hydraulic component procurement.
- In June 2023, Weir Group partnered with several mining companies in Australia and South Africa to conduct field validation of its remanufactured pump components for mineral processing applications, demonstrating comparable performance to new components at significantly reduced cost.
- In August 2024, Hitachi Construction Machinery expanded its remanufacturing service network in South America to support growing demand from copper mining customers in Chile and Peru seeking cost-effective component replacement for aging excavator fleets.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.