What is the Non-Chocolate Candy Market Size and Growth Rate?
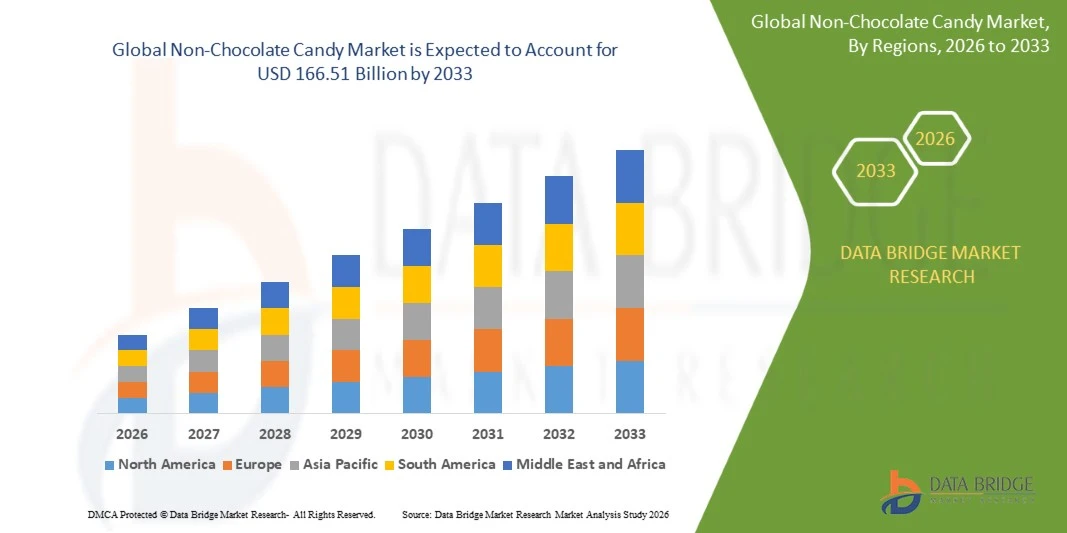
- As per Data Bridge Market Research analysis, the non-chocolate candy market was valued at USD 108.50 billion in 2025 and is projected to reach USD 166.51 billion by 2033, growing at a CAGR of 5.50% from 2026 to 2033.
- The market is experiencing consistent growth driven by rising demand for diverse confectionery products, increasing consumer preference for innovative flavors and textures, and expanding distribution through supermarkets, convenience stores, and online retail channels.
- The growing popularity of gummies, hard candies, chewing candies, and fruit-flavored confectionery, combined with seasonal consumption and product innovation, is supporting market expansion. Manufacturers are increasingly introducing sugar-free alternatives, new flavor combinations, and attractive packaging to address changing consumer preferences and strengthen demand across global markets.
Market Size & Forecast
- Global Market Value (2025): USD 108.50 Billion
- Expected Market Value (2033): USD 166.51 Billion
- Forecast CAGR (2026–2033): 5.50%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Non-Chocolate Candy Market?
- North America dominated the non-chocolate candy market with the largest revenue share of 34.6% in 2025, supported by established confectionery manufacturers, strong retail distribution networks, and high consumer demand for convenient candy products
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 5.8% from 2026 to 2033, fueled by rising disposable incomes, expanding retail infrastructure, and increasing demand for innovative confectionery products across China, India, and other emerging Asian markets.
- The hard type segment led the market with a 38.0% share in 2025, driven by the established popularity of hard candies, boiled sweets, and traditional sugar confectionery.
- Chewing type are the fastest-growing type, projected to register a CAGR of 5.8%, reflecting the surge in demand for chewy candies, soft sweets, and products offering distinctive mouthfeel.
- The hard candy segment dominated the product type category with a 32.0% revenue share in 2025, led by widespread availability, affordable pricing, and established consumer preferences
- Fruit accounted for 48.6% of the market share in 2025, preferred by widespread consumer acceptance and the extensive availability of fruit-flavored confectionery.
- The sour segment is the fastest-growing flavor category, with a CAGR of 8.2%, driven by consumer interest in intense taste sensations and distinctive confectionery experiences.
Report Scope and Non-Chocolate Candy Market Segmentation
|
Attributes |
Non-Chocolate Candy Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, pricing analysis, brand share analysis, consumer survey, demography analysis, supply chain analysis, value chain analysis, raw material/consumables overview, vendor selection criteria, PESTLE Analysis, Porter Analysis, and regulatory framework. |
What is the Key Trend in the Non-Chocolate Candy Market?
- Non-chocolate candy manufacturers are increasingly focusing on innovative flavors, distinctive textures, and novel product formats to attract younger consumers and differentiate their confectionery offerings in competitive retail markets.
- For instance, in May 2025, FoodNavigator reported that gummy candy brands were introducing innovative shapes, contrasting textures, bold flavor combinations, and interactive formats to attract consumers. Nassau Candy showcased its Clever Candy range with novelty-shaped gummies and sour flavor varieties, reflecting the growing emphasis on multisensory confectionery experiences
- Gummies, freeze-dried candies, sour confectionery, and limited-edition products are gaining attention as consumers seek entertaining and multisensory snacking experiences beyond traditional hard candies and mints.
- Manufacturers are also expanding better-for-you confectionery options, including reduced-sugar products and candies featuring functional ingredients, to respond to evolving consumer preferences.
- Product innovation increasingly emphasizes colorful packaging, unusual flavor combinations, and formats designed to encourage social sharing and repeat purchases among younger demographics.
- Seasonal product launches, nostalgic flavors, and premium candy assortments are further helping brands attract consumers seeking distinctive treats for everyday consumption, gifting, and celebrations.
- For instance, in May 2025, ConfectioneryNews reported that SweeTARTS launched Gummy Halos, combining a soft, airy gummy layer with a chewy layer in Blue Punch and Strawberries & Cream flavors. The launch highlights manufacturers' focus on distinctive textures, flavor combinations, and new candy formats
- As confectionery companies continue prioritizing differentiated experiences and changing consumer preferences, innovation in flavor, texture, and formulation is expected to remain a key trend shaping the non-chocolate candy market.
What are the Key Drivers of the Non-Chocolate Candy Market?
- The rising consumer demand for convenient, affordable, and ready-to-eat confectionery products is supporting the growth of non-chocolate candies across supermarkets, convenience stores, and other retail channels.
- For instance, in October 2024, Reuters reported that U.S. candy manufacturers were expanding non-chocolate Halloween offerings, including gummies, licorice, and flavored crème candies, as consumers sought more affordable alternatives amid rising chocolate prices and high cocoa costs. This shift demonstrates how price-conscious purchasing and seasonal demand can drive sales of non-chocolate confectionery.
- Growing popularity among younger consumers, combined with expanding product variety, is encouraging manufacturers to introduce gummies, chewy candies, sour sweets, and innovative flavor combinations.
- The expansion of modern retail and e-commerce platforms is improving product accessibility, enabling confectionery brands to reach a wider customer base and promote specialty candy varieties.
- Increasing demand for sugar-free and reduced-sugar alternatives is encouraging manufacturers to diversify their product portfolios and respond to changing dietary preferences among health-conscious consumers.
- For instance, in April 2025, Innova Market Insights reported that India's sugar confectionery market recorded 7% sales growth and 6% volume growth over the preceding five years. The research also found that 40% of Indian consumers had increased their sugar confectionery consumption, citing taste preferences, lifestyle changes, and greater availability of product varieties as contributing factors.
- With evolving consumption habits, expanding distribution networks, and continued product innovation supporting category demand, the non-chocolate candy market is positioned for further growth across established and emerging markets.
What Factors are Challenging the Growth of the Non-Chocolate Candy Market?
- Non-chocolate candy manufacturers face fluctuating raw material costs, particularly for sugar, corn syrup, sweeteners, flavorings, and packaging materials, which can increase production expenses and pressure profit margins.
- For instance, in February 2024, Mintel reported that nearly three in five Indian consumers were trying to reduce their sugar intake, creating challenges for conventional sugar confectionery manufacturers. Reformulating candies to reduce sugar while maintaining the expected sweetness, texture, and affordability can increase product-development complexity and limit consumer acceptance
- Rising production and distribution costs can force manufacturers to increase retail prices or reduce package sizes, potentially weakening demand among price-sensitive consumers and affecting repeat purchases.
- Growing consumer awareness of sugar consumption and dietary health concerns may limit demand for conventional sugar-heavy candies, compelling manufacturers to reformulate products while maintaining taste and texture.
- Competition from alternative snacks, including savory snacks, protein bars, and other reduced-sugar products, creates additional pressure on candy manufacturers to retain consumer interest and differentiate their offerings.
- For instance, in May 2025, the Government of India introduced the Sugar (Control) Order, 2025, establishing provisions governing sugar production, sales, packaging, and domestic and international trade. Changes in sugar-sector controls and supply conditions can create uncertainty in the availability and procurement costs of sugar, a key ingredient for non-chocolate candy manufacturers.
- These cost pressures, changing dietary preferences, and competitive challenges can constrain profitability and complicate product development, particularly for manufacturers targeting affordable mass-market confectionery segments.
How is the Non-Chocolate Candy Market Segmented?
The non-chocolate candy market is segmented on the basis of type, product type, flavor, and distribution channel.
- By Type
On the basis of type, the non-chocolate candy market is segmented into hard type, chewing type, and scotch type. The hard type segment dominated the market with an estimated 38.0% share in 2025, supported by the established popularity of hard candies, boiled sweets, and traditional sugar confectionery. These products offer extended shelf life and are convenient for storage, transportation, and retail distribution. Their availability in fruit, mint, sour, and other flavors helps manufacturers appeal to a broad consumer base. Hard candies are widely sold through supermarkets, convenience stores, and small neighborhood retailers. Their relatively simple manufacturing processes and suitability for individual packaging further support their commercial appeal.
The chewing type segment is expected to witness comparatively strong growth, at an estimated CAGR of 5.8% from 2026 to 2033, driven by demand for chewy candies, soft sweets, and products offering distinctive mouthfeel. Consumers are increasingly attracted to confectionery products that combine multiple textures and flavors. Manufacturers are expanding their portfolios with fruit chews, filled candies, and innovative gummy-based products to encourage repeat purchases. Attractive shapes and convenient packaging also support consumption among younger consumers. Product innovation and the introduction of new flavor combinations are helping chewing candies differentiate themselves from traditional hard sweets.
- By Product Type
On the basis of product type, the non-chocolate candy market is segmented into hard candy, gummies and jellies, mints, chewing gum, caramels and toffees, lollipops and suckers, licorice candy, and other non-chocolate candies. The hard candy segment dominated the market with an estimated 32.0% share in 2025, supported by widespread availability, affordable pricing, and established consumer preferences. Hard candies are available in numerous flavors, shapes, and packaging formats, allowing manufacturers to target different age groups and consumption occasions. Their relatively long shelf life supports inventory management and distribution across extensive retail networks. Individually wrapped products are particularly suitable for convenience stores and impulse purchases. Established production capabilities and strong brand recognition further contribute to the segment's market presence.
The gummies and jellies segment is projected to register the fastest growth at an estimated CAGR of 6.8% from 2026 to 2035, driven by increasing consumer interest in chewy textures, innovative shapes, and bold flavor combinations. Gummies and jellies are available in fruit, sour, tropical, and assorted flavor varieties, broadening their appeal across age groups. Manufacturers are introducing layered textures, filled gummies, and novelty formats to differentiate their offerings. Colorful designs and character-shaped products also help attract younger consumers. The popularity of premium, sour, and unconventional confectionery experiences is encouraging further product innovation. Continued product development and expanding consumer interest are expected to support the segment's expansion.
- By Flavor
On the basis of flavor, the non-chocolate candy market is segmented into fruit, mint, sour, caramel and butterscotch, cinnamon and spiced flavors, berry, tropical, and other flavors. The fruit flavor segment dominated the market with an estimated 48.6% share in 2025, supported by widespread consumer acceptance and the extensive availability of fruit-flavored confectionery. Popular flavors such as strawberry, orange, lemon, apple, and watermelon appeal to consumers across different age groups. Fruit flavors are compatible with hard candies, gummies, jellies, lollipops, and chewing candies, providing manufacturers with considerable product development flexibility. Their familiar taste profiles encourage repeat purchases and support mass-market distribution. Manufacturers frequently introduce mixed-fruit combinations to expand their product offerings. Broad consumer appeal and versatility across candy formats continue to support demand for fruit-flavored products.
The sour flavor segment is expected to witness the fastest growth, at an estimated CAGR of 8.2% from 2026 to 2033, driven by consumer interest in intense taste sensations and distinctive confectionery experiences. Sour gummies, chewy sweets, and hard candies are particularly attractive to younger consumers seeking bold flavors. Manufacturers are developing products that combine sour coatings with sweet centers to create contrasting taste experiences. Novelty packaging and unusual flavor combinations further differentiate sour candies from traditional confectionery products. Social media exposure and interest in new candy experiences can also encourage product discovery and trial purchases. Continued flavor innovation is expected to support the segment's expansion.
- By Distribution Channel
On the basis of distribution channel, the non-chocolate candy market is segmented into supermarkets/hypermarkets, specialist stores, convenience stores, online stores, and others. The supermarkets/hypermarkets segment dominated the market with an estimated 42.4% share in 2025, supported by extensive product availability, established retail networks, and convenient access to multiple confectionery brands. These outlets offer a wide selection of hard candies, gummies, mints, chewing gum, and other non-chocolate sweets in different price ranges. High consumer footfall supports impulse purchases and routine confectionery buying. Promotional campaigns, discounts, and seasonal displays encourage product discovery and increase basket purchases. Large retail chains also provide manufacturers with opportunities to introduce new products and improve brand visibility.
The online stores segment is expected to witness the fastest growth, at an estimated CAGR of 8.9% from 2026 to 2033, driven by increasing e-commerce adoption and consumer demand for convenient purchasing options. Online platforms allow consumers to explore a broader selection of domestic, imported, premium, and specialty candy products. Home delivery and easy product comparisons improve the shopping experience. Digital promotions and targeted advertising help confectionery brands reach specific consumer groups. Online channels also support the sale of assorted candy boxes, customized gift packs, and products that may have limited availability in physical stores. Continued improvements in digital retail infrastructure and delivery services are expected to strengthen online confectionery sales.
Which Region Holds the Largest Share of the Non-Chocolate Candy Market?
- North America dominated the non-chocolate candy market with the largest revenue share of 34.6% in 2025, supported by established confectionery manufacturers, strong retail distribution networks, and high consumer demand for convenient candy products
- The region also benefits from high consumption of gummies, hard candies, chewing gum, and other sugar confectionery products, alongside well-established supermarkets, convenience stores, and specialty retail channels. Strong brand recognition, seasonal candy purchases, and continuous product innovation further reinforce North America's leadership in the global market
U.S. Non-Chocolate Candy Market Insight
The U.S. non-chocolate candy market is witnessing strong growth due to rising consumer demand for gummies, hard candies, mints, chewing gum, and other sugar confectionery products. The country’s established confectionery industry, along with extensive retail distribution networks and strong brand presence, is driving demand across supermarkets, convenience stores, and online channels. In addition, growing interest in innovative flavors, sugar-free alternatives, and convenient snack options is accelerating product development and expanding consumer appeal across different age groups.
Asia-Pacific Non-Chocolate Candy Market Insight
The Asia-Pacific non-chocolate candy market is expected to witness rapid growth, driven by rising urbanization, increasing disposable incomes, and expanding demand for confectionery products across countries such as China, India, and Japan. Growing consumer interest in gummies, fruit-flavored candies, mints, and innovative confectionery formats, along with the expansion of modern retail infrastructure, is supporting regional market expansion. In addition, increasing e-commerce penetration, product innovation, and the growing availability of affordable packaged sweets are accelerating non-chocolate candy consumption across the region.
Japan Non-Chocolate Candy Market Insight
The Japan non-chocolate candy market is witnessing consistent growth due to rising demand for innovative confectionery products, premium flavors, and convenient snack options. Candy manufacturers are increasingly introducing fruit-flavored sweets, gummies, hard candies, and functional confectionery products to address evolving consumer preferences. Moreover, the country’s strong confectionery culture, emphasis on product quality, and continued development of distinctive flavors and packaging formats are further contributing to market growth.
China Non-Chocolate Candy Market Insight
The China non-chocolate candy market is growing rapidly, driven by rising disposable incomes, expanding urban populations, and increasing consumer demand for diverse confectionery products. Growing adoption of fruit-flavored candies, gummies, mints, and premium sweets, supported by expanding supermarkets, convenience stores, and online retail platforms, is significantly boosting market demand. In addition, rising interest in novel flavors, attractive packaging, and convenient snack products is encouraging manufacturers to strengthen product innovation and expand their presence in China’s confectionery market.
U.K. Non-Chocolate Candy Market Insight
The U.K. non-chocolate candy market is experiencing steady growth, supported by sustained consumer demand for gummies, hard candies, mints, chewing gum, and other sugar confectionery products. Increasing availability of innovative confectionery products through supermarkets, convenience stores, specialist retailers, and e-commerce channels is contributing to market growth. Furthermore, growing interest in reduced-sugar formulations, vegan-friendly ingredients, and distinctive flavor combinations is encouraging manufacturers to diversify their product portfolios and respond to changing consumer preferences.
Germany Non-Chocolate Candy Market Insight
The Germany non-chocolate candy market is expanding steadily due to strong demand for confectionery products, established manufacturing capabilities, and a well-developed retail distribution network. Candy manufacturers are increasingly focusing on gummies, fruit-flavored sweets, mints, and sugar-reduced products to address evolving consumer preferences. Continuous advancements in product formulation, sustainable packaging, and flavor innovation, along with the growing availability of confectionery through online and offline retail channels, are further supporting market growth in Germany.
Which are the Top Companies in Non-Chocolate Candy Market?
The non-chocolate candy industry is primarily led by well-established companies, including:
- The Hershey Company (U.S.)
- Mondelēz International, Inc. (U.S.)
- Perfetti Van Melle (Italy)
- HARIBO GmbH & Co. KG (Germany)
- Mars, Incorporated (U.S.)
- Ferrara Candy Company (U.S.)
- Tootsie Roll Industries, Inc. (U.S.)
- The Bazooka Companies, Inc. (U.S.)
- Just Born, Inc. (U.S.)
- Jelly Belly Candy Company (U.S.)
- The American Licorice Company (U.S.)
- Spangler Candy Company (U.S.)
- Albanese Confectionery Group, Inc. (U.S.)
- Smarties Candy Company (U.S.)
- Adams and Brooks, Inc. (U.S.)
- Arcor S.A.I.C. (Argentina)
- Meiji Co., Ltd. (Japan)
- Morinaga & Co., Ltd. (Japan)
- Lotte Wellfood Co., Ltd. (South Korea)
What are Latest Developments in Non-Chocolate Candy Market?
- In March 2025, Mondelēz International announced the launch of SOUR PATCH KIDS Strawberry-Watermelon Glow Ups, an innovative gummy candy designed to glow under blacklight. The product features edible confetti containing turmeric extract, creating a fluorescent effect while retaining the brand’s signature sour-then-sweet flavor experience. The company also introduced Swedish Fish Mini Strawberry-Watermelon Glow Ups, extending the concept to another popular chewy candy brand. This launch highlights the growing focus on interactive confectionery experiences and distinctive product formats.
- In September 2024, The Hershey Company introduced Shaq-A-Licious XL Gummies in partnership with basketball star Shaquille O’Neal. Available in original and sour flavors, the oversized gummy candies were developed to bring a playful, celebrity-inspired concept to the non-chocolate confectionery category. The launch reflects Hershey’s strategy of expanding its sweets portfolio through distinctive product designs, flavor variations, and partnerships that appeal to consumers seeking new candy experiences. This development demonstrates continued innovation in the gummy candy segment.
- In May 2024, HI-CHEW announced the launch of HI-CHEW Gummies and HI-CHEW Gummies Sour at the Sweets & Snacks Expo. The products adapted the brand’s familiar fruity flavors into a gummy format, allowing the company to reach consumers who prefer different candy textures. The launch expanded HI-CHEW’s presence beyond its traditional chewy candy products and introduced both sweet and sour options. This product development illustrates how confectionery brands are diversifying established offerings to appeal to a broader range of consumer preferences.
- In July 2023, HARIBO of America opened its first U.S. factory and introduced Wild Berry Goldbears, expanding its manufacturing presence and product offering in the American market. The new gummy variety added a berry-inspired flavor profile to the company’s established Goldbears range. The factory opening represented an important step in HARIBO’s U.S. expansion, while the product launch strengthened its offering in the non-chocolate candy category. The development reflects continued investment in local production capacity and confectionery product innovation.
- In April 2021, HARIBO of America launched Funtastic Mix, a gummy candy assortment featuring eight flavors and more than fifteen playful shapes. The product combined multiple colors, flavors, and gummy textures, including double- and triple-flavored pieces, to create a more varied candy experience. Designed to appeal to consumers looking for fun and imaginative sweets, Funtastic Mix joined HARIBO’s existing product portfolio and became available through retailers across the United States. The launch highlighted the company’s emphasis on variety, visual appeal, and flavor innovation in the non-chocolate candy market.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Non Chocolate Candy Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Non Chocolate Candy Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Non Chocolate Candy Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.