What is the Optical Satellite Communication Market Size and Growth Rate?
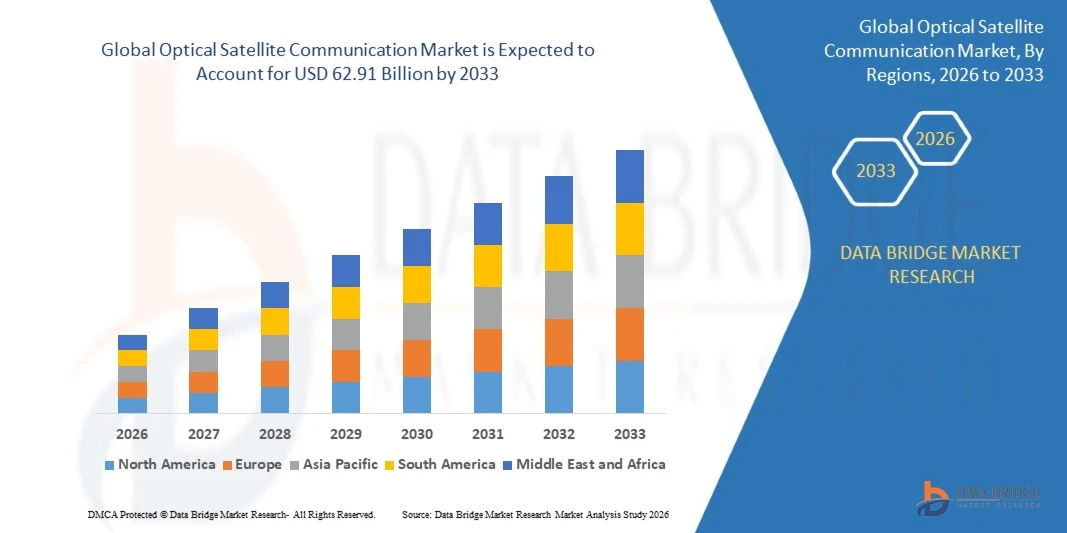
- As per Data Bridge Market Research analysis, the optical satellite communication market was valued at USD 13.42 billion in 2025 and is projected to reach USD 62.91 billion by 2033, growing at a CAGR of 21.3% from 2026 to 2033.
- The market is experiencing strong growth driven by rising demand for high-bandwidth, low-latency satellite connectivity, expanding low Earth orbit constellations, and increasing adoption across defense, commercial satellite operations, space agencies, telecommunications, and earth observation sectors.
- The increasing deployment of proliferated satellite constellations, growing data volumes from earth observation, and rising need for secure, interference-resistant links are supporting market adoption. Free-space optical technology is being applied across inter-satellite links, ground downlinks, deep space missions, and small satellite constellations, offering operators far greater throughput than conventional radio-frequency satellite communication systems.
Market Size & Forecast
- Global Market Value (2025): USD 13.42 Billion
- Expected Market Value (2033): USD 62.91 Billion
- Forecast CAGR (2026–2033): 21.3%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Optical Satellite Communication Market?
- North America dominated the optical satellite communication market with the largest revenue share of 41.37% in 2025, supported by large defense space programs, a strong commercial launch ecosystem, and early deployment of laser links across proliferated constellations.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 25.2% from 2026 to 2033, fueled by expanding national space programs, growing satellite constellation investments, and rising demand for secure high-capacity connectivity.
- The optical terminals segment led the market with a 73.40% share in 2025, driven by large-scale procurement of laser communication terminals for constellations and defense networks.
- Optical ground stations are the fastest-growing product type, projected to register a CAGR of 23.9%, reflecting the need for geographically diverse ground infrastructure to receive optical downlinks.
- The LEO segment dominated the orbit category with a 63.52% revenue share in 2025, led by proliferated constellations that require high-capacity inter-satellite meshes.
- Inter-satellite links accounted for 46.84% of the market share in 2025, preferred for building space-based mesh networks that reduce reliance on ground stations.
- The deep space communication segment is the fastest-growing application category, with a CAGR of 27.4%, driven by lunar and planetary mission requirements for high-rate data return.
Report Scope and Optical Satellite Communication Market Segmentation
|
Attributes |
Optical Satellite Communication Market Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the market insights such as market value, growth rate, market segments, geographical coverage, market players, and market scenario, the market report curated by the Data Bridge Market Research team includes in-depth expert analysis, import/export analysis, pricing analysis, production consumption analysis, and pestle analysis. |
What is the Key Trend in the Optical Satellite Communication Market?
- Optical satellite communication is evolving from technology demonstrations into operational infrastructure, with laser terminals enabling high-capacity inter-satellite meshes, space-to-ground downlinks, and data relay services across low Earth orbit, medium Earth orbit, and deep space.
- For instance, in January 2024, according to SpaceX, presenting at SPIE Photonics West, the Starlink constellation operated about 9,000 laser links carrying more than 42 petabytes of data per day, with each link sustaining 100 Gbps and link uptime exceeding 99%, demonstrating laser communication at commercial scale.
- Terminal makers are pushing data rates, power efficiency, and standardization higher, with SDA-compatible terminals increasingly adopted as an interoperability baseline across government and commercial constellations.
- Optical links are also moving beyond satellites, with aircraft-to-space demonstrations, optical data relay networks, and lunar missions using lasers to return large volumes of imagery and science data.
- For instance, in April 2024, according to Tesat, Tesat and MPB Communications demonstrated 100 Gbps transmission at 40 W optical output power over a simulated distance of more than 45,000 kilometres, compared with 1.8 Gbps at 2.2 W achieved by current LEO-to-GEO links on the European Data Relay Service.
- As terminal costs fall, production scales, and standards mature, optical satellite communication is expected to become the default backbone for high-throughput satellite networks, defense data transport, and next-generation space exploration.
What are the Key Drivers of the Optical Satellite Communication Market?
- Rapidly growing data volumes from earth observation, broadband constellations, and defense sensors are exceeding the capacity of radio-frequency links, increasing demand for high-throughput optical inter-satellite and downlink solutions.
- For instance, in March 2026, according to Breaking Defense, the U.S. Space Development Agency's Tranche 1 architecture comprises 154 satellites, including 126 data relay satellites in the Transport Layer and 28 missile warning and tracking satellites, which depend on laser links for high-speed data transport.
- Defense and government agencies are prioritizing secure, jam-resistant, low-probability-of-intercept communication, strengthening procurement of laser terminals for resilient space data networks and missile-tracking architectures.
- For instance, in December 2024, according to the European Space Agency (ESA), the European Commission and the SpaceRISE consortium signed a 12-year concession contract for the IRIS² multi-orbit constellation of approximately 300 satellites, with an earmarked budget of €10.6 billion, reinforcing sovereign investment in high-capacity space connectivity.
- Falling terminal costs, higher manufacturing volumes, and wider availability of standardized, interoperable terminals are making optical links viable for smaller satellites and commercial operators.
What Factors Are Challenging the Growth of the Optical Satellite Communication Market?
- Optical terminals require precise pointing, acquisition, and tracking, along with specialized photonic components, which increases engineering complexity and limits the number of qualified suppliers.
- For instance, in August 2024, according to Via Satellite, Mynaric disclosed production delays for its CONDOR Mk3 terminals caused by lower-than-expected yields and shortages of key components, cut its revenue guidance, and saw its chief executive step down, highlighting the manufacturing challenge of scaling laser terminals.
- Atmospheric conditions such as clouds and turbulence can interrupt space-to-ground optical links, requiring diverse ground station networks and backup radio-frequency systems, which raises infrastructure costs.
- Interoperability between terminals from different suppliers, export-control restrictions, and long qualification cycles for space hardware can delay deployments and slow adoption among new operators.
- For instance, in March 2026, according to Breaking Defense, the director of the Space Development Agency said the optical mesh network for Tranche 1 had not yet been established and that the agency was at least three months behind schedule in demonstrating satellite-to-satellite laser links, underscoring integration challenges.
- The combination of manufacturing yield risk, weather dependence, standardization gaps, and high upfront costs can constrain adoption among cost-sensitive operators and delay the transition from radio-frequency to optical networks.
How is the Optical Satellite Communication Market Segmented?
The optical satellite communication market is segmented on the basis of product, orbit, application, and end user.
- By Product
On the basis of product, the optical satellite communication market is segmented into optical terminals and optical ground stations. The optical terminals segment dominated the market with 73.40% share in 2025, supported by large-scale procurement of laser communication terminals for broadband constellations, defense data networks, and data relay satellites. Terminals combine telescopes, pointing mechanisms, lasers, and modems to establish high-rate links between spacecraft. Improvements in size, weight, power, and interoperability are expanding their use on smaller satellites. Rising production volumes and the entry of new suppliers are also improving availability and lowering costs for satellite manufacturers.
The optical ground stations segment is projected to register the fastest growth at a CAGR of 23.9% from 2026 to 2033, driven by the need for geographically diverse receiving sites that can maintain links despite cloud cover. Operators are building networks of ground telescopes and terminals linked through site-diversity schemes to improve availability. Government-funded networks, commercial ground-segment providers, and research institutions are investing in optical downlink infrastructure. Increasing data volumes from earth observation and deep space missions are further raising demand for dependable, high-capacity optical ground infrastructure.
- By Orbit
On the basis of orbit, the optical satellite communication market is segmented into LEO, MEO, and GEO. The LEO segment dominated the orbit category with 63.52% share in 2025, supported by the rapid deployment of proliferated constellations that rely on laser links to form low-latency space meshes. Optical links allow data to be routed between satellites without a ground station in view, improving coverage over oceans and remote regions. Defense transport layers, broadband networks, and earth observation constellations are major users. Falling launch costs and standardized terminals are encouraging operators to equip more satellites with optical links.
The MEO segment is projected to register the fastest growth at a CAGR of 25.8% from 2026 to 2033, supported by planned multi-orbit architectures and medium Earth orbit missile-tracking and data-network programs. MEO links span longer distances than LEO, creating demand for higher-power terminals and precise pointing. Multi-orbit constellations that combine LEO and MEO satellites rely on optical links to move data between layers. Sovereign connectivity programs and defense networks are expected to add new MEO nodes, creating additional demand for advanced optical terminals.
- By Application
On the basis of application, the optical satellite communication market is segmented into inter-satellite links, satellite-to-ground links, deep space communication, and others. The inter-satellite links segment dominated the application category with 46.84% share in 2025, supported by the need to build space-based mesh networks that move data across constellations with low latency. Laser crosslinks reduce dependence on ground stations and enable routing across continents and oceans. Defense transport networks and commercial broadband constellations are scaling these links. Standardization of terminals and improvements in acquisition and tracking are making crosslinks more reliable and affordable.
The deep space communication segment is projected to register the fastest growth at a CAGR of 27.4% from 2026 to 2033, driven by lunar and planetary missions that need to return high-resolution imagery, video, and science data. Laser links can deliver much higher data rates than radio from the same distance with smaller, lighter hardware. Crewed lunar missions and robotic probes are testing optical payloads alongside radio systems. Growing commercial activity near the Moon and plans for Mars exploration are creating long-term demand for optical deep space communication.
- By End User
On the basis of end user, the optical satellite communication market is segmented into defense and government, commercial satellite operators, space agencies, telecommunication providers, earth observation and remote sensing, and others. The defense and government segment dominated the end-user category with 43.17% share in 2025, supported by investment in resilient, secure, and jam-resistant space data networks. Military programs use laser links for missile warning and tracking, data transport, and command and control. Their preference for low-probability-of-intercept communication and high capacity strongly supports terminal procurement. Sovereign connectivity programs are further increasing government spending.
The commercial satellite operators segment is projected to register the fastest growth at a CAGR of 24.1% from 2026 to 2033, driven by broadband constellations, data relay services, and hosted payload networks. Operators are adopting optical links to increase capacity, improve latency, and reduce ground infrastructure costs. Commercial relay networks are also offering optical connectivity to third-party satellites and aircraft. Standardized terminals and growing supplier competition are lowering barriers for new entrants, supporting wider commercial adoption of optical communication.
Which Region Holds the Largest Share of the Optical Satellite Communication Market?
- North America dominated the optical satellite communication market with the largest revenue share of 41.37% in 2025, supported by large defense space programs, a strong commercial launch ecosystem, and early deployment of laser links across proliferated constellations.
- The region also benefits from substantial government funding for space networks, the presence of leading constellation operators and terminal suppliers, and active collaboration between space agencies, universities, and industry. Increasing use of optical links for defense data transport, commercial relay services, and lunar exploration continues to strengthen North America's position in the global market.
U.S. Optical Satellite Communication Market Insight
The U.S. optical satellite communication market is witnessing strong growth due to large-scale defense transport and tracking constellations, commercial broadband networks, and NASA-led optical communication demonstrations. The country's mature space industry, along with a deep base of terminal developers and launch providers, is driving demand for advanced laser terminals. In addition, growing emphasis on resilient, secure data transport and the expansion of commercial data relay networks are accelerating adoption of optical links across government and commercial applications.
Asia-Pacific Optical Satellite Communication Market Insight
The Asia-Pacific optical satellite communication market is expected to witness rapid growth, driven by expanding national space programs, growing investment in satellite constellations, and rising demand for secure high-capacity connectivity across countries such as China, India, and Japan. Growing earth observation activity, increasing launch capability, and government support for domestic space technology are supporting regional market expansion. In addition, rising interest in optical inter-satellite links and ground infrastructure is accelerating demand for laser communication solutions.
Japan Optical Satellite Communication Market Insight
The Japan optical satellite communication market is witnessing consistent growth due to strong capabilities in photonics and precision electronics, government support for space communication, and the participation of established electronics and aerospace companies. Domestic developers are working on laser communication terminals and data relay concepts for earth observation and commercial applications. Moreover, strong demand for reliability, compact hardware, and international collaboration on optical standards is further contributing to market growth in Japan.
China Optical Satellite Communication Market Insight
The China optical satellite communication market is growing rapidly, driven by expanding satellite constellations, active research in laser communication, and strong domestic manufacturing capacity. Growing use of satellites for broadband, earth observation, and navigation is significantly boosting demand for high-capacity links. In addition, sustained government investment in space infrastructure, increasing launch cadence, and progress in domestic photonic components are positioning China as a key growth market for optical satellite communication across Asia-Pacific.
U.K. Optical Satellite Communication Market Insight
The U.K. optical satellite communication market is experiencing steady growth, supported by government investment in space and defense communication, an active satellite manufacturing sector, and collaboration with European and international partners. Companies, universities, and research institutions are developing optical ground stations and laser communication technologies. Furthermore, growing interest in secure, resilient connectivity and participation in multinational space programs is supporting wider adoption of optical satellite communication in the U.K.
Germany Optical Satellite Communication Market Insight
The Germany optical satellite communication market is expanding steadily due to the country's strong aerospace and photonics base and the presence of established laser terminal developers. Manufacturers, research institutes, and space agencies are advancing optical terminals for data relay, constellations, and defense applications. Continuous advancements in terminal performance, participation in European sovereign connectivity programs, and Germany's focus on precision engineering and secure communication are further driving market growth in the country.
Which are the Top Companies in Optical Satellite Communication Market?
The optical satellite communication market industry is primarily led by well-established companies, including:
- SpaceX (U.S.)
- Tesat-Spacecom GmbH & Co. KG (Germany)
- Mynaric AG (Germany)
- CACI International Inc. (U.S.)
- Kepler Communications Inc. (Canada)
- Rocket Lab USA, Inc. (U.S.)
- General Atomics Electromagnetic Systems (U.S.)
- Northrop Grumman Corporation (U.S.)
- Lockheed Martin Corporation (U.S.)
- York Space Systems (U.S.)
- Airbus SE (Netherlands)
- Thales Alenia Space (France)
- Honeywell International Inc. (U.S.)
- L3Harris Technologies, Inc. (U.S.)
- Mitsubishi Electric Corporation (Japan)
- NEC Corporation (Japan)
- Sony Group Corporation (Japan)
- BAE Systems plc (U.K.)
- Viasat, Inc. (U.S.)
- Space Compass Corporation (Japan)
What are Latest Developments in Optical Satellite Communication Market
- In August 2026, Kepler Communications announced that service on its optical data relay constellation is now active, following the January 2026 launch of ten satellites carrying SDA-compatible optical terminals, enabling customers in earth observation, defense, and space domain awareness to access real-time connectivity, with future tranches planned to support data rates up to 100 Gbps.
- In July 2026, the U.S. Space Development Agency resumed launches of its Tranche 1 Transport Layer data relay satellites, with 21 satellites scheduled to launch on a SpaceX Falcon 9 following technology fixes, as the agency works to establish the optical mesh network at the core of its Proliferated Warfighter Space Architecture.
- In April 2026, NASA flew the Orion Artemis II Optical Communications System (O2O), developed with MIT Lincoln Laboratory, on the Artemis II lunar mission, using infrared laser links to return high-definition imagery and data at rates of up to 260 Mbps alongside conventional radio systems.
- In September 2025, York Space Systems announced the successful demonstration of a space-to-ground optical laser communication link between a Tranche 0 satellite and a Space Development Agency optical ground terminal, with more than 1.5 million frames successfully received, advancing the agency's Transport Layer.
- In March 2025, Rocket Lab announced its intention to acquire laser terminal supplier Mynaric, which provides CONDOR Mk3 terminals for Rocket Lab's USD 515 million Space Development Agency contract to produce 18 Tranche 2 Transport Layer Beta satellites, with the aim of scaling production of optical communication terminals.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.