What is the Paper Core Market Size and Growth Rate?
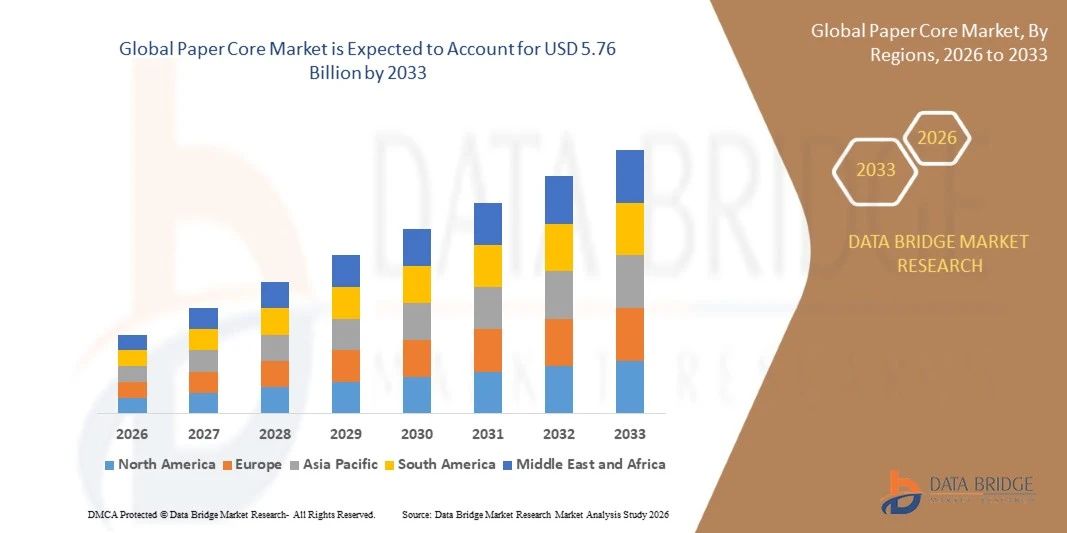
- As per Data Bridge Market Research analysis, the paper core market was valued at USD 3.92 billion in 2025 and is projected to reach USD 5.76 billion by 2033, growing at a CAGR of 4.95% from 2026 to 2033.
- The market is experiencing consistent growth driven by rising demand for roll-based materials, increasing replacement of plastic and metal cores with recyclable fiber-based alternatives, and expanding use of cores across paper, film, tape, textile, and label manufacturing.
- The increasing shift toward sustainable packaging, growth in e-commerce and flexible packaging production, and rising output of tissue, film, and technical textiles are supporting market adoption. Paper cores are being applied across recycled paperboard winding, flexible packaging film rolls, and e-commerce packaging materials, offering converters a strong, lightweight, and recyclable support for winding, storing, and transporting rolled goods.
Market Size & Forecast
- Global Market Value (2025): USD 3.92 Billion
- Expected Market Value (2033): USD 5.76 Billion
- Forecast CAGR (2026–2033): 4.95%
What are the Major Takeaways of Paper Core Market?
- Asia-Pacific dominated the paper core market with the largest revenue share of 46.50% in 2025, supported by large paper, film, textile, and packaging production bases, and rising consumption of roll-based materials across China, India, and Southeast Asia.
- Asia-Pacific is also expected to be the fastest-growing region at a CAGR of 5.80% from 2026 to 2033, fueled by flexible packaging capacity additions, expanding textile and nonwoven output, and growth in online retail.
- The spiral wound segment led the product category with a 62.10% share in 2025, driven by its versatility, strength, and cost-efficiency across a wide range of diameters and wall thicknesses.
- Parallel wound cores are the fastest-growing product type, projected to register a CAGR of 6.20%, reflecting demand for tight tolerances and smooth surfaces in precision film, label, and tape winding.
- The recycled paperboard segment dominated the material category with a 71.30% revenue share in 2025, led by cost advantages, circular-economy goals, and wide availability of recovered fiber.
- Paper and printing accounted for 33.50% of the market share in 2025, preferred for the large volumes of heavy-duty mill cores used to wind paper, tissue, and board rolls.
- The plastic film and foil winding segment is the fastest-growing application category, with a CAGR of 6.00%, driven by growing output of flexible packaging and thinner film gauges that need precise cores.
Report Scope and Paper Core Market Segmentation
|
Attributes |
Paper Core Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, pricing analysis, brand share analysis, consumer survey, demography analysis, supply chain analysis, value chain analysis, raw material/consumables overview, vendor selection criteria, PESTLE Analysis, Porter Analysis, and regulatory framework. |
What is the Key Trend in the Paper Core Market?
- Paper core suppliers are tightening their link between recycled paperboard mills and core converting plants, so that coreboard availability, quality, and cost can be managed together as demand for roll-based materials grows and mill capacity runs at high utilization.
- For instance, in June 2026, according to Sonoco Products Company, it announced a USD 60 per ton increase for all grades of uncoated recycled paperboard in the United States and Canada and a 7% increase for converted paperboard products including tubes and cores, citing robust demand and strong utilization across its paper mill network.
- Integration of coreboard production with converting is increasingly viewed as a way to secure supply, control quality for precision applications, and respond faster to customers in film, tape, and paper winding.
- For instance, in August 2019, according to Sonoco Products Company, it completed the acquisition of Corenso Holdings America for about USD 110 million, adding a 108,000-ton per year uncoated recycled paperboard mill in Wisconsin and two core converting facilities with about 175 employees.
- As sustainability goals, thinner film gauges, and e-commerce volumes continue to shape roll-based production, paper core suppliers are expected to invest further in integrated recycled paperboard capacity, engineered multi-ply cores, and tighter tolerances.
What are the Key Drivers of the Paper Core Market?
- The rising output of paper, tissue, flexible packaging film, tape, and textiles has significantly increased demand for cores, since nearly every rolled product needs a strong and dimensionally stable core for winding, storage, and shipping.
- For instance, in March 2026, according to Sonoco Products Company, tightening market conditions and increased mill utilization rates led it to implement a USD 70 per ton price increase for all grades of uncoated recycled paperboard in the United States and Canada, effective April 2026.
- Paper, packaging, textile, and label manufacturers are increasingly choosing fiber-based cores because they are recyclable, widely available, and can be engineered for different wall thicknesses, diameters, and load requirements.
- For instance, in May 2019, according to NS Packaging, Cascades Sonoco, a joint venture of Cascades and Sonoco Products Company, opened an expanded facility in Birmingham, Alabama, adding regional capacity to serve demand for paperboard-based tubes, cores, and related products.
- With e-commerce, flexible packaging, and industrial film production continuing to expand, paper cores remain the standard winding support, sustaining steady replacement and growth demand across end-use industries.
What Factors Are Challenging the Growth of the Paper Core Market?
- Paper cores depend on recovered paper, energy, adhesives, and freight, which exposes producers to input-cost inflation and tight coreboard supply when mills operate at high utilization.
- For instance, in March 2026, according to Sonoco Products Company, inflationary input costs led it to raise prices for all converted paperboard products, including tubes, cores, cones, and partitions, by 8%, effective April 15, 2026.
- These cost pressures can squeeze converter margins, trigger contract renegotiations, and push cost-sensitive buyers to consider alternatives such as plastic or composite cores or to reduce core wall thickness.
- Cores are also a low-value, high-volume product with significant freight costs, which limits the distance over which producers can serve customers competitively and keeps the market regional in nature.
- For instance, in June 2026, according to Sonoco Products Company, elevated inflationary pressures significantly increased its operating costs, prompting a further 7% increase for converted paperboard products, including tubes and cores, effective July 8, 2026.
- The combination of repeated price adjustments, input-cost volatility, and competition from alternative core materials can constrain adoption among cost-sensitive converters, particularly in low-margin commodity applications.
How is the Paper Core Market Segmented?
The paper core market is segmented on the basis of product type, material grade, application, and end user.
- By Product Type
On the basis of product type, the paper core market is segmented into spiral wound, convolute wound, parallel wound, and others. The spiral wound segment dominated the market with 62.10% share in 2025, supported by its versatility across a wide range of diameters, lengths, and wall thicknesses. Spiral winding allows continuous production of long cores with strong, consistent walls. Plants can switch between sizes quickly, which keeps lead times short for customers. The method suits heavy-duty mill cores as well as lighter film and tape cores. Established equipment and low production cost further strengthen demand.
The parallel wound segment is projected to register the fastest growth at a CAGR of 6.20% from 2026 to 2033, driven by demand for tight dimensional tolerances and smooth surfaces in precision winding. Thin films, labels, and pressure-sensitive tapes can be marked or deformed by uneven cores. Parallel winding yields a consistent inner diameter and surface finish. Converters of premium films are increasingly specifying these cores to reduce roll defects. Growth in high-speed converting lines is creating additional demand.
- By Material Grade
On the basis of material grade, the paper core market is segmented into recycled paperboard, virgin kraft paper, and specialty and laminated paper. The recycled paperboard segment dominated the market with 71.30% share in 2025, supported by cost advantages, circular-economy goals, and wide availability of recovered fiber. Cores made from uncoated recycled paperboard are readily recyclable at the end of the roll’s life. Integrated mills allow producers to control coreboard strength and moisture. Brand owners and converters increasingly favor recycled content to meet environmental targets.
The specialty and laminated paper segment is projected to register the fastest growth at a CAGR of 6.40% from 2026 to 2033, driven by demand for higher crush resistance, moisture protection, and cleaner surfaces. Specialty grades are used where cores must carry heavy rolls or resist humidity during shipping. Laminated constructions can add strength without increasing wall thickness. Film and textile producers are adopting these cores to protect product quality. Ongoing development of barrier and coated grades is widening the application range.
- By Application
On the basis of application, the paper core market is segmented into paper and printing, plastic film and foil winding, textile and yarn winding, adhesive tapes and labels, and others. The paper and printing segment dominated the application category with 33.50% share in 2025, supported by the large volumes of heavy-duty mill cores used to wind paper, tissue, newsprint, and board. Mill cores must withstand high winding tension and rough handling. Tissue and towel producers use large numbers of cores for parent and finished rolls. Consistent demand from established paper mills provides stable volume.
The plastic film and foil winding segment is projected to register the fastest growth at a CAGR of 6.00% from 2026 to 2033, driven by growth in flexible packaging, stretch film, shrink film, and aluminum foil production. Thinner film gauges expose defects from dust or uneven cores, so converters require cleaner, more precise cores. Expanding packaging capacity in emerging economies is increasing demand. Growth in e-commerce raises consumption of stretch and protective films. Customized core designs help reduce roll damage during transport.
- By End User
On the basis of end user, the paper core market is segmented into packaging and converting, paper and pulp, textiles, chemicals and plastics, and others. The packaging and converting segment dominated the end-user category with 37.40% share in 2025, supported by the wide use of rolled films, foils, labels, and laminates in food, consumer goods, and logistics packaging. Converters value cores that run smoothly on high-speed equipment. Demand follows growth in flexible packaging and label production. Recyclability supports the sustainability claims of packaged-goods brands.
The chemicals and plastics segment is projected to register the fastest growth at a CAGR of 5.90% from 2026 to 2033, driven by rising output of industrial films, geomembranes, nonwovens, and technical sheet materials. These producers need strong and stable cores for wide and heavy rolls. Increasing demand for agricultural, construction, and hygiene films is creating further volume. Producers are seeking local supply to reduce freight and lead times. Quality requirements are encouraging closer supplier partnerships.
Which Region Holds the Largest Share of the Paper Core Market?
- Asia-Pacific dominated the paper core market with the largest revenue share of 46.50% in 2025, supported by large-scale paper, film, textile, and packaging production across China, India, Japan, and Southeast Asia.
- The region also benefits from rapid growth in online retail, expanding flexible packaging capacity, and a broad base of recycled paperboard and tube manufacturers. Rising demand for locally produced, lightweight, and recyclable cores continues to strengthen Asia-Pacific’s position in the global market.
U.S. Paper Core Market Insight
The U.S. paper core market is witnessing steady growth due to strong demand from paper and tissue mills, flexible packaging converters, adhesive tape producers, and e-commerce related film consumption. The country’s integrated base of recycled paperboard mills and core converting plants, led by large domestic producers, supports reliable supply across regional markets. In addition, repeated price adjustments for recycled paperboard and converted products reflect strong mill utilization and are shaping contracting and sourcing strategies across the U.S. industry.
Asia-Pacific Paper Core Market Insight
The Asia-Pacific paper core market is expected to witness rapid growth, driven by large-scale paper, film, and textile production, expanding flexible packaging capacity, and rising online retail across countries such as China, India, and Japan. Growing demand for lightweight, recyclable, and cost-effective winding supports is supporting regional market expansion. In addition, the region’s extensive manufacturing base and availability of recovered paper are accelerating demand for locally produced paper cores across packaging, textile, and industrial applications.
Japan Paper Core Market Insight
The Japan paper core market is witnessing consistent growth due to demand from high-quality film, label, and tape manufacturers that require precise and clean winding supports. Paper and packaging companies, textile producers, and specialty material makers are increasingly specifying cores with tight tolerances and consistent strength. Moreover, strong demand for reliability, recycling, and efficient logistics is further contributing to market growth in Japan.
China Paper Core Market Insight
The China paper core market is growing rapidly, driven by massive output of paper, plastic film, textiles, and packaging materials, together with a large domestic network of paperboard and tube producers. Growing use of cores in e-commerce packaging films, hygiene products, and industrial sheet materials is significantly boosting market demand. In addition, strong local manufacturing capacity, competitive pricing, and investment in recycled fiber supply are positioning China as a key growth market for paper cores across Asia-Pacific.
U.K. Paper Core Market Insight
The U.K. paper core market is experiencing steady growth, supported by demand from paper and tissue producers, film converters, label printers, and food packaging manufacturers. Producers and converters are increasingly focusing on recyclable fiber-based products to meet packaging sustainability commitments. Furthermore, regional supply from integrated tube and core manufacturers, together with efficient logistics within Europe, is supporting wider use of paper cores in the U.K.
Germany Paper Core Market Insight
The Germany paper core market is expanding steadily due to the country’s strong paper, packaging, and technical textile industries and its well-developed recycling system that supplies recovered fiber. Paper mills, film extruders, and converters are increasingly utilizing high-strength and precision cores to support efficient high-speed production. Continuous advancements in coreboard quality, a strong focus on circular economy practices, and robust industrial demand are further driving market growth in the country.
Which are the Top Companies in Paper Core Market?
The paper core industry is primarily led by well-established companies, including:
- Sonoco Products Company (U.S.)
- Greif, Inc. (U.S.)
- Smurfit Westrock plc (Ireland)
- Cascades Inc. (Canada)
- Yazoo Mills, Inc. (U.S.)
- Caraustar Industries, Inc. (U.S.)
- Ox Paper Tube and Core, Inc. (U.S.)
- Visy Industries (Australia)
- Rengo Co., Ltd. (Japan)
What are Latest Developments in Paper Core Market?
- In June 2026, Sonoco Products Company announced a USD 60 per ton price increase for all grades of uncoated recycled paperboard in the United States and Canada, effective July 8, 2026, together with a 7% increase for converted paperboard products including tubes, cores, cones, and partitions.
- In March 2026, Sonoco Products Company announced a USD 70 per ton price increase for all grades of uncoated recycled paperboard in the United States and Canada, effective April 3, 2026, and an 8% increase for converted paperboard products effective April 15, 2026.
- In August 2019, Sonoco Products Company completed the acquisition of Corenso Holdings America for about USD 110 million in cash, adding a 108,000-ton per year uncoated recycled paperboard mill and two core converting facilities in the U.S.
- In May 2019, Cascades Sonoco, a joint venture of Cascades and Sonoco Products Company, opened an expanded facility in Birmingham, Alabama, U.S., to increase regional capacity.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Paper Core Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Paper Core Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Paper Core Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.