What is the Tarpaulin Sheets Market Size and Growth Rate?
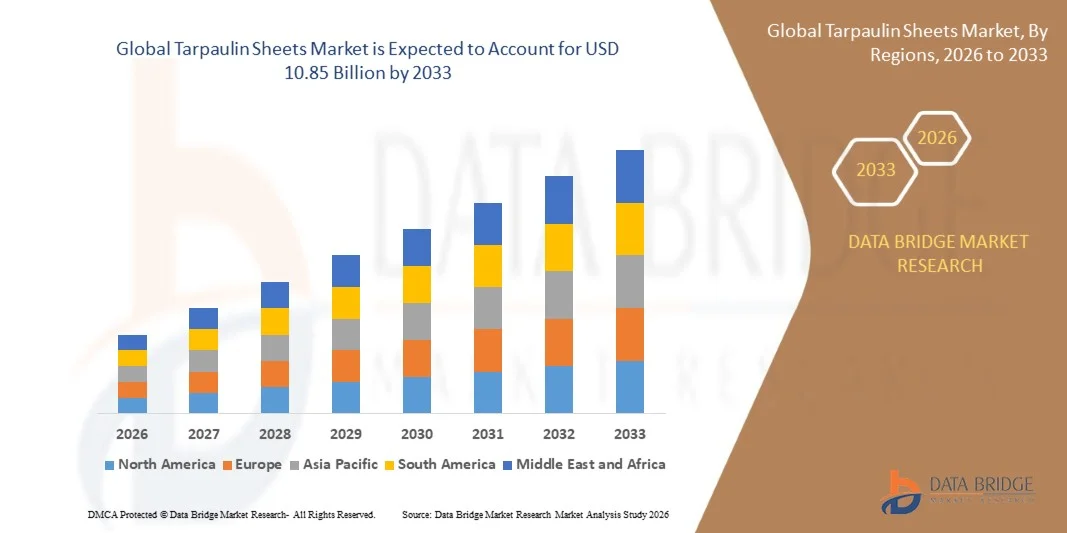
- As per Data Bridge Market Research analysis, the tarpaulin sheets market was valued at USD 7.40 Billion in 2025 and is projected to reach USD 10.85 Billion by 2033, growing at a CAGR of 4.90% from 2026 to 2033.
- The market is experiencing steady growth driven by expanding construction and infrastructure activity across developing economies, rising agricultural reliance on tarpaulins for crop protection and storage, and growing warehousing and logistics volumes that require efficient goods protection during transportation and storage.
- Rising investment in sustainable polymer manufacturing technologies and increasing demand for UV-resistant, multilayer protective covers are strengthening the value proposition of tarpaulin sheets across construction, agriculture, and industrial covering applications worldwide.
Market Size & Forecast
- Global Market Value (2025): USD 7.40 Billion
- Expected Market Value (2033): USD 10.85 Billion
- Forecast CAGR (2026–2033): 4.90%
- Leading Region in 2025: Asia-Pacific
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Tarpaulin Sheets Market?
- Asia-Pacific dominated the global tarpaulin sheets market with the largest revenue share of 34.00% in 2025, supported by extensive construction activity, large-scale agricultural operations, and a well-established manufacturing base for polymer-based protective coverings.
- Asia-Pacific holds both the largest share and the fastest growth trajectory in the market, with India recording the fastest country-level expansion at a CAGR of 6.40% through 2033, driven by rapid infrastructure development and expanding logistics networks.
- The construction application segment led the market with a 42.00% share in 2025, driven by rising infrastructure investment and sustained demand for temporary shelters, scaffolding covers, and site protection materials.
- The laminated tarpaulin product type segment dominated the market with a 48.00% share in 2025, owing to its superior tear resistance, waterproofing performance, and extended service life compared with non-laminated alternatives.
- The HDPE woven material segment held a 52.00% share in 2025, reflecting its widespread adoption for its lightweight structure, durability, and cost-effective manufacturing process.
- The 100-250 GSM weight band accounted for a 38.00% share in 2025, representing the standard weight range for general-purpose construction, agricultural, and transportation covering applications.
- The direct sales channel commanded a 58.00% share of the sales-channel mix in 2025, reflecting large-volume procurement relationships between manufacturers and commercial, industrial, and government buyers.
Report Scope and Tarpaulin Sheets Market Segmentation
|
Attributes |
Tarpaulin Sheets Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, pricing analysis, brand share analysis, consumer survey, demography analysis, supply chain analysis, value chain analysis, raw material/consumables overview, vendor selection criteria, PESTLE Analysis, Porter Analysis, and regulatory framework. |
What is the Key Trend in the Tarpaulin Sheets Market?
- Manufacturers are shifting production toward laminated, multilayer tarpaulin constructions that combine tear resistance with extended waterproofing performance for demanding outdoor applications.
- In July 2026, Packaging Market Insights published an updated global forecast confirming laminated tarpaulin holds a 48.00% share of the product type segment and HDPE woven material holds a 52.00% share, reflecting the industry's decisive shift toward higher-performance, multilayer constructions.
- Manufacturers are relocating and expanding production capacity across Southeast Asian manufacturing hubs to serve rising regional construction and export demand at competitive cost structures.
- In 2025, leading Vietnam-based manufacturers including Tan Dai Hung Plastic, Gia Loi, and K-TARP VINA expanded production capacity to serve rising domestic construction demand and growing export orders to North America and Europe.
- Manufacturers commit to expanding laminated, UV-treated, and recyclable product lines as construction and logistics buyers prioritize durability and sustainability, establishing multilayer construction as the core innovation trend across the market.
What are the Key Drivers of the Tarpaulin Sheets Market?
- Expanding construction and infrastructure activity in developing economies drives sustained demand for durable, cost-effective covering materials across residential, commercial, and government construction sites.
- In 2025, India recorded the fastest country-level expansion in the tarpaulin sheets market at a CAGR of 6.40% through 2033, driven by rapid infrastructure development, expanding logistics networks, and government-backed housing and highway construction programs.
- Rising agricultural sector reliance on tarpaulins for crop protection, grain storage, and greenhouse covering strengthens baseline demand across both developed and emerging agricultural economies.
- In 2025, East Asia held the leading 34.00% share of regional tarpaulin sheets demand, driven by large-scale agricultural operations, extensive construction activity, and a well-established polymer manufacturing base across China, Japan, and South Korea.
- Sustained infrastructure investment, agricultural expansion, and logistics network growth position tarpaulin sheets as a core protective material with durable, multi-year demand across construction, agriculture, and transportation sectors.
Which Factors are Challenging the Growth of the Tarpaulin Sheets Market?
- Volatility in polymer feedstock prices, particularly for polyethylene and PVC resins, creates margin pressure for manufacturers operating on thin per-unit economics.
- Tightening environmental regulations on single-use and non-recyclable plastic products require manufacturers to invest in alternative, recyclable material formulations, adding cost and complexity to product development.
- Price-based competition among a fragmented base of regional manufacturers, particularly across Southeast Asia, compresses margins even as unit volumes expand.
- Rising polymer feedstock volatility, tightening plastic packaging regulations, and fragmented, price-driven competition together restrain margin expansion across the tarpaulin sheets value chain despite strong underlying demand growth.
How is the Tarpaulin Sheets Market Segmented?
The tarpaulin sheets market is segmented on the basis of material type, product type, weight/GSM range, application, color/finish, end use, sales channel, thickness range, reinforcement type, and packaging format.
- By Material Type
On the basis of material type, the global tarpaulin sheets market is segmented into HDPE woven, LDPE, polyvinyl chloride (PVC), canvas/cotton, and polypropylene (PP). The HDPE woven segment dominated the market with a 52.00% share in 2025, driven by its lightweight structure, moisture resistance, flexibility, and cost-effective manufacturing process for industrial and agricultural applications.
The polyvinyl chloride (PVC) segment registers the fastest growth at a CAGR of 6.10% from 2026 to 2033, driven by its superior chemical resistance and rising adoption in heavy-duty transportation and logistics covering applications.
- By Product Type
On the basis of product type, the global tarpaulin sheets market is segmented into laminated tarpaulin, coated tarpaulin, mesh tarpaulin, and insulated tarpaulin. The laminated tarpaulin segment dominated the market with a 48.00% share in 2025, owing to its superior tear resistance, waterproofing performance, and extended service life across construction and transportation applications.
The insulated tarpaulin segment registers the fastest growth at a CAGR of 6.80% from 2026 to 2033, driven by rising demand for temperature-controlled covering solutions in cold-chain logistics and industrial storage applications.
- By Weight/GSM Range
On the basis of weight/GSM range, the global tarpaulin sheets market is segmented into below 100 GSM, 100-250 GSM, 251-400 GSM, and above 400 GSM. The 100-250 GSM segment dominated the market with a 38.00% share in 2025, representing the standard weight range for general-purpose construction, agricultural, and transportation covering applications.
The above 400 GSM segment registers the fastest growth at a CAGR of 6.50% from 2026 to 2033, driven by rising demand for heavy-duty industrial and defense-grade covers requiring maximum durability and puncture resistance.
- By Application
On the basis of application, the global tarpaulin sheets market is segmented into construction, agriculture, automobiles & transportation, storage & warehousing & logistics, and industrial covers. The construction segment dominated the market with a 42.00% share in 2025, driven by rising infrastructure investment and sustained demand for temporary shelters, scaffolding covers, and site protection materials.
The storage & warehousing & logistics segment registers the fastest growth at a CAGR of 6.90% from 2026 to 2033, driven by expanding e-commerce fulfillment infrastructure and rising demand for weatherproof cargo and pallet covers.
- By Color/Finish
On the basis of color/finish, the global tarpaulin sheets market is segmented into single-colored, multi-colored/printed, and UV-treated. The single-colored segment dominated the market with a 61.00% share in 2025, reflecting its widespread use across standard commercial and industrial covering applications where branding is not a priority.
The UV-treated segment registers the fastest growth at a CAGR of 6.30% from 2026 to 2033, driven by rising demand for long-term outdoor covering solutions in regions with intense sun exposure.
- By End Use
On the basis of end use, the global tarpaulin sheets market is segmented into commercial & industrial, residential, and government & defense. The commercial & industrial segment dominated the market with a 44.00% share in 2025, driven by large-volume procurement from construction firms, logistics operators, and manufacturing facilities.
The government & defense segment registers the fastest growth at a CAGR of 6.60% from 2026 to 2033, driven by rising procurement of heavy-duty, weather-resistant covers for military equipment, temporary shelters, and disaster relief operations.
- By Sales Channel
On the basis of sales channel, the global tarpaulin sheets market is segmented into direct sales, distributors & wholesalers, online/e-commerce, and retail stores. The direct sales segment commanded a 58.00% share in 2025, reflecting large-volume procurement relationships between manufacturers and commercial, industrial, and government buyers.
The online/e-commerce segment registers the fastest growth at a CAGR of 8.10% from 2026 to 2033, driven by rising digital procurement adoption among small contractors, farmers, and individual consumers.
- By Thickness Range
On the basis of thickness range, the global tarpaulin sheets market is segmented into light duty, medium duty, and heavy duty. The medium duty segment dominated the market with a 47.00% share in 2025, offering a practical balance of durability and cost for general construction, agricultural, and transportation applications.
The heavy duty segment registers the fastest growth at a CAGR of 6.70% from 2026 to 2033, driven by rising demand from industrial and defense end users requiring maximum tear and puncture resistance.
- By Reinforcement Type
On the basis of reinforcement type, the global tarpaulin sheets market is segmented into ripstop reinforced, grommet-reinforced, and non-reinforced. The grommet-reinforced segment dominated the market with a 54.00% share in 2025, reflecting its widespread use for secure tie-down applications across construction, transportation, and agricultural covering needs.
The ripstop reinforced segment registers the fastest growth at a CAGR of 6.40% from 2026 to 2033, driven by rising demand for tear-resistant covers in high-wind and heavy-load transportation applications.
- By Packaging Format
On the basis of packaging format, the global tarpaulin sheets market is segmented into rolls, pre-cut sheets, and custom-fabricated covers. The pre-cut sheets segment dominated the market with a 49.00% share in 2025, reflecting strong demand for ready-to-use covering solutions across construction and agricultural applications.
The custom-fabricated covers segment registers the fastest growth at a CAGR of 7.20% from 2026 to 2033, driven by rising demand for application-specific covers tailored to industrial equipment, vehicles, and specialized storage requirements.
Which Region Holds the Largest Share of the Tarpaulin Sheets Market?
- Asia-Pacific dominated the tarpaulin sheets market and accounted for the largest revenue share of 34.00% in 2025, driven by extensive construction activity, large-scale agricultural operations, and a well-established manufacturing base for polymer-based protective coverings across China, Japan, India, and Vietnam.
- The region combines the largest current market share with the fastest regional growth trajectory, supported by rising infrastructure investment, expanding export-oriented manufacturing capacity, and growing e-commerce logistics infrastructure that drives sustained demand for protective covering materials.
China Tarpaulin Sheets Market Insight
The China tarpaulin sheets market grows steadily, supported by the country's extensive construction sector and its position as a major global manufacturing hub for polymer-based protective coverings. Domestic manufacturers, including Zhejiang MSD Group and Fulin Plastic Industry, expand production capacity to serve both domestic construction demand and growing export volumes.
India Tarpaulin Sheets Market Insight
The India tarpaulin sheets market records the fastest country-level growth globally at a CAGR of 6.40% through 2033, driven by rapid infrastructure development, expanding highway and housing construction programs, and rising agricultural mechanization requiring crop protection and storage coverings.
Vietnam Tarpaulin Sheets Market Insight
The Vietnam tarpaulin sheets market expands rapidly, anchored by a concentrated base of export-oriented manufacturers, including Tan Dai Hung Plastic, Gia Loi, and K-TARP VINA, that serve rising domestic construction demand alongside growing export orders to North America and Europe.
U.S. Tarpaulin Sheets Market Insight
The U.S. tarpaulin sheets market grows steadily, supported by robust demand from the construction and logistics sectors and rising adoption of PVC tarpaulin sheets in transportation and freight-covering applications. Leading manufacturers, including Seaman Corporation and SKAPS Industries, expand product lines to serve industrial and agricultural buyers.
Germany Tarpaulin Sheets Market Insight
The Germany tarpaulin sheets market grows steadily, supported by the country's advanced polymer manufacturing base and strong demand from construction and industrial covering applications. Leading domestic manufacturers, including Heytex Group and Mehler Texnologies, invest in laminated and recyclable product lines to meet tightening European Union sustainability regulations.
Which are the Top Companies in Tarpaulin Sheets Market?
The tarpaulin sheets industry is primarily led by well-established companies, including:
- Heytex Group (Germany)
- Sioen Industries NV (Belgium)
- Serge Ferrari Group (France)
- Hiraoka & Co., Ltd. (Japan)
- Seaman Corporation (U.S.)
- Mehler Texnologies (Germany)
- SKAPS Industries (U.S.)
- THRACE PLASTICS Co. (Greece)
- Tan Dai Hung Plastic JSC (Vietnam)
- Rhino Textile Products (U.K.)
- Canadian Tarpaulin Manufacturers Ltd. (Canada)
- Tarpaulins India (India)
- Zhejiang MSD Group (China)
- Fulin Plastic Industry Co., Ltd. (China)
- Gia Loi JSC (Vietnam)
What are Latest Developments in Tarpaulin Sheets Market?
- In July 2026, Packaging Market Insights published an updated global forecast confirming laminated tarpaulin holds a 48.00% share of the product type segment, HDPE woven material holds a 52.00% share, and direct sales secures a 58.00% share of the sales-channel mix, profiling more than 120 industry participants across 35 countries.
- In 2025, leading Vietnam-based manufacturers, including Tan Dai Hung Plastic, Gia Loi, and K-TARP VINA, expanded production capacity to serve rising domestic construction demand and growing export orders to North America and Europe.
- In August 2025, North America Tarpaulin Sheets industry data confirmed the region maintains steady demand growth from the construction and logistics sectors, with a compound annual growth rate of 3.20% recorded for the 2024-2031 forecast window.
- In 2025, manufacturers across the industry increased investment in sustainable polymer manufacturing technologies and recyclable material formulations to align with tightening plastic packaging regulations in the European Union and North America.
- In 2025, industry analysis confirmed East Asia holds the leading 34.00% share of regional tarpaulin sheets demand, with India recording the fastest country-level expansion at a CAGR of 6.40% through 2036.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Global Tarpaulin Sheets Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Global Tarpaulin Sheets Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Global Tarpaulin Sheets Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.