Mexico Pet Care Products Market Overview
The Mexico pet care products market was valued at USD 1.10 billion in 2025 and is projected to reach USD 1.71 billion by 2033, growing at a CAGR of 5.9% from 2026 to 2033. The market is experiencing steady expansion due to increasing pet ownership, rising disposable income, and growing awareness regarding pet health and wellness. Mexican consumers are increasingly treating pets as family members, leading to higher spending on premium food, grooming products, supplements, and preventive healthcare solutions.
The growing demand for natural and high-quality pet products is encouraging manufacturers to introduce specialized diets, functional supplements, and advanced care solutions. Increasing veterinary awareness and regular health checkups are also contributing to market growth. Additionally, the expansion of e-commerce platforms has improved access to a wide range of pet care products, especially in urban and emerging markets.
Dogs represent a major share of pet ownership in Mexico, while cat adoption is growing rapidly due to changing lifestyles. Overall, rising pet humanization, product innovation, and improved distribution networks are expected to support continued growth of the Mexico pet care products market during the forecast period.
Key Market Trends & Insights
- The Mexico pet care products market is driven by changing consumer preferences and increasing investment in pet well-being. Pet owners are becoming more focused on preventive healthcare, high-quality nutrition, and grooming solutions, creating strong demand for premium products. The market is also benefiting from the expansion of veterinary services, retail outlets, and online shopping platforms. Growing awareness about pet diseases and the availability of innovative products are further supporting market development. These factors are expected to create significant growth opportunities for domestic and international pet care companies in Mexico.
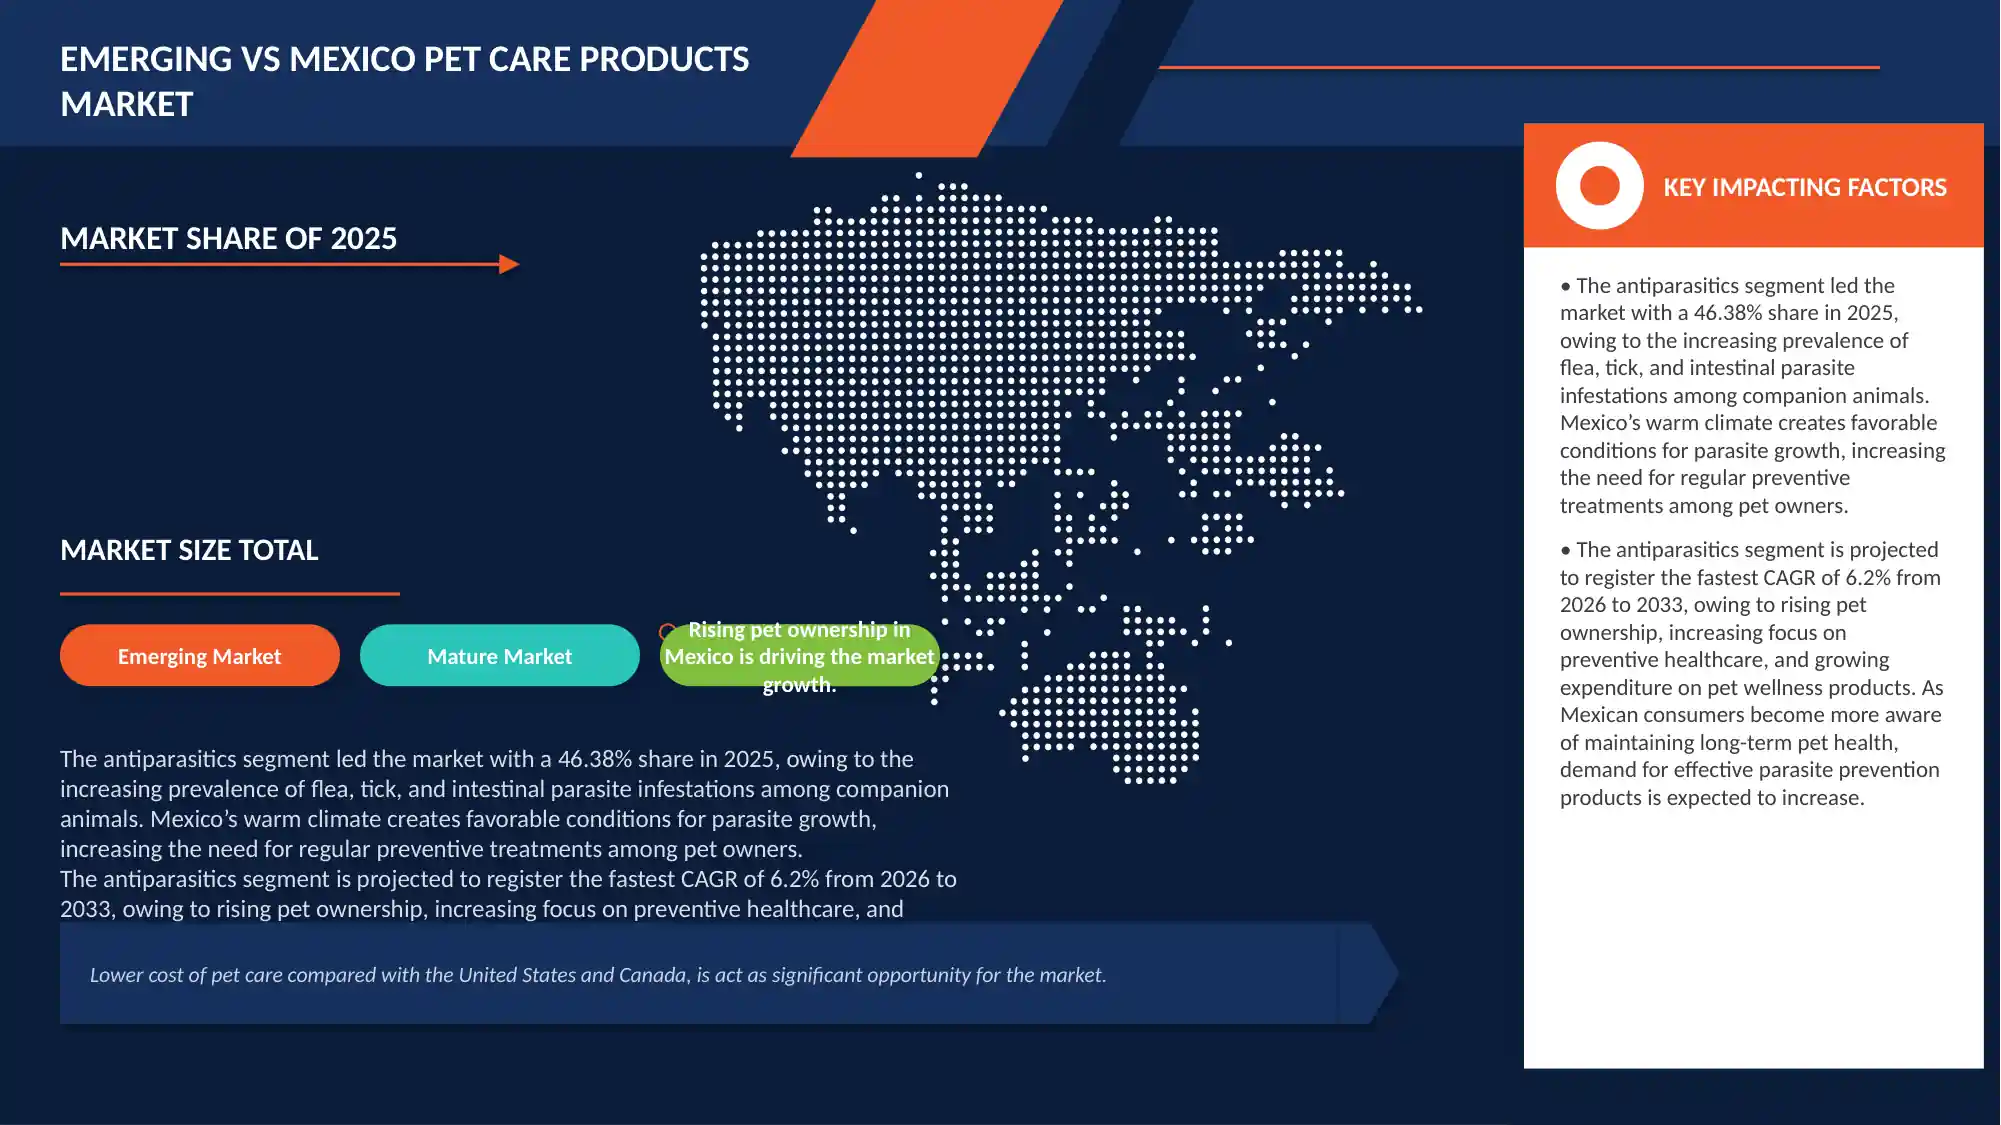
- The antiparasitics segment led the market with a 46.38% share in 2025, owing to the increasing prevalence of flea, tick, and intestinal parasite infestations among companion animals. Mexico’s warm climate creates favorable conditions for parasite growth, increasing the need for regular preventive treatments among pet owners. Growing awareness about the health risks associated with parasites, such as skin infections, anemia, and disease transmission, is encouraging consumers to adopt routine parasite prevention practices. Additionally, veterinarians are increasingly recommending antiparasitic treatments as part of regular pet wellness programs, further supporting segment growth.
- The antiparasitics segment is projected to register the fastest CAGR of 6.2% from 2026 to 2033, owing to rising pet ownership, increasing focus on preventive healthcare, and growing expenditure on pet wellness products. As Mexican consumers become more aware of maintaining long-term pet health, demand for effective parasite prevention products is expected to increase. The expansion of veterinary services, improved access to pet care information, and wider availability through online platforms are also contributing to the rapid adoption of antiparasitic products.
- The dogs segment dominated the market with a 67.84% revenue share in 2025, driven by the high number of dog-owning households and strong consumer preference for dogs as companion animals. Dogs are widely considered family members in Mexican households, leading owners to invest significantly in their nutrition, healthcare, grooming, and preventive treatments. The increasing awareness regarding canine diseases, vaccination, parasite control, and specialized dietary requirements is boosting demand for dog-specific pet care products. Additionally, the availability of a broad range of products, including premium dog food, supplements, grooming items, and veterinary medicines, supports the segment’s leading position.
- The cats segment is anticipated to be the fastest-growing pet type, registering a CAGR of 6.7% during 2026–2033, driven by the increasing cat adoption, changing lifestyle preferences, and growing acceptance of cats as household companions. Urban consumers, particularly younger pet owners, are increasingly choosing cats due to their lower maintenance requirements and suitability for smaller living spaces. Growing awareness about feline nutrition, preventive healthcare, grooming, and disease management is encouraging higher spending on cat-specific products. The expansion of specialized cat food, supplements, litter products, and healthcare solutions is further supporting market growth.
Market Size & Forecast
- Mexico Market Value (2025): USD 1.10 Billion
- Expected Market Value (2033): USD 1.71 Billion
- Forecast CAGR (2026–2033): 5.9%
Report Scope and Mexico Pet Care Products Market Segmentation
|
Attributes |
Mexico Pet Care Products Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, pricing analysis, brand share analysis, consumer survey, demography analysis, supply chain analysis, value chain analysis, raw material/consumables overview, vendor selection criteria, PESTLE Analysis, Porter Analysis, and regulatory framework. |
Mexico Pet Care Products Market Trends
Trend: Growing Demand for Premium and Natural Pet Care Products
The growing humanization of pets in Mexico is encouraging owners to prioritize quality, nutrition, preventive healthcare, and overall well-being rather than simply purchasing basic pet products. This shift is supporting demand for premium and natural pet food, functional nutrition, supplements, grooming products, and specialized healthcare solutions. Rising disposable incomes in urban areas, greater health awareness, and increasing access to product information are further encouraging consumers to trade up toward higher-value products.
For instance,
- In May 2026, Expansión reported that premium pet food represented approximately 20% of total pet food consumption in Mexico, with the segment continuing to grow faster than the overall category. The report also noted that 55% of consumers check ingredients and nutritional information before purchasing pet food, demonstrating increasing consumer attention to quality and health benefits. This growing preference for premium and nutritionally focused products is supporting the expansion of Mexico’s pet care market.
- In 2024, approximately 80 million pets were reported to be living in Mexican households, while dogs were owned by around 91% of surveyed respondents and cats by 61%. Increasing concerns regarding obesity, allergies, and digestive problems are encouraging owners to examine ingredient lists and seek cleaner, more digestible formulations. This growing health consciousness is creating opportunities for natural, functional, and specialized pet care products.
The increasing emphasis on premium nutrition, natural ingredients, functional benefits, and preventive pet health is reshaping purchasing behavior across Mexico. As owners increasingly regard pets as family members, they are becoming more willing to pay for products that offer improved nutrition, safety, and quality. The combination of pet humanization, rising health awareness, urbanization, premiumization, and expanding e-commerce is therefore expected to sustain demand for premium and natural pet care products throughout the forecast period.
Mexico Pet Care Products Market Dynamics
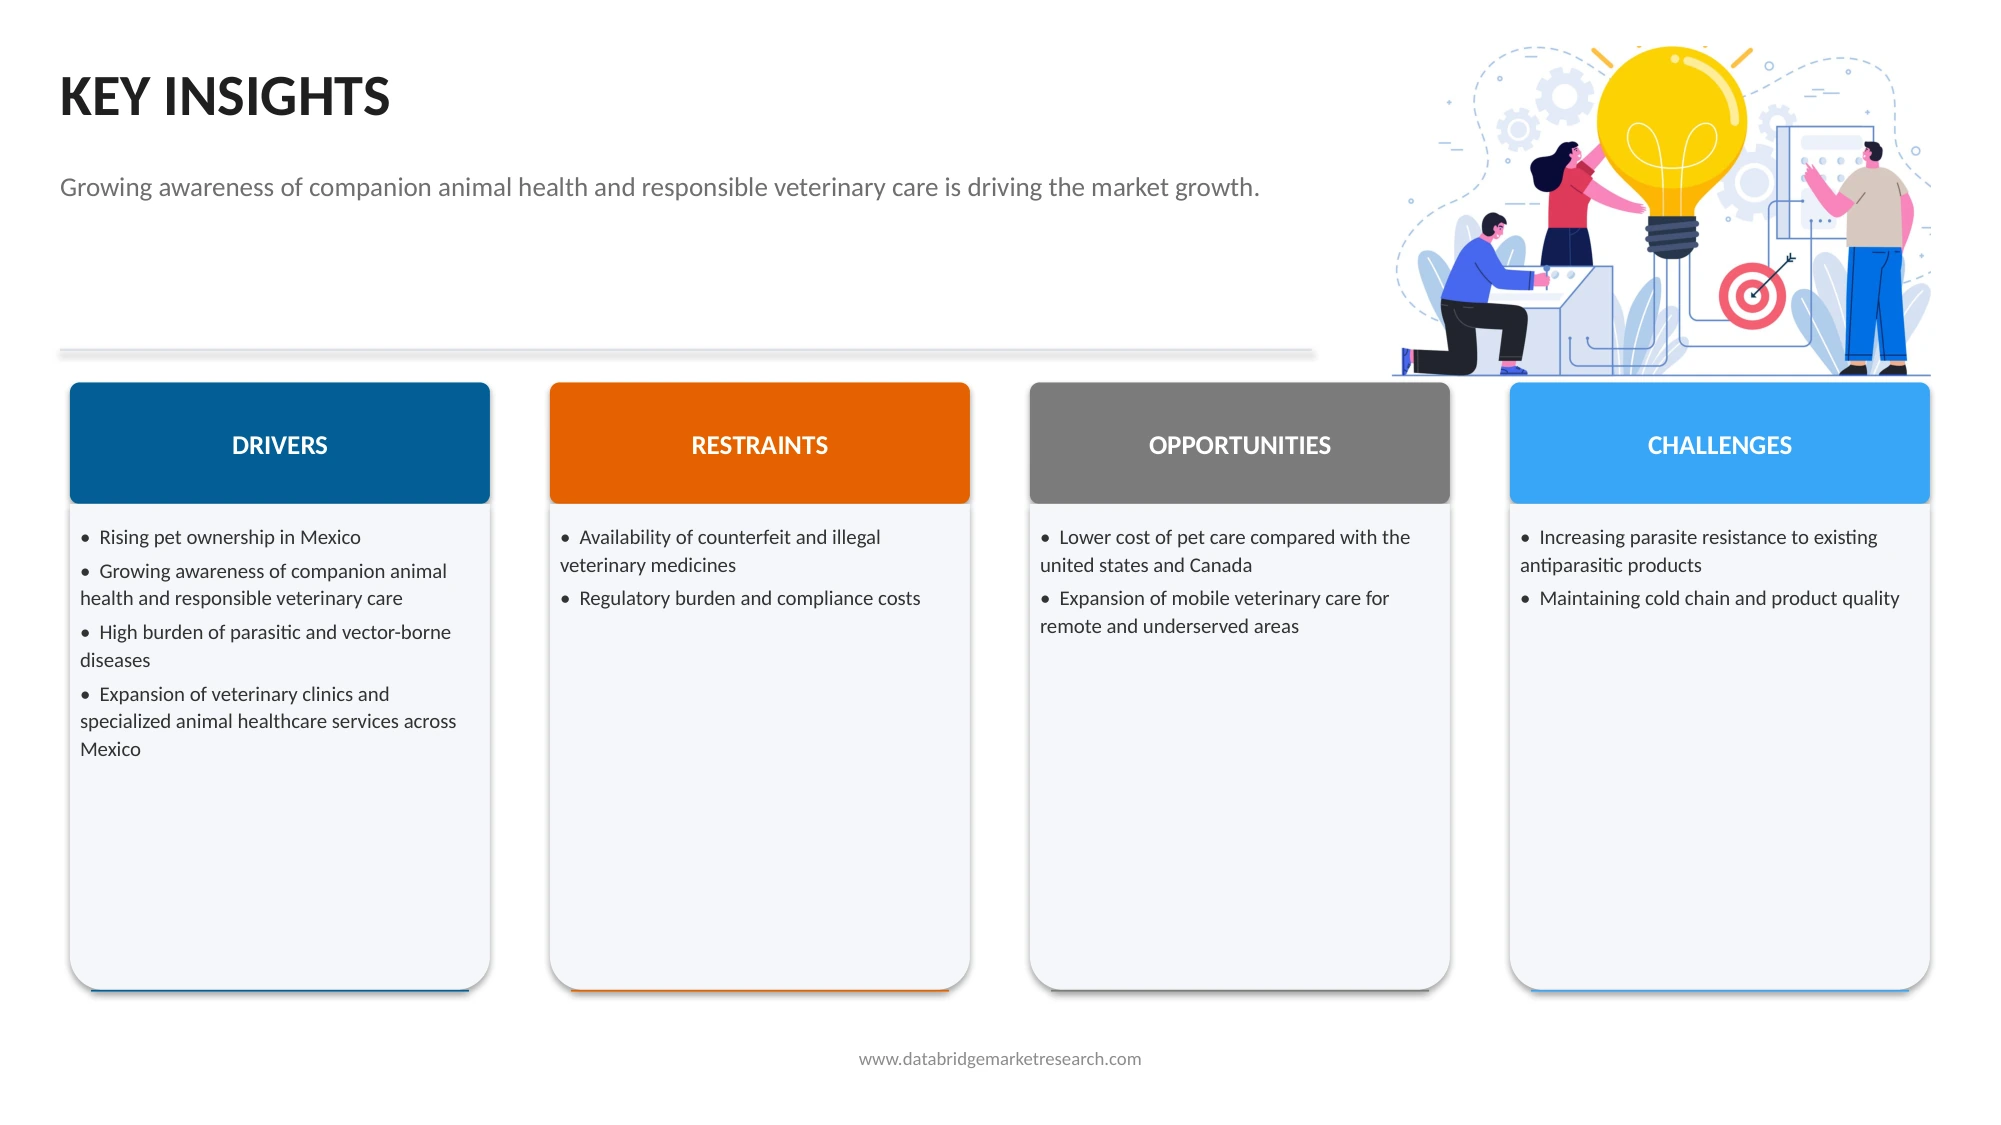
Key Market Driver: Rising Pet Ownership in Mexico
Rising pet ownership in Mexico has significantly increased demand for veterinary healthcare products as companion animals receive greater attention throughout their lives. According to Mexico's Chamber of Deputies, citing INEGI and veterinary organizations, approximately seven out of ten Mexican households own at least one pet, with dogs and cats accounting for the largest share. The expanding pet population has increased veterinary consultations, routine vaccinations, deworming programs, flea and tick prevention, surgical procedures, and treatment for infectious diseases. Simultaneously, stronger awareness of responsible pet ownership has encouraged greater spending on preventive and therapeutic healthcare products. As the companion animal population continues to expand, demand for antimicrobials, antiparasitics, anaesthetics, and other pet care products increases, thereby driving the growth of the Mexico pet care products market.
For instance,
- In June 2026, GlobalPETS reported that Mexico remained the largest pet food consumer market in Latin America, with 9 out of 10 households purchasing pet food. The country also demonstrated steady growth in pet food spending and gradual expansion of online purchasing, reflecting a growing pet-owning population and increasing investment in pet well-being. This expanding pet ownership acts as a key driver for the Mexico pet care market.
- In July 2024, Steve Dale PetWorld, LLC, highlighted that dogs accounted for 69.8% of Mexico’s companion animal population, while the pet cat population increased by 41.3% between 2017 and 2022. Growing pet humanization, rising indoor cat ownership, and higher spending on premium pet products reflect the expanding pet population and stronger owner engagement. This rising pet ownership acts as a key driver for the Mexico pet care market.
The rising number of pet-owning households, increasing pet humanization, improving economic conditions, and higher consumer expenditure on pet health and nutrition are collectively strengthening demand for pet care products across Mexico. As companion animals are increasingly regarded as family members, owners are investing more in preventive healthcare, veterinary treatments, nutritional products, grooming solutions, and wellness services. The continued expansion of the companion animal population, supported by greater awareness and evolving purchasing behavior, is creating sustained demand across the pet care value chain. Consequently, rising pet ownership remains a fundamental driver accelerating the growth of the Mexico pet care market.
Key Restraint/Challenge: Availability of Counterfeit and Illegal Veterinary Medicines
The availability of counterfeit and illegally distributed veterinary medicines in Mexico poses a significant challenge to the companion animal healthcare sector. Unauthorized products often fail to meet established quality, safety, and efficacy standards, reducing treatment effectiveness and increasing the risk of adverse health outcomes in pets. Their presence in informal distribution channels undermines consumer confidence in veterinary pharmaceuticals and creates unfair competition for licensed manufacturers and authorized distributors. Veterinary professionals also face difficulties ensuring consistent treatment outcomes when counterfeit products circulate in the market. Regulatory authorities continue to strengthen surveillance and enforcement efforts; however, illegal distribution persists across several regions. The widespread availability of counterfeit and illegal veterinary medicines reduces the adoption of legitimate pet care products and restrains the growth of the Mexico pet care products market.
For instance,
- In May 2026, Mexico’s Secretariat of Agriculture, through SENASICA, issued a warning regarding counterfeit batches of GiardiaVax and Bronchicine CAe veterinary medicines, highlighting risks to animal health and welfare. The agency urged veterinarians and distributors to purchase products only from authorized suppliers and strengthened pharmacovigilance measures to prevent illegal drug circulation. The availability of counterfeit and illegal veterinary medicines undermines treatment effectiveness and consumer confidence, acting as a key restraint for the Mexico pet care market.
- In August 2025, SENASICA issued alerts regarding the circulation of counterfeit and illegal veterinary medicines, including Catarrol Oral, Hemoplex, and Rabi Volt, citing concerns over their safety, quality, and efficacy. The agency advised veterinarians and producers to avoid unauthorized products and strengthened pharmacovigilance efforts through its Health Alert system. The availability of counterfeit and illegal veterinary medicines compromises treatment outcomes and reduces confidence in veterinary products, acting as a key restraint for the Mexico pet care market.
The continued circulation of counterfeit and illegal veterinary medicines remains a significant barrier to the development of Mexico’s pet care market. Despite stronger regulatory oversight, pharmacovigilance programs, and international enforcement initiatives, unauthorized veterinary products continue to enter informal supply chains, posing risks to animal health and reducing confidence among veterinarians and pet owners. These products compromise treatment efficacy, increase the likelihood of therapeutic failure, and discourage the use of legitimate veterinary pharmaceuticals. As manufacturers and regulatory authorities intensify efforts to combat illegal distribution, counterfeit medicines continue to challenge market integrity, limiting the adoption of quality assured pet care products and restraining overall market growth.
Key Market Opportunity: Expansion of Mobile Veterinary Care for Remote and Underserved Areas
The expansion of mobile veterinary care for remote and underserved areas presents a significant opportunity for the Mexico pet care products market. Mobile veterinary clinics deliver essential companion animal healthcare services, including routine health examinations, vaccinations, deworming, parasite control, diagnostics, minor surgical procedures, and treatment for infectious diseases directly to communities with limited access to permanent veterinary facilities. These services improve the availability of preventive and therapeutic care, strengthen awareness of responsible pet ownership, and encourage timely veterinary intervention. Government agencies, veterinary universities, animal welfare organizations, and private providers continue to expand mobile veterinary outreach programs across Mexico. The growing reach of mobile veterinary care increases the utilization of veterinary medicines and preventive healthcare products, thereby creating a significant opportunity for the growth of the Mexico pet care products market.
For instance,
- In June 2026, the National Autonomous University of Mexico (UNAM) continued operating its Mobile Veterinary Clinic to provide sterilization, deworming, rabies vaccination, and basic veterinary care in low-income areas of Mexico City. Equipped with advanced diagnostic and surgical facilities, the initiative expanded access to essential companion animal healthcare in underserved communities. This expansion of mobile veterinary care increases demand for pet healthcare products and services, acting as a key opportunity for the Mexico pet care market.
- In July 2024, as published by Humane World for Animals, Humane Society International (HSI)/Mexico launched a pilot program in Aguascalientes featuring a mobile veterinary clinic that provides free vaccinations, deworming, preventive healthcare, and veterinary check-ups in rural and low-income communities. The initiative improves access to essential companion animal healthcare while promoting responsible pet ownership. This expansion of mobile veterinary care for underserved areas acts as a key opportunity for the Mexico pet care market.
The continued expansion of mobile veterinary care across Mexico is improving access to essential companion animal healthcare in remote, rural, and underserved communities where permanent veterinary infrastructure remains limited. Mobile clinics operated by universities, animal welfare organizations, and international partners are increasing the availability of vaccinations, deworming, sterilization, preventive treatments, diagnostics, and primary veterinary services while promoting responsible pet ownership. These initiatives encourage earlier disease detection, improve treatment compliance, and expand the use of veterinary pharmaceuticals, vaccines, nutritional products, and preventive healthcare solutions. As mobile veterinary outreach continues to broaden its geographic coverage, it is expected to strengthen demand for pet care products and create substantial growth opportunities for the Mexico pet care products market.
Mexico Pet Care Products Market Scope
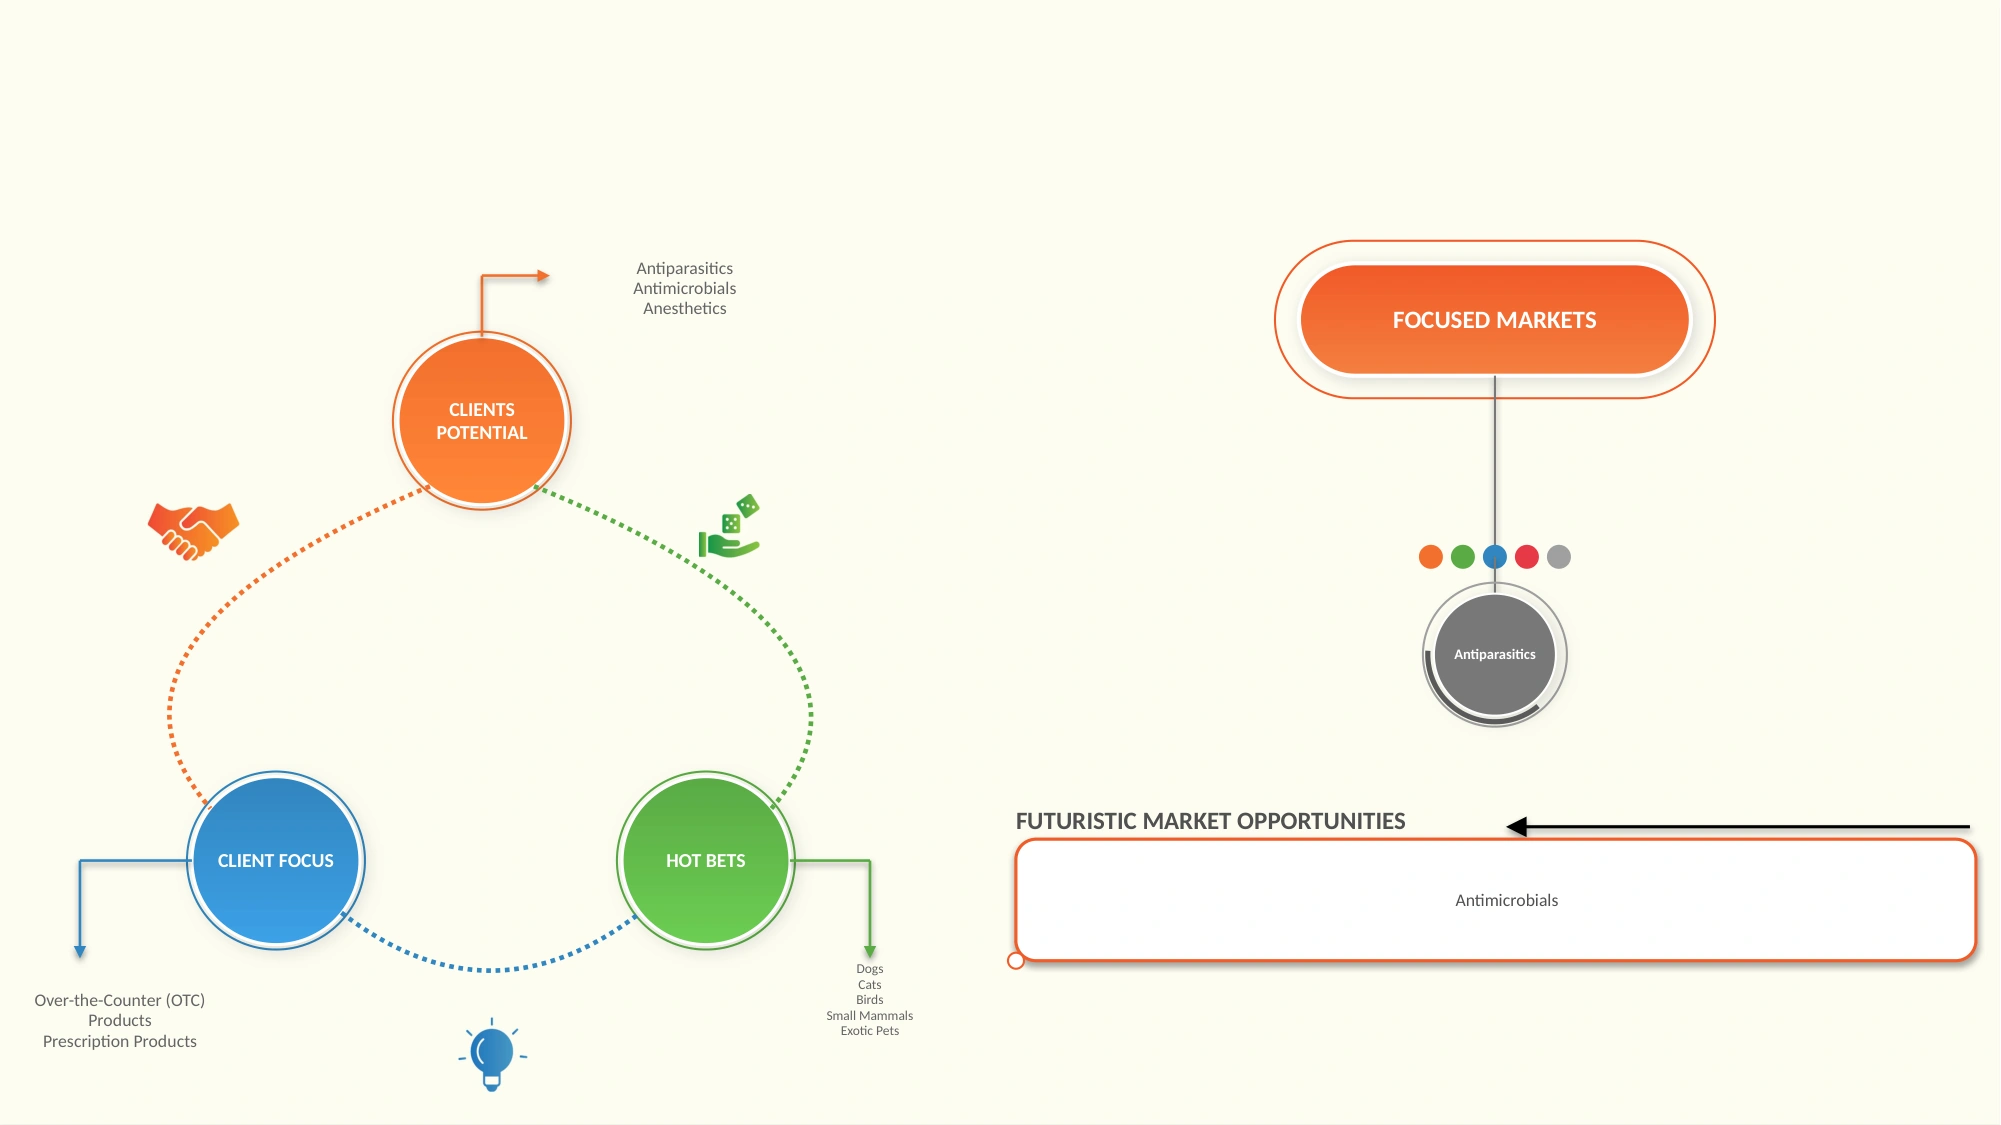
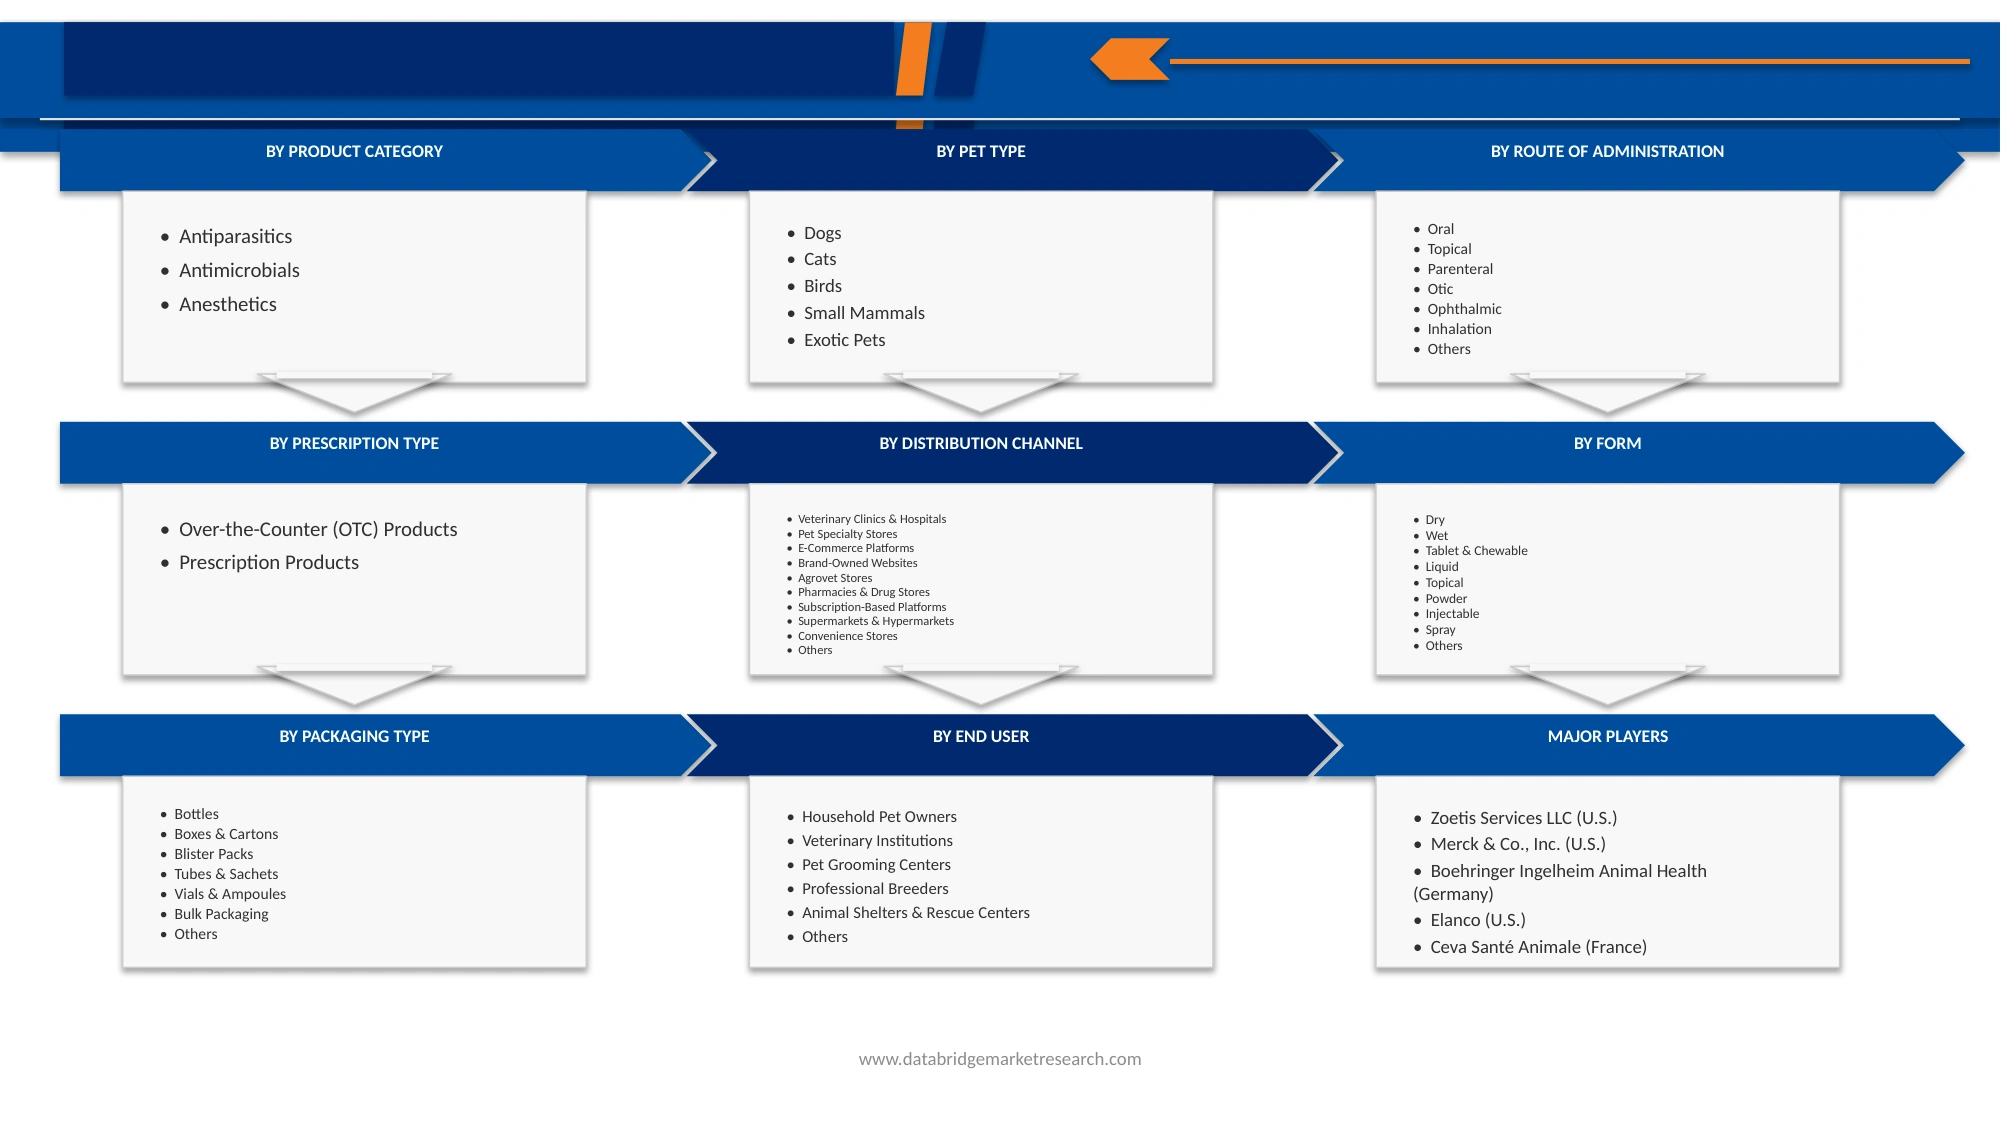
The Mexico pet care products market is segmented into eight notable segments based on product category, pet type, route of administration, prescription type, distribution channel, form, packaging type, and end user.
- By Product Category
On the basis of product category, the market is segmented into antiparasitics, antimicrobials, and anesthetics. In 2025, the antiparasitics segment is expected to dominate the Mexico pet care products market with a market share of 46.38% due to the increasing prevalence of flea, tick, and intestinal parasite infestations among companion animals. Mexico’s warm climate creates favorable conditions for parasite growth, increasing the need for regular preventive treatments among pet owners. Growing awareness about the health risks associated with parasites, such as skin infections, anemia, and disease transmission, is encouraging consumers to adopt routine parasite prevention practices. Additionally, veterinarians are increasingly recommending antiparasitic treatments as part of regular pet wellness programs, further supporting segment growth. The availability of various formulations, including oral tablets, topical solutions, sprays, and collars, provides pet owners with convenient options for parasite control.
Moreover, this segment is projected to register the fastest CAGR of 6.2% from 2026 to 2033, owing to rising pet ownership, increasing focus on preventive healthcare, and growing expenditure on pet wellness products. As Mexican consumers become more aware of maintaining long-term pet health, demand for effective parasite prevention products is expected to increase. The expansion of veterinary services, improved access to pet care information, and wider availability through online platforms are also contributing to the rapid adoption of antiparasitic products. Furthermore, manufacturers are introducing advanced formulations with longer-lasting protection and improved safety profiles, which is expected to accelerate market growth during the forecast period.
- By Pet Type
On the basis of pet type, the market is segmented into dogs, cats, birds, small mammals, exotic pets. In 2025, the dogs segment is expected to dominate the market with a share of 67.84% due to high number of dog-owning households and strong consumer preference for dogs as companion animals. Dogs are widely considered family members in Mexican households, leading owners to invest significantly in their nutrition, healthcare, grooming, and preventive treatments. The increasing awareness regarding canine diseases, vaccination, parasite control, and specialized dietary requirements is boosting demand for dog-specific pet care products. Additionally, the availability of a broad range of products, including premium dog food, supplements, grooming items, and veterinary medicines, supports the segment’s leading position. Rising urbanization and growing disposable income are also encouraging pet owners to spend more on improving the health and comfort of their dogs.
The cats segment is projected to register the fastest CAGR of 6.7% from 2026 to 2033. The fast growth is mainly driven by increasing cat adoption, changing lifestyle preferences, and growing acceptance of cats as household companions. Urban consumers, particularly younger pet owners, are increasingly choosing cats due to their lower maintenance requirements and suitability for smaller living spaces. Growing awareness about feline nutrition, preventive healthcare, grooming, and disease management is encouraging higher spending on cat-specific products. The expansion of specialized cat food, supplements, litter products, and healthcare solutions is further supporting market growth. In addition, increased availability of feline products through e-commerce platforms is making premium cat care products more accessible to consumers across Mexico.
- By Route of Administration
On the basis of route of administration, the market is segmented into oral, topical, parenteral, otic, ophthalmic, inhalation, and others. In 2025, the oral segment is expected to dominate the market with a share of 46.82% due to convenience, easy administration, and widespread availability of oral medications, supplements, and nutritional products. Pet owners often prefer oral solutions because they are effective and simple to use.
The topical segment is expected to experience the fastest CAGR of 6.4% from 2026 to 2033, supported by increasing demand for flea and tick treatments, skin care solutions, and easy-to-apply external parasite control products.
- By Prescription Type
On the basis of prescription type, the market is segmented into over-the-counter (OTC) products, prescription products. In 2025, the over-the-counter (OTC) products segment is expected to dominate the market with a share of 58.74% due to easy accessibility, affordability, and availability through multiple retail channels. Consumers increasingly prefer convenient products that do not require veterinary prescriptions.
Moreover, this segment is expected to experience the fastest CAGR of 6.1% from 2026 to 2033, driven by rising consumer awareness, increased self-care practices for pets, and expanding availability of OTC pet health products.
- By Distribution Channel
On the basis of distribution channel, the market is segmented into veterinary clinics & hospitals, pet specialty stores, e-commerce platforms, brand-owned websites, agrovet stores, pharmacies & drug stores, subscription-based platforms, supermarkets & hypermarkets, and convenience stores. In 2025, the veterinary clinics & hospitals segment is expected to dominate the market with a share of 27.46% due to professional guidance, trusted recommendations, and access to specialized pet healthcare products. Pet owners rely on veterinarians for disease prevention and treatment solutions.
The e-commerce platforms segment is expected to experience the fastest CAGR of 6.7% from 2026 to 2033, supported by growing internet penetration, convenient home delivery, wider product availability, and increasing online purchasing behavior among pet owners.
- By Form
On the basis of form, the market is segmented into dry, wet, tablet & chewable, liquid, topical, powder, injectable, spray, and others. In 2025, the dry segment is expected to dominate the market with a share of 34.62% due to longer shelf life, easy storage, and popularity among pet owners. Dry products are widely preferred because of their convenience, affordability, and practical usage benefits.
The tablet & chewable segment is expected to experience the fastest CAGR of 6.6% from 2026 to 2033, owing to improved palatability, easier administration, and increasing demand for supplements and preventive healthcare products.
- By Packaging Type
On the basis of packaging type, the market is segmented into bottles, boxes & cartons, blister packs, tubes & sachets, vials & ampoules, bulk packaging, and others. In 2025, the bottles segment is expected to dominate the market with a market share of 31.74% due to convenient storage, durability, and widespread usage for liquid medications, supplements, and grooming products. Bottles provide ease of handling and consumer familiarity.
The blister packs segment is expected to experience the fastest CAGR of 6.6% from 2026 to 2033, driven by accurate dosage control, portability, product protection, and growing demand for tablets and chewable pet medications.
- By End User
On the basis of end user, the market is segmented into household pet owners, veterinary institutions, pet grooming centers, professional breeders, animal shelters & rescue centers, and others. In 2025, the household pet owners segment is expected to dominate the market with a share of 62.84% due to increasing trend of pet humanization and the growing perception of pets as important family members. Mexican households are increasingly investing in high-quality food, healthcare products, grooming solutions, supplements, and preventive treatments to improve their pets’ overall well-being. Rising disposable income, greater awareness of animal health, and increased access to pet care information through digital platforms are encouraging owners to adopt better care practices. Additionally, the expansion of retail stores and online marketplaces has improved consumer access to a wide range of pet products, including premium and specialized offerings. The growing adoption of dogs and cats as companion animals, especially in urban areas, is further strengthening demand from household pet owners.
Moreover, this segment is expected to experience the fastest CAGR of 6.0% from 2026 to 2033, supported by rising pet ownership, increasing expenditure on preventive healthcare, and growing demand for premium pet care solutions. Consumers are becoming more proactive about maintaining pet health through regular parasite prevention, nutritional supplements, grooming products, and wellness services. Younger generations of pet owners are contributing significantly to this growth by seeking convenient, high-quality, and personalized products for their animals. Furthermore, the rapid growth of e-commerce platforms is enabling easier access to a broader range of pet care products, including imported and specialized items. Increasing awareness about pet nutrition, hygiene, and disease prevention is expected to continue driving the expansion of the household pet owners segment throughout the forecast period.
Mexico Pet Care Products Market Regional Analysis
The Mexico pet care products market is growing across regions due to rising pet ownership, increasing disposable income, urbanization, and greater awareness of pet health. The central region, especially Mexico City and nearby metropolitan areas, dominates the market due to high pet adoption rates, strong veterinary infrastructure, and greater demand for premium pet food, grooming products, and healthcare solutions.
Northern Mexico is also witnessing strong growth due to higher purchasing power, exposure to international pet care trends, and increasing demand for advanced wellness products. The presence of organized retail channels and improved distribution networks further supports market expansion in this region.
Western and southeastern regions are expected to experience steady growth, supported by rising awareness of pet nutrition, expanding e-commerce platforms, and improved access to pet care products. Overall, increasing pet humanization and growing consumer spending on animal wellness are driving market growth throughout Mexico.
Mexico Pet Care Products Market Share
The Mexico pet care products industry is primarily led by well-established companies, including:
- Zoetis Inc. (US)
- Elanco Animal Health Incorporated (US)
- Boehringer Ingelheim Animal Health (Germany)
- Merck Animal Health (US)
- Virbac S.A. (France)
- Vetoquinol S.A. (France)
- Ceva Santé Animale (France)
- Vetnil (Brazil)
- Bimeda Holdings PLC (Ireland)
- Phibro Animal Health Corporation (US)
- Avimex (Laboratorio Avi-Mex) (Mexico)
- Laboratorios Andoci (Mexico)
- Pecuaris Laboratorios (Mexico)
- Pets Pharma de México (Mexico)
- Vets Pharma Internacional (Mexico)
- Agro Salud Animal (Mexico)
- Alpha Chem México (Mexico)
Latest Developments in Mexico Pet Care Products Market
- In June 2026, Merck Animal Health reaffirmed its commitment to protecting U.S. livestock from the growing threat of New World Screwworm (NWS) following the first confirmed U.S. cattle case. The company emphasized industry-wide collaboration, education for veterinarians and producers, and proactive disease preparedness.
- In June 2026, Elanco Animal Health announced its commitment to helping U.S. livestock producers, veterinarians, and pet owners combat the growing threat of New World screwworm (NWS) after the first confirmed case in U.S. livestock was reported in Texas. The company is providing a portfolio of treatment and prevention solutions for both livestock and companion animals, supported by its decades of experience in managing the parasite globally.
- In May 2026, Ceva Animal Health (Ceva) and Mitsui & Co., Ltd. (Mitsui) announced the creation of Ceva Bussan Animal Health, a new joint venture that brings together Bussan Animal Health (BAH) and Ceva Japan. As part of the transaction, Mitsui has transferred 60% of its shareholding in BAH to Ceva. Ceva Bussan Animal Health will be operated by Ceva as a controlling shareholder and benefit from Mitsui’s ongoing support as a leading global trading and investment company headquartered in Japan.
- In November, Phibro Animal Health Corporation completed the acquisition of Zoetis' Medicated Feed Additive (MFA) portfolio and selected water soluble products. The acquisition added more than 37 product lines, six manufacturing facilities (U.S., Italy, 2024 Acquisition and China), products marketed in approximately 80 countries, and over 300 employees. The portfolio includes livestock health products such as Avatec (lasalocid), an anticoccidial used in poultry, strengthening Phibro's animal health and parasiticide-related portfolio.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Table of Content
1 INTRODUCTION
1.1 OBJECTIVES OF THE STUDY
1.2 MARKET DEFINITION
1.3 OVERVIEW OF MEXICO PET CARE PRODUCTS MARKET
1.4 LIMITATIONS
1.5 MARKETS COVERED
2 MARKET SEGMENTATION
2.1 MARKETS COVERED
2.2 GEOGRAPHICAL SCOPE
2.3 YEARS CONSIDERED FOR THE STUDY
2.4 CURRENCY AND PRICING
2.5 DBMR TRIPOD DATA VALIDATION MODEL
2.6 MULTIVARIATE MODELING
2.7 PRIMARY INTERVIEWS WITH KEY OPINION LEADERS
2.8 DBMR MARKET POSITION GRID
2.9 MARKET APPLICATION COVERAGE GRID
2.1 VENDOR SHARE ANALYSIS
2.11 SECONDARY SOURCES
2.12 ASSUMPTIONS
3 EXECUTIVE SUMMARY
4 PREMIUM INSIGHTS
4.1 PORTER FIVE FORCES
4.2 PESTLE ANALYSIS
4.2.1 POLITICAL FACTORS
4.2.2 ECONOMIC FACTORS
4.2.3 SOCIAL FACTORS
4.2.4 TECHNOLOGICAL FACTORS
4.2.5 ENVIRONMENTAL FACTORS
4.2.6 LEGAL FACTORS
4.3 PIPELINE ANALYSIS
4.3.1 CLINICAL DEVELOPMENT AND PHASE ANALYSIS
4.3.2 PRODUCT PIPELINE FOR ANIMAL PARASITICIDES
4.3.3 TARGET ANIMAL SAFETY STUDIES (TASS)
4.3.4 TARGET ANIMAL EFFECTIVENESS STUDIES (TAES)
4.4 PATENT ANALYSIS
4.4.1 PATENT NUMBER AND EXPIRY
4.4.2 COUNTRY-LEVEL APPROVAL
4.4.3 LIST OF PRODUCTS REACHING EXPIRY IN NEXT 3 YEARS
4.4.4 PRODUCTS PATENTED IN SPECIFIC COUNTRIES
4.4.5 CONCLUSION
4.5 INDUSTRY INSIGHTS
4.5.1 MICRO AND MACRO ECONOMIC FACTORS
4.5.1.1 RISING PET OWNERSHIP AND HOUSEHOLD PET PENETRATION SUPPORTING MARKET EXPANSION
4.5.1.2 URBANIZATION AND EXPANSION OF VETERINARY HEALTHCARE INFRASTRUCTURE
4.5.1.3 INFLATION AND EXCHANGE RATE VOLATILITY INFLUENCING VETERINARY PRODUCT PRICING
4.5.1.4 GROWTH OF DIGITAL COMMERCE EXPANDING ACCESS TO PET HEALTHCARE PRODUCTS
4.5.1.5 INCREASING HOUSEHOLD EXPENDITURE ON COMPANION ANIMAL CARE
4.5.1.6 DEPENDENCE ON IMPORTED VETERINARY PRODUCTS AND PHARMACEUTICAL INPUTS
4.5.2 PENETRATION AND GROWTH PROSPECT MAPPING
4.5.2.1 RISING PENETRATION OF PREVENTIVE VETERINARY HEALTHCARE AMONG COMPANION ANIMALS
4.5.3 KEY PRICING STRATEGIES
4.5.3.1 VALUE-BASED PRICING FOR PREMIUM VETERINARY THERAPEUTICS
4.5.3.2 COMPETITIVE PRICING ACROSS PRESCRIPTION AND OVER-THE-COUNTER PRODUCT PORTFOLIOS
4.5.3.3 CHANNEL-BASED PRICING TO OPTIMIZE MARKET COVERAGE
4.5.3.4 PORTFOLIO DIVERSIFICATION AND PACK-SIZE PRICING STRATEGIES
4.5.4 ANALYSIS AND RECOMMENDATION
4.5.4.1 STRENGTHEN PREVENTIVE HEALTHCARE PRODUCT PORTFOLIOS
4.5.4.2 EXPAND PRESENCE IN UNDERSERVED AND RURAL MARKETS
4.5.4.3 INVEST IN LOCAL MANUFACTURING AND SUPPLY CHAIN RESILIENCE
4.5.4.4 ACCELERATE DIGITAL TRANSFORMATION AND OMNICHANNEL DISTRIBUTION
4.5.5 SUPPLY CHAIN RESILIENCE
4.5.5.1 DIVERSIFICATION OF PET CARE RAW MATERIAL AND MANUFACTURING SUPPLIERS
4.5.5.2 ESTABLISHMENT OF LOCAL PRODUCTION AND FILL-FINISH HUBS
4.5.5.3 STRATEGIC STOCKPILING OF CORE PET CARE PRODUCTS
4.5.5.4 DEVELOPMENT OF ALTERNATIVE LOGISTICS AND DISTRIBUTION ROUTES
4.5.5.5 STRATEGIC PARTNERSHIPS WITH CONTRACT MANUFACTURERS (CDMOS)
4.5.5.6 EXPANSION OF PET PRODUCT MANUFACTURING AND PACKAGING CAPABILITIES
4.5.6 ENERGY & MANUFACTURING OPERATIONAL COST RISK
4.5.6.1 RISING ENERGY COSTS AFFECTING PRODUCTION FACILITIES
4.5.6.2 INCREASED COSTS FOR RAW MATERIALS AND INGREDIENTS
4.5.6.3 LONG-TERM ENERGY PROCUREMENT STRATEGIES
4.5.6.4 ADOPTION OF ENERGY-EFFICIENT TECHNOLOGIES
4.5.6.5 ADVANCED AUTOMATION AND CONTINUOUS MANUFACTURING
4.5.6.6 INTEGRATION OF RENEWABLE ENERGY SOURCES
4.5.7 GEOGRAPHIC FOOTPRINT REASSESSMENT
4.5.7.1 EXPANSION OF MANUFACTURING IN STABLE REGIONS
4.5.7.2 DIVERSIFICATION OF SUPPLY BASE
4.5.7.3 RELOCATION OF MANUFACTURING FACILITIES
4.5.7.4 EXPANSION IN EMERGING MARKETS WITHIN MEXICO
4.5.7.5 REGIONAL DISTRIBUTION AND COLD CHAIN HUBS
4.5.8 SCENARIO PLANNING & RISK MANAGEMENT
4.5.8.1 DEVELOPMENT OF SUPPLY CHAIN CONTINGENCY PLANS
4.5.8.2 MULTI-SOURCE PROCUREMENT STRATEGIES
4.5.8.3 GOVERNMENT AND PUBLIC HEALTH AUTHORITY COLLABORATIONS
4.5.8.4 CRISIS-RESPONSE SUPPLY NETWORKS
4.5.8.5 DEPLOYMENT OF PREDICTIVE SUPPLY CHAIN ANALYTICS
4.5.9 NEW BUSINESS, EMERGING REVENUE OPPORTUNITIES & FUTURE OUTLOOK
4.5.9.1 EXPANSION OF PREVENTIVE HEALTHCARE AND SUBSCRIPTION-BASED WELLNESS PROGRAMS
4.5.9.2 GROWTH OPPORTUNITIES IN DIGITAL VETERINARY SERVICES AND E-COMMERCE
4.5.9.3 INCREASING INVESTMENT IN PREMIUM AND INNOVATIVE VETERINARY THERAPEUTICS
4.5.9.4 EXPANSION OF VETERINARY HEALTHCARE INFRASTRUCTURE IN UNDERSERVED REGIONS
4.5.9.5 POSITIVE LONG-TERM MARKET OUTLOOK SUPPORTED BY PET HUMANIZATION AND HEALTHCARE AWARENESS
4.6 EPIDEMIOLOGY
4.6.1 PET OWNERSHIP LEVELS BY TYPE
4.6.2 PET HEALTHCARE ACCESS RATES
4.6.3 PET LIFESPAN AND MORTALITY TRENDS
4.6.4 PRODUCT USAGE ADHERENCE AND SWITCH MODEL
4.6.4.1 PREVENTIVE PRODUCT USAGE ADHERENCE
4.6.4.2 FACTORS AFFECTING PRODUCT ADHERENCE
4.6.4.3 PRODUCT SWITCHING MODEL
4.6.5 BRAND LOYALTY AND RETENTION TRENDS
4.6.6 SUCCESS RATES FOR PET TREATMENTS
4.6.6.1 ANTIPARASITIC TREATMENT SUCCESS RATES
4.6.6.2 ANTIMICROBIAL TREATMENT SUCCESS RATES
4.6.6.3 SURGICAL AND ANESTHESIA TREATMENT OUTCOMES
4.6.6.4 CHRONIC DISEASE MANAGEMENT OUTCOMES
4.7 MARKETED PRODUCT ANALYSIS
4.7.1 INTRODUCTION
4.7.2 PRODUCT
4.7.2.1 BRAND NAME
4.7.2.2 GENERIC NAME
4.7.3 INDICATION
4.7.4 PHARMACOLOGICAL CLASSIFICATION
4.7.5 PRIMARY INDICATION
4.7.6 MARKET STATUS
4.7.7 PRODUCT TYPE
4.7.8 PRODUCT DOSAGE FORM
4.7.9 DOSAGE AVAILABILITY
4.7.10 PACKAGING TYPE
4.7.11 ROUTE OF ADMINISTRATION
4.7.12 DOSING FREQUENCY
4.7.13 PRODUCT INSIGHT
4.8 MARKET ACCESS
4.8.1 TEN-YEAR MARKET FORECAST
4.8.2 CLINICAL TRIAL / NEW PRODUCT UPDATES
4.8.3 ANNUAL NEW PRODUCT LAUNCHES & REGISTRATIONS
4.8.4 MANUFACTURERS AND PARTNERSHIP DEALS
4.8.5 MAJOR PRODUCT ADOPTION AND UPTAKE
4.8.6 CURRENT PET CARE PRACTICES
4.9 IMPACT OF UPCOMING PRODUCTS AND INNOVATIONS
4.9.1 CONCLUSION
4.1 R&D ANALYSIS
4.10.1 COMPARATIVE ANALYSIS
4.10.1.1 COMPANION ANIMAL THERAPEUTICS RECEIVE GREATER R&D FOCUS THAN LIVESTOCK-ORIENTED PRODUCTS
4.10.1.2 PREVENTIVE HEALTHCARE PRODUCTS DEMONSTRATE HIGHER DEVELOPMENT ACTIVITY THAN THERAPEUTIC MEDICINES
4.10.1.3 ADVANCED FORMULATIONS ARE REPLACING CONVENTIONAL DOSAGE FORMS
4.10.1.4 INCREASING INVESTMENT IN VETERINARY RESEARCH STRENGTHENS PRODUCT INNOVATION
4.10.2 DEVELOPMENTAL LANDSCAPE
4.10.2.1 GROWING DEVELOPMENT OF PREVENTIVE AND LONG-ACTING COMPANION ANIMAL THERAPIES
4.10.2.2 EXPANSION OF VETERINARY BIOLOGICALS AND IMMUNOLOGICAL PRODUCTS
4.10.2.3 INCREASING DIGITALIZATION OF VETERINARY PHARMACOVIGILANCE AND PRODUCT MONITORING
4.10.2.4 STRENGTHENING RESEARCH THROUGH GOVERNMENT–ACADEMIC COLLABORATION
4.10.3 IN-DEPTH INSIGHTS ON REGULATORY MILESTONES
4.10.3.1 IMPLEMENTATION OF MEXICO'S VETERINARY PHARMACOVIGILANCE SYSTEM STRENGTHENED POST-MARKET SURVEILLANCE
4.10.3.2 NOM-012-SAG/ZOO-2020 MODERNIZED THE REGULATORY FRAMEWORK FOR VETERINARY PRODUCTS
4.10.3.3 EXPANSION OF VETERINARY PRODUCT REGISTRATION SUPPORTING MARKET INNOVATION
4.10.3.4 STRENGTHENED CONTROLS AGAINST COUNTERFEIT VETERINARY MEDICINES
4.10.3.5 ALIGNMENT WITH INTERNATIONAL ANIMAL HEALTH STANDARDS
5 HEALTHCARE TARIFFS IMPACT ANALYSIS
5.1 OVERVIEW
5.2 TARIFF STRUCTURES
5.2.1 MEXICO VS. REGIONAL TARIFF STRUCTURES
5.2.2 MEXICO: PUBLIC HEALTH INSURANCE & REGULATORY PRICING
5.2.3 TRADE AGREEMENTS IMPACTING IMPORTED PRODUCTS
5.2.4 GOVERNMENT TARIFFS ON IMPORTED PET PRODUCTS
5.2.5 EMERGING MARKETS: CHALLENGES IN TARIFF IMPLEMENTATION
5.2.6 TRADE BARRIERS AND IMPORT DUTIES
5.2.7 IMPORT DUTIES ON VETERINARY DRUGS VS. GENERICS
5.2.8 IMPACT ON PRODUCT AFFORDABILITY
5.2.9 TRADE AGREEMENTS IMPACTING PET SECTOR
5.3 IMPACT OF HEALTHCARE TARIFFS ON END USERS
5.3.1 COST BURDEN ON RETAILERS, VETS, PET OWNERS
5.3.2 EFFECT ON PET OWNER AFFORDABILITY AND INSURANCE COVERAGE
5.3.3 TARIFFS & MEDICAL TOURISM FOR SPECIALIST PET CARE
5.4 TRADE AGREEMENTS AND TARIFFS
5.4.1 WTO REGULATIONS ON HEALTHCARE TARIFFS
5.4.2 IMPACT OF TRADE WARS ON SUPPLY CHAIN
5.4.3 ROLE OF FTAS IN REDUCING TARIFFS
5.5 IMPACT ON COSTS AND ACCESSIBILITY
5.6 IMPORTANCE OF TARIFFS IN THE SECTOR
6 REGULATORY FRAMEWORK
6.1 INTRODUCTION
6.2 REGULATORY APPROVAL PROCESS FOR PET CARE PRODUCTS
6.3 EASE OF REGULATORY APPROVAL IN MEXICO
6.4 APPROVAL PATHWAYS FOR IMPORTED/LOCAL PRODUCTS
6.5 LICENSING AND REGISTRATION
6.6 POST-MARKETING SURVEILLANCE
6.7 GOOD MANUFACTURING PRACTICES (GMPS) GUIDELINES
6.8 CONCLUSION
7 MARKET OVERVIEW
7.1 DRIVER
7.1.1 RISING PET OWNERSHIP IN MEXICO
7.1.2 GROWING AWARENESS OF COMPANION ANIMAL HEALTH AND RESPONSIBLE VETERINARY CARE
7.1.3 HIGH BURDEN OF PARASITIC AND VECTOR-BORNE DISEASES
7.1.4 EXPANSION OF VETERINARY CLINICS AND SPECIALIZED ANIMAL HEALTHCARE SERVICES ACROSS MEXICO
7.2 RESTRAINTS
7.2.1 AVAILABILITY OF COUNTERFEIT AND ILLEGAL VETERINARY MEDICINES
7.2.2 REGULATORY BURDEN AND COMPLIANCE COSTS
7.3 OPPORTUNITY
7.3.1 LOWER COST OF PET CARE COMPARED WITH THE UNITED STATES AND CANADA
7.3.2 EXPANSION OF MOBILE VETERINARY CARE FOR REMOTE AND UNDERSERVED AREAS
7.3.3 RISING APPLICATIONS OF UV FILTERS IN INDUSTRIAL COATINGS
7.4 CHALLENGES
7.4.1 INCREASING PARASITE RESISTANCE TO EXISTING ANTIPARASITIC PRODUCTS
7.4.2 MAINTAINING COLD CHAIN AND PRODUCT QUALITY
8 MEXICO PET CARE PRODUCTS MARKET, BY PRODUCT TYPE
8.1 OVERVIEW
8.2 MEXICO PET CARE PRODUCTS MARKET, BY PRODUCT CATEGORY, 2018-2033 (USD THOUSAND)
8.2.1 ANTIPARASITICS
8.2.2 ANTIMICROBIALS
8.2.3 ANESTHETICS
8.3 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY PARASITE TYPE, 2018-2033 (USD THOUSAND)
8.3.1 ECTOPARASITICIDES
8.3.2 ENDOPARASITICIDES
8.3.3 ENDECTOCIDES
8.4 MEXICO ECTOPARASITICIDES IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.4.1 FLEA CONTROL
8.4.2 TICK CONTROL
8.4.3 MITE CONTROL
8.4.4 LICE CONTROL
8.5 MEXICO ENDOPARASITICIDES IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.5.1 NEMATODES
8.5.2 CESTODES
8.5.3 TREMATODES
8.6 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY DRUG CLASS, 2018-2033 (USD THOUSAND)
8.6.1 ISOXAZOLINES
8.6.2 MACROCYCLIC LACTONES
8.6.3 COMBINATION PRODUCTS
8.6.4 BENZIMIDAZOLES
8.6.5 IMIDACLOPRID-BASED PRODUCTS
8.6.6 PYRETHROIDS
8.6.7 ORGANOPHOSPHATES
8.6.8 OTHERS
8.7 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY FORM, 2018-2033 (USD THOUSAND)
8.7.1 TOPICAL PRODUCTS
8.7.2 ORAL PRODUCTS
8.7.3 WEARABLE PRODUCTS
8.7.4 INJECTABLE PRODUCTS
8.8 MEXICO TOPICAL PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.8.1 SPOT-ON SOLUTIONS
8.8.2 SHAMPOOS
8.8.3 SPRAYS
8.8.4 POWDERS
8.8.5 OTHERS
8.9 MEXICO ORAL PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.9.1 CHEWABLE TABLETS
8.9.2 TABLETS/DEWORMERS
8.9.3 LIQUIDS
8.1 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY PREVENTION TYPE, 2018-2033 (USD THOUSAND)
8.10.1 MONTHLY PREVENTION
8.10.2 QUARTERLY PREVENTION
8.10.3 ANNUAL PREVENTION
8.11 MEXICO ANTIMICROBIALS IN PET CARE PRODUCTS MARKET, BY DRUG CLASS, 2018-2033 (USD THOUSAND)
8.11.1 PENICILLINS
8.11.2 CEPHALOSPORINS
8.11.3 FLUOROQUINOLONES
8.11.4 MACROLIDES
8.11.5 TETRACYCLINES
8.11.6 AMINOGLYCOSIDES
8.11.7 SULFONAMIDES
8.11.8 LINCOSAMIDES
8.11.9 CARBAPENEMS
8.11.10 OTHERS
8.12 MEXICO ANTIMICROBIALS IN PET CARE PRODUCTS MARKET, BY INDICATION, 2018-2033 (USD THOUSAND)
8.12.1 SKIN & SOFT TISSUE INFECTIONS
8.12.2 RESPIRATORY INFECTIONS
8.12.3 URINARY TRACT INFECTIONS
8.12.4 GASTROINTESTINAL INFECTIONS
8.12.5 DENTAL INFECTIONS
8.12.6 OTITIS & EAR INFECTIONS
8.12.7 POST-SURGICAL INFECTIONS
8.12.8 OPHTHALMIC INFECTIONS
8.12.9 OTHERS
8.13 MEXICO ANTIMICROBIALS IN PET CARE PRODUCTS MARKET, BY FORM, 2018-2033 (USD THOUSAND)
8.13.1 ORAL PRODUCTS
8.13.2 INJECTABLE PRODUCTS
8.13.3 TOPICAL & DERMATOLOGY PRODUCTS
8.13.4 EYE & EAR PREPARATIONS
8.14 MEXICO ORAL PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.14.1 TABLETS
8.14.2 CHEWABLE TABLETS
8.14.3 ORAL SUSPENSIONS/SYRUPS
8.14.4 CAPSULES
8.14.5 OTHERS
8.15 MEXICO INJECTABLE PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.15.1 INTRAMUSCULAR
8.15.2 SUBCUTANEOUS
8.15.3 INTRAVENOUS
8.16 MEXICO TOPICAL & DERMATOLOGY PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.16.1 MEDICATED SHAMPOOS
8.16.2 SPRAYS
8.16.3 MEDICATED CREAMS
8.16.4 OINTMENTS
8.16.5 GELS
8.16.6 OTHERS
8.17 MEXICO EYE & EAR PREPARATIONS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
8.17.1 OTIC SOLUTIONS
8.17.2 OPHTHALMIC DROPS
8.17.3 OTHERS
8.18 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY PRODUCT TYPE, 2018-2033 (USD THOUSAND)
8.18.1 GENERAL ANESTHETICS
8.18.2 LOCAL ANESTHETICS
8.18.3 SEDATIVES
8.18.4 ANALGESICS WITH ANESTHESIA
8.19 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY ADMINISTRATION ROUTE, 2018-2033 (USD THOUSAND)
8.19.1 INJECTABLE
8.19.2 INHALATION
8.19.3 TOPICAL
8.2 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY PROCEDURE TYPE, 2018-2033 (USD THOUSAND)
8.20.1 SURGICAL PROCEDURES
8.20.2 DENTAL PROCEDURES
8.20.3 DIAGNOSTIC PROCEDURES
8.20.4 ORTHOPEDIC PROCEDURES
8.20.5 EMERGENCY PROCEDURES
8.20.6 OTHERS
8.21 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY DURATION TYPE, 2018-2033 (USD THOUSAND)
8.21.1 SHORT-ACTING
8.21.2 INTERMEDIATE-ACTING
8.21.3 LONG-ACTING
9 MEXICO PET CARE PRODUCTS MARKET, BY PET TYPE
9.1 OVERVIEW
9.2 MEXICO PET CARE PRODUCTS MARKET, BY PET TYPE, 2018-2033 (USD THOUSAND)
9.2.1 DOGS
9.2.2 CATS
9.2.3 BIRDS
9.2.4 SMALL MAMMALS
9.2.5 EXOTIC PETS
9.3 MEXICO DOGS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
9.3.1 ADULT DOGS
9.3.2 PUPPIES
9.3.3 SENIOR DOGS
9.4 MEXICO CATS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
9.4.1 ADULT CATS
9.4.2 KITTENS
9.4.3 SENIOR CATS
9.5 MEXICO SMALL MAMMALS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
9.5.1 RABBITS
9.5.2 HAMSTERS
9.5.3 GUINEA PIGS
9.5.4 FERRETS
10 MEXICO PET CARE PRODUCTS MARKET, BY ROUTE OF ADMINISTRATION
10.1 OVERVIEW
10.2 MEXICO PET CARE PRODUCTS MARKET, BY ROUTE OF ADMINISTRATION, 2018-2033 (USD THOUSAND)
10.2.1 ORAL
10.2.2 TOPICAL
10.2.3 PARENTERAL
10.2.4 OTIC
10.2.5 OPHTHALMIC
10.2.6 INHALATION
10.2.7 OTHERS
10.3 MEXICO ORAL IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
10.3.1 TABLETS
10.3.2 CHEWABLES
10.3.3 LIQUIDS
10.3.4 CAPSULES
10.4 MEXICO TOPICAL IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
10.4.1 SPOT-ON
10.4.2 SHAMPOOS
10.4.3 SPRAYS
10.4.4 CREAMS
10.4.5 OTHERS
10.5 MEXICO PARENTERAL IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
10.5.1 SUBCUTANEOUS
10.5.2 INTRAMUSCULAR
10.5.3 INTRAVENOUS
11 MEXICO PET CARE PRODUCTS MARKET, BY PRESCRIPTION TYPE
11.1 OVERVIEW
11.2 MEXICO PET CARE PRODUCTS MARKET, BY PRESCRIPTION TYPE, 2018-2033 (USD THOUSAND)
11.2.1 OVER-THE-COUNTER (OTC) PRODUCTS
11.2.2 PRESCRIPTION PRODUCTS
12 MEXICO PET CARE PRODUCTS MARKET, BY DISTRIBUTION CHANNEL
12.1 OVERVIEW
12.2 MEXICO PET CARE PRODUCTS MARKET, BY DISTRIBUTION CHANNEL, 2018-2033 (USD THOUSAND)
12.2.1 VETERINARY CLINICS & HOSPITALS
12.2.2 PET SPECIALTY STORES
12.2.3 E-COMMERCE PLATFORMS
12.2.4 BRAND-OWNED WEBSITES
12.2.5 AGROVET STORES
12.2.6 PHARMACIES & DRUG STORES
12.2.7 SUBSCRIPTION-BASED PLATFORMS
12.2.8 SUPERMARKETS & HYPERMARKETS
12.2.9 CONVENIENCE STORES
12.2.10 OTHERS
13 MEXICO PET CARE PRODUCTS MARKET, BY FORM
13.1 OVERVIEW
13.2 MEXICO PET CARE PRODUCTS MARKET, BY FORM, 2018-2033 (USD THOUSAND)
13.2.1 DRY
13.2.2 WET
13.2.3 TABLET & CHEWABLE
13.2.4 LIQUID
13.2.5 TOPICAL
13.2.6 POWDER
13.2.7 INJECTABLE
13.2.8 SPRAY
13.2.9 OTHERS
14 MEXICO PET CARE PRODUCTS MARKET, BY PACKAGING TYPE
14.1 OVERVIEW
14.2 MEXICO PET CARE PRODUCTS MARKET, BY PACKAGING TYPE, 2018-2033 (USD THOUSAND)
14.2.1 BOTTLES
14.2.2 BOXES & CARTONS
14.2.3 BLISTER PACKS
14.2.4 TUBES & SACHETS
14.2.5 VIALS & AMPOULES
14.2.6 BULK PACKAGING
14.2.7 OTHERS
15 MEXICO PET CARE PRODUCTS MARKET, BY END USER
15.1 OVERVIEW
15.2 MEXICO PET CARE PRODUCTS MARKET, BY END USER, 2018-2033 (USD THOUSAND)
15.2.1 HOUSEHOLD PET OWNERS
15.2.2 VETERINARY INSTITUTIONS
15.2.3 PET GROOMING CENTERS
15.2.4 PROFESSIONAL BREEDERS
15.2.5 ANIMAL SHELTERS & RESCUE CENTERS
15.2.6 OTHERS
16 MEXICO PET CARE PRODUCTS MARKET
16.1 COMPANY SHARE ANALYSIS: MEXICO
17 SWOT ANALYSIS
18 COMPANY PROFILES - GLOBAL COMPANIES
18.1 ZOETIS SERVICES LLC
18.1.1 COMPANY SNAPSHOT
18.1.2 REVENUE ANALYSIS
18.1.3 PRODUCT PORTFOLIO
18.1.4 RECENT DEVELOPMENT
18.2 MERCK & CO., INC
18.2.1 COMPANY SNAPSHOT
18.2.2 REVENUE ANALYSIS
18.2.3 PRODUCT PORTFOLIO
18.2.4 RECENT DEVELOPMENT
18.3 BOEHRINGER INGELHEIM INTERNATIONAL GMBH
18.3.1 COMPANY SNAPSHOT
18.3.2 PRODUCT PORTFOLIO
18.3.3 RECENT DEVELOPMENT
18.4 ELANCO
18.4.1 COMPANY SNAPSHOT
18.4.2 REVENUE ANALYSIS
18.4.3 PRODUCT PORTFOLIO
18.4.4 RECENT DEVELOPMENT
18.5 CEVA
18.5.1 COMPANY SNAPSHOT
18.5.2 PRODUCT PORTFOLIO
18.5.3 RECENT DEVELOPMENT
18.6 BIMEDA CORPORATE
18.6.1 COMPANY SNAPSHOT
18.6.2 PRODUCT PORTFOLIO
18.6.3 RECENT DEVELOPMENT/NEWS
18.7 PHIBRO
18.7.1 COMPANY SNAPSHOT
18.7.2 PRODUCT PORTFOLIO
18.7.3 RECENT DEVELOPMENT/NEWS
18.8 VETNIL
18.8.1 COMPANY SNAPSHOT
18.8.2 PRODUCT PORTFOLIO
18.8.3 RECENT DEVELOPMENT/NEWS
18.9 VETOQUINOL
18.9.1 COMPANY SNAPSHOT
18.9.2 REVENUE ANALYSIS
18.9.3 PRODUCT PORTFOLIO
18.9.4 RECENT DEVELOPMENT
18.1 VIRBAC
18.10.1 COMPANY SNAPSHOT
18.10.2 REVENUE ANALYSIS
18.10.3 PRODUCT PORTFOLIO
18.10.4 RECENT DEVELOPMENT
19 COMPANY PROFILES- DOMESTIC COMPANIES
19.1 AGRO ANIMAL HEALTH SA DE CV
19.1.1 COMPANY SNAPSHOT
19.1.2 PRODUCT PORTFOLIO
19.1.3 RECENT DEVELOPMENT
19.2 ALPHACHEM
19.2.1 COMPANY SNAPSHOT
19.2.2 PRODUCT PORTFOLIO
19.2.3 RECENT DEVELOPMENT
19.3 ANDOCI
19.3.1 COMPANY SNAPSHOT
19.3.2 PRODUCT PORTFOLIO
19.3.3 RECENT DEVELOPMENT/NEWS
19.4 AVIMEX SALUD ANIMAL
19.4.1 COMPANY SNAPSHOT
19.4.2 PRODUCT PORTFOLIO
19.4.3 RECENT DEVELOPMENT
19.5 PECUARIUS MÉXICO
19.5.1 COMPANY SNAPSHOT
19.5.2 PRODUCT PORTFOLIO
19.5.3 RECENT DEVELOPMENT/NEWS
19.6 PET'S PHARMA
19.6.1 COMPANY SNAPSHOT
19.6.2 PRODUCT PORTFOLIO
19.6.3 RECENT DEVELOPMENT/NEWS
19.7 VETS PHARMA
19.7.1 COMPANY SNAPSHOT
19.7.2 PRODUCT PORTFOLIO
19.7.3 RECENT DEVELOPMENT
20 QUESTIONNAIRE
21 RELATED REPORT
List of Table
TABLE 1 MEXICO CLINICAL TRIAL MARKET FOR PET CARE PRODUCTS
TABLE 2 REPRESENTATIVE MARKETED BRANDS IN MEXICO
TABLE 3 MAJOR GENERIC MOLECULES:
TABLE 4 MAJOR THERAPEUTIC CATEGORIES
TABLE 5 MAJOR PHARMACOLOGICAL CLASSIFICATIONS INCLUDE:
TABLE 6 MAJOR PRODUCT TYPES:
TABLE 7 COMMON DOSAGE FORMS INCLUDE:
TABLE 8 COMMON PACKAGING FORMATS INCLUDE:
TABLE 9 MAJOR DOSING FREQUENCY CATEGORIES INCLUDE:
TABLE 10 MEXICO PET CARE PRODUCTS MARKET FORECAST, 2024–2033 (USD MILLION)
TABLE 11 COMPARATIVE IMPACT OF IMPORT DUTIES
TABLE 12 MEXICO PET CARE PRODUCTS MARKET, BY PRODUCT CATEGORY, 2018-2033 (USD THOUSAND)
TABLE 13 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY PARASITE TYPE, 2018-2033 (USD THOUSAND)
TABLE 14 MEXICO ECTOPARASITICIDES IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 15 MEXICO ENDOPARASITICIDES IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 16 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY DRUG CLASS, 2018-2033 (USD THOUSAND)
TABLE 17 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY FORM, 2018-2033 (USD THOUSAND)
TABLE 18 MEXICO TOPICAL PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 19 MEXICO ORAL PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 20 MEXICO ANTIPARASITICS IN PET CARE PRODUCTS MARKET, BY PREVENTION TYPE, 2018-2033 (USD THOUSAND)
TABLE 21 MEXICO ANTIMICROBIALS IN PET CARE PRODUCTS MARKET, BY DRUG CLASS, 2018-2033 (USD THOUSAND)
TABLE 22 MEXICO ANTIMICROBIALS IN PET CARE PRODUCTS MARKET, BY INDICATION, 2018-2033 (USD THOUSAND)
TABLE 23 MEXICO ANTIMICROBIALS IN PET CARE PRODUCTS MARKET, BY FORM, 2018-2033 (USD THOUSAND)
TABLE 24 MEXICO ORAL PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 25 MEXICO INJECTABLE PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 26 MEXICO TOPICAL & DERMATOLOGY PRODUCTS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 27 MEXICO EYE & EAR PREPARATIONS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 28 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY PRODUCT TYPE, 2018-2033 (USD THOUSAND)
TABLE 29 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY ADMINISTRATION ROUTE, 2018-2033 (USD THOUSAND)
TABLE 30 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY PROCEDURE TYPE, 2018-2033 (USD THOUSAND)
TABLE 31 MEXICO ANESTHETICS IN PET CARE PRODUCTS MARKET, BY DURATION TYPE, 2018-2033 (USD THOUSAND)
TABLE 32 MEXICO PET CARE PRODUCTS MARKET, BY PET TYPE, 2018-2033 (USD THOUSAND)
TABLE 33 MEXICO DOGS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 34 MEXICO CATS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 35 MEXICO SMALL MAMMALS IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 36 MEXICO PET CARE PRODUCTS MARKET, BY ROUTE OF ADMINISTRATION, 2018-2033 (USD THOUSAND)
TABLE 37 MEXICO ORAL IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 38 MEXICO TOPICAL IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 39 MEXICO PARENTERAL IN PET CARE PRODUCTS MARKET, BY TYPE, 2018-2033 (USD THOUSAND)
TABLE 40 MEXICO PET CARE PRODUCTS MARKET, BY PRESCRIPTION TYPE, 2018-2033 (USD THOUSAND)
TABLE 41 MEXICO PET CARE PRODUCTS MARKET, BY DISTRIBUTION CHANNEL, 2018-2033 (USD THOUSAND)
TABLE 42 MEXICO PET CARE PRODUCTS MARKET, BY FORM, 2018-2033 (USD THOUSAND)
TABLE 43 MEXICO PET CARE PRODUCTS MARKET, BY PACKAGING TYPE, 2018-2033 (USD THOUSAND)
TABLE 44 MEXICO PET CARE PRODUCTS MARKET, BY END USER, 2018-2033 (USD THOUSAND)
List of Figure
FIGURE 1 MEXICO PET CARE PRODUCTS MARKET: SEGMENTATION
FIGURE 2 MEXICO PET CARE PRODUCTS MARKET: DATA TRIANGULATION
FIGURE 3 MEXICO PET CARE PRODUCTS MARKET: DROC ANALYSIS
FIGURE 4 MEXICO PET CARE PRODUCTS MARKET: VS REGIONAL MARKET ANALYSIS
FIGURE 5 MEXICO PET CARE PRODUCTS MARKET: COMPANY RESEARCH ANALYSIS
FIGURE 6 MEXICO PET CARE PRODUCTS MARKET: MULTIVARIATE MODELLING
FIGURE 7 MEXICO PET CARE PRODUCTS MARKET: INTERVIEW DEMOGRAPHICS
FIGURE 8 MEXICO PET CARE PRODUCTS MARKET: DBMR MARKET POSITION GRID
FIGURE 9 MEXICO PET CARE PRODUCTS MARKET: MARKET END USER COVERAGE GRID
FIGURE 10 MEXICO PET CARE PRODUCTS MARKET: VENDOR SHARE ANALYSIS
FIGURE 11 MEXICO PET CARE PRODUCTS MARKET: SEGMENTATION
FIGURE 12 EXECUTIVE SUMMARY
FIGURE 13 MEXICO PET CARE PRODUCTS MARKET, BY PRODUCT CATEGORY (2025)
FIGURE 14 STRATEGIC DECISIONS
FIGURE 15 RISING PET OWNERSHIP IN MEXICO IS DRIVING THE MEXICO PET CARE PRODUCTS MARKET FROM 2026 TO 2033
FIGURE 16 ANTIPARASITICS SEGMENT IS EXPECTED TO ACCOUNT FOR THE LARGEST SHARE OF THE MEXICO PET CARE PRODUCTS MARKET IN 2026 & 2033
FIGURE 17 TOP ENTITIES BASED ON R&D GLANCE FOR MEXICO PET CARE PRODUCTS
FIGURE 18 DROC ANALYSIS
FIGURE 19 MEXICO PET CARE PRODUCTS MARKET: BY PRODUCT CATEGORY, 2025 (USD THOUSAND)
FIGURE 20 MEXICO PET CARE PRODUCTS MARKET: BY PET TYPE, 2025 (USD THOUSAND)
FIGURE 21 MEXICO PET CARE PRODUCTS MARKET: BY ROUTE OF ADMINISTRATION, 2025 (USD THOUSAND)
FIGURE 22 MEXICO PET CARE PRODUCTS MARKET: BY PRESCRIPTION TYPE, 2025 (USD THOUSAND)
FIGURE 23 MEXICO PET CARE PRODUCTS MARKET: BY DISTRIBUTION CHANNEL, 2025 (USD THOUSAND)
FIGURE 24 MEXICO PET CARE PRODUCTS MARKET: BY FORM, 2025 (USD THOUSAND)
FIGURE 25 MEXICO PET CARE PRODUCTS MARKET: BY PACKAGING TYPE, 2025 (USD THOUSAND)
FIGURE 26 MEXICO PET CARE PRODUCTS MARKET: BY END USER, 2025 (USD THOUSAND)
FIGURE 27 MEXICO PET CARE PRODUCTS MARKET: COMPANY SHARE 2025 (%)

Mexico Pet Care Products Market, Supply Chain Analysis and Ecosystem Framework
To support market growth and help clients navigate the impact of geopolitical shifts, DBMR has integrated in-depth supply chain analysis into its Mexico Pet Care Products Market research reports. This addition empowers clients to respond effectively to global changes affecting their industries. The supply chain analysis section includes detailed insights such as Mexico Pet Care Products Market consumption and production by country, price trend analysis, the impact of tariffs and geopolitical developments, and import and export trends by country and HSN code. It also highlights major suppliers with data on production capacity and company profiles, as well as key importers and exporters. In addition to research, DBMR offers specialized supply chain consulting services backed by over a decade of experience, providing solutions like supplier discovery, supplier risk assessment, price trend analysis, impact evaluation of inflation and trade route changes, and comprehensive market trend analysis.
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.