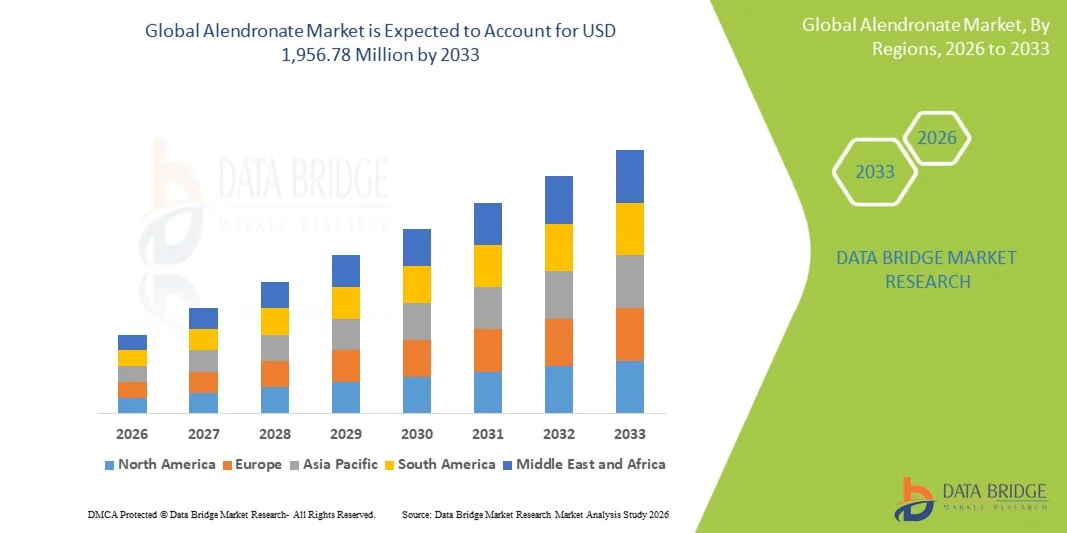
What is the Alendronate Market Size and Growth Rate?
- As per Data Bridge Market Research analysis, the alendronate market was valued at USD 1,486.0 million in 2025 and is projected to reach USD 1,956.78 million by 2033, growing at a CAGR of 3.5% from 2026 to 2033.
- The market is experiencing steady growth driven by the rising global prevalence of osteoporosis among postmenopausal women and the aging population, growing awareness of early bone-density screening, and continued reliance on alendronate as a first-line, cost-effective bisphosphonate therapy.
- The increasing burden of fragility fractures among geriatric populations, combined with expanding government screening and reimbursement programs for osteoporosis management, is compelling healthcare providers to prescribe alendronate as a foundational therapy for both prevention and treatment. Widespread availability of low-cost generic formulations following patent expiry continues to support sustained prescribing volumes across both developed and price-sensitive healthcare markets.
- Continued clinical emphasis on weekly and once-daily oral dosing regimens, along with combination formulations incorporating vitamin D3, is improving patient convenience and adherence, reinforcing alendronate's position as a preferred oral bisphosphonate relative to more complex intravenous alternatives.
- Continued global patent expiry of branded alendronate formulations has opened the market to widespread generic competition, driving down treatment costs and expanding patient access across public healthcare systems in both developed and emerging economies.
Market Size & Forecast
- Global Market Value (2025): USD 1,486.0 Million
- Expected Market Value (2033): USD 1,956.78 Million
- Forecast CAGR (2026–2033): 3.5%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Alendronate Market?
- North America dominated the global alendronate market with the largest revenue share of 36.24% in 2025, supported by high osteoporosis diagnosis rates and well-established generic drug distribution networks.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 5.2% from 2026 to 2033, fueled by rising geriatric population, growing bone-health awareness, and increasing generic drug manufacturing capacity in India and China.
- The tablets segment led the market with a 68.47% share in 2025, driven by ease of administration, established weekly dosing protocols, and widespread availability across retail and hospital pharmacies.
- The effervescent tablets segment is the fastest-growing formulation type, projected to register a CAGR of 5.6%, reflecting rising patient preference for formulations that reduce esophageal irritation risk associated with conventional tablets.
- The postmenopausal osteoporosis application segment dominated the application category with a 58.32% revenue share in 2025, led by alendronate's established role as a first-line therapy for bone-density preservation in aging women.
- The generic product type accounted for 74.86% of the market share in 2025, preferred for its cost-effectiveness and broad accessibility following patent expiry in major markets.
- The alendronate + vitamin D3 combination formulation is the fastest-growing formulation segment, with a CAGR of 5.4%, driven by rising clinical preference for simplified single-pill regimens that improve calcium and bone-metabolism support.
Report Scope and Alendronate Market Segmentation
|
Attributes |
Alendronate Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, patient epidemiology, pipeline analysis, pricing analysis, and regulatory framework. |
What is the Key Trend in the Alendronate Market?
- Generic pharmaceutical manufacturers are increasingly expanding their alendronate product portfolios across weekly-dose tablets, effervescent tablets, and vitamin D3 combination formulations to improve affordability and treatment adherence for osteoporosis patients.
- For instance, in April 2025, Sun Pharmaceutical Industries expanded its generic alendronate portfolio in emerging markets, including 70 mg weekly-dose tablets and combination formulations, to strengthen access to affordable bone-health therapies.
- Rising adoption of effervescent alendronate tablets is enabling patients with gastrointestinal sensitivity to better tolerate long-term bisphosphonate therapy, improving treatment persistence and reducing therapy discontinuation rates.
- Healthcare providers and public health agencies are increasingly incorporating bone-density screening initiatives into routine geriatric and postmenopausal care programs, driving earlier diagnosis and treatment initiation with alendronate.
- For instance, in January 2025, Cipla partnered with regional public health agencies to expand distribution of alendronate combination formulations under an osteoporosis awareness and essential-medicines access initiative.
- As healthcare systems continue to prioritize affordable, accessible bone-health management, the adoption of alendronate is expected to remain steady, reinforcing its role as a cost-effective first-line oral bisphosphonate across both developed and emerging markets.
What are the Key Drivers of the Alendronate Market?
- The rising global prevalence of osteoporosis, particularly among postmenopausal women and the aging population, has significantly increased demand for established, cost-effective bisphosphonate therapies capable of reducing fracture risk.
- For instance, in March 2025, Teva Pharmaceutical Industries expanded its generic alendronate manufacturing capacity to meet rising demand for tablets and combination formulations across North America and Europe.
- Hospitals, specialty clinics, and public healthcare systems are increasingly incorporating alendronate into osteoporosis treatment protocols to reduce therapy costs, broaden patient access, and manage large aging patient populations efficiently.
- For instance, in October 2024, Zydus Lifesciences announced an investment in additional oral-solid manufacturing capacity to support rising orders for alendronate and other generic bone-health therapies.
- With healthcare systems increasingly relying on affordable generics to manage rising osteoporosis caseloads, alendronate will remain indispensable for the prevention and treatment of postmenopausal, male, and glucocorticoid-induced osteoporosis.
Which Factors are Challenging the Growth of the Alendronate Market?
- Alendronate therapy is associated with gastrointestinal side effects, including esophageal irritation and acid reflux, along with rare risks of osteonecrosis of the jaw and atypical femoral fractures with long-term use, which can limit treatment persistence.
- These tolerability and long-term safety concerns limit adoption among certain patient populations and prompt clinicians to consider alternative osteoporosis therapies or drug holidays after extended use.
- For instance, in September 2024, the Endocrine Society highlighted the importance of reassessing long-term bisphosphonate therapy and considering individualized treatment duration for patients receiving osteoporosis medications.
- The availability of newer osteoporosis therapies, including injectable and monoclonal antibody-based treatments with less frequent dosing requirements, continues to restrict growth, particularly in developed markets with broader insurance coverage. This preference shift slows market penetration in price-insensitive regions, limiting the expansion of alendronate despite its established efficacy and low cost.
How is the Alendronate Market Segmented?
The alendronate market is segmented on the basis of type, dosage strength, application, formulation, product type, end user, distribution channel, packaging type, patient age group and sales channel.
- By Type
On the basis of type, the global alendronate market is segmented into tablets, effervescent tablets, and oral solution. The tablets segment dominated the market with a 68.47% share in 2025, owing to established weekly dosing protocols, broad patient familiarity, and widespread availability across retail and hospital pharmacies. These formulations deliver consistent dosing, making them the preferred choice for long-term outpatient management of osteoporosis.
The effervescent tablets segment is projected to register the fastest growth at a CAGR of 5.6% from 2026 to 2033, driven by rising patient preference for formulations that dissolve fully before ingestion, reducing esophageal irritation risk associated with conventional tablets. Advances in effervescent formulation technology, combined with growing physician recommendation for patients with swallowing difficulties, are accelerating segment expansion.
- By Dosage Strength
On the basis of dosage strength, the global alendronate market is segmented into 5 mg, 10 mg, 35 mg, 70 mg, and others. The 70 mg segment led the market with a 61.38% share in 2025, supported by its widespread prescription as the standard once-weekly maintenance dose for postmenopausal osteoporosis patients.
The 35 mg segment is expected to experience the fastest growth at a CAGR of 5.1% from 2026 to 2033, driven by increasing use of once-weekly preventive-dose formulations among patients with osteopenia and early-stage bone-density loss.
- By Application
On the basis of application, the global alendronate market is segmented into postmenopausal osteoporosis, male osteoporosis, glucocorticoid-induced osteoporosis, Paget's disease of bone, and others. The postmenopausal osteoporosis segment dominated the market with a share of 58.32% in 2025 due to its widespread adoption as a first-line therapy for bone-density preservation, increasing diagnosis rates, and growing integration with routine geriatric care protocols. Additionally, rising focus on affordable long-term fracture-prevention management further supports the strong adoption of alendronate-based treatment.
The glucocorticoid-induced osteoporosis segment is anticipated to witness the fastest CAGR of 5.3% from 2026 to 2033, driven by the increasing reliance on alendronate as a preventive therapy for patients undergoing long-term corticosteroid treatment for chronic inflammatory and autoimmune conditions. Clinicians are adopting established bisphosphonate protocols to conduct cost-effective, accessible, and repeatable bone-density protection. Additionally, the integration of alendronate into standard-of-care corticosteroid treatment guidelines is enhancing the accuracy and efficiency of glucocorticoid-induced osteoporosis management, further driving segment growth.
- By Formulation
On the basis of formulation, the global alendronate market is segmented into alendronate alone and alendronate + vitamin D3 combination. The alendronate alone segment dominated the market with a share of 64.75% in 2025 due to its critical role in providing established, flexible dosing options that allow physicians to prescribe vitamin D3 supplementation separately based on individual patient needs. The widespread availability of standalone generic formulations across multiple manufacturers is driving strong demand for this formulation type.
The alendronate + vitamin D3 combination segment is expected to witness the fastest CAGR of 5.4% from 2026 to 2033, driven by the rising clinical preference for simplified single-pill regimens that improve patient adherence by reducing overall pill burden. Physicians are increasingly prescribing combination formulations to streamline bone-metabolism support. Additionally, the growing emphasis on adherence-focused treatment in geriatric care is further accelerating adoption of this formulation type.
- By Product Type
On the basis of product type, the global alendronate market is segmented into branded and generic. The generic segment dominated the market with a share of 74.86% in 2025 due to its critical role in providing affordable, accessible bisphosphonate therapy across public and private healthcare systems. High adoption is driven by the increasing need for cost-effective treatment options, expiry of patent protections, and enhanced availability across multiple manufacturers. Additionally, growing investment by generic drug makers, government procurement agencies, and public health programs to improve affordability and access is reinforcing the leading position of this segment in the market.
The generic segment is expected to witness the fastest CAGR of 4.1% from 2026 to 2033. This growth is driven by increasing demand for low-cost osteoporosis therapies that expand treatment access across public healthcare systems. Growing manufacturing capacity among generic drug producers, along with regulatory support for essential medicines, is improving affordability and supply consistency. Additionally, the adoption of generics in public healthcare procurement programs is further accelerating market expansion.
- By End User
On the basis of end user, the global alendronate market is segmented into hospitals, specialty clinics, homecare settings, and long-term care facilities. The specialty clinics segment dominated the market with a share of 39.84% in 2025 due to its widespread role in osteoporosis diagnosis, bone-density screening, and long-term treatment monitoring across endocrinology and orthopedic care settings. Rising adoption of structured osteoporosis management protocols, integrated pharmacy supply chains, and routine screening programs is enabling specialty clinics to enhance treatment consistency, improve patient outcomes, and optimize resource utilization. Additionally, increasing investment by public health systems, clinic networks, and bone-health care institutions is accelerating adoption and reinforcing this segment's leading position in the market.
The homecare settings segment is expected to witness the fastest CAGR of 5.5% from 2026 to 2033, driven by the increasing adoption of outpatient and home-based osteoporosis management models that reduce treatment costs and improve patient quality of life for long-term bisphosphonate therapy. These care models enhance medication adherence, reduce clinic-visit burden, and allow personalized treatment monitoring, making alendronate therapy more accessible, sustainable, and valuable for chronic disease management.
- By Distribution Channel
On the basis of distribution channel, the global alendronate market is segmented into hospital pharmacies, retail pharmacies, and online pharmacies. The retail pharmacies segment dominated the market with a share of 47.62% in 2025 due to its widespread adoption in outpatient osteoporosis management, which requires convenient, recurring access to weekly-dose oral medications. High adoption is supported by community pharmacy networks, healthcare providers, and patients who rely on established retail pharmacy relationships to ensure consistency, convenience, and measurable treatment outcomes. Additionally, increasing integration with electronic prescribing and refill-reminder systems enhances dispensing accuracy and reinforces the dominance of the retail pharmacies segment.
The online pharmacies segment is expected to witness the fastest CAGR of 6.1% from 2026 to 2033. This growth is primarily driven by the increasing demand for convenient, accessible, and cost-effective medication delivery solutions for chronic osteoporosis therapy patients. By offering home delivery and refill-management services, this channel enhances medication adherence, patient convenience, and treatment continuity, making it highly attractive for long-term bisphosphonate therapy management and homecare patient populations.
- By Packaging Type
On the basis of packaging type, the global alendronate market is segmented into blister packs and bottles. The blister packs segment dominated the market with a share of 58.29% in 2025 due to its critical role in ensuring dosage accuracy, product stability, and tamper-evident packaging for weekly-dose oral tablet formulations. Additionally, established partnerships with contract packaging providers, pharmacy distributors, and generic drug manufacturers are expanding reach, improving accessibility, and reinforcing the adoption of blister-packaged alendronate across global markets.
The bottles segment is expected to witness the fastest CAGR of 4.6% from 2026 to 2033. This growth is primarily driven by the increasing demand for bulk-dispensed formulations used in institutional and long-term care settings. Manufacturers and healthcare providers are leveraging cost-efficient bottle packaging to support high-volume dispensing, enable simplified inventory management, and support institutional procurement protocols, thereby accelerating adoption across hospital and long-term care applications.
- By Patient Age Group
On the basis of patient age group, the global alendronate market is segmented into adults and geriatric. The geriatric segment dominated the market with a share of 71.53% in 2025 due to its preference among the largest patient population diagnosed with osteoporosis and related age-related bone-density loss requiring long-term bisphosphonate management. Additionally, established treatment protocols, broad prescriber familiarity, and extensive clinical usage history are facilitating continued adoption of alendronate among geriatric patients, while strong healthcare provider networks are improving accessibility, reliability, and trust, further reinforcing this segment's leading market position.
The adults segment is expected to witness the fastest CAGR of 4.9% from 2026 to 2033, driven by the increasing prevalence of early-onset osteopenia and preventive bone-density management among younger postmenopausal and glucocorticoid-treated adult patients. Healthcare providers offer proactive screening and early-intervention treatment regimens for at-risk adult patients, while providing enhanced monitoring, dose-titration guidance, and seamless integration with preventive care management, enhancing overall treatment safety and effectiveness.
- By Sales Channel
On the basis of sales channel, the global alendronate market is segmented into prescription-based and institutional procurement. The prescription-based segment dominated the market with a share of 84.67% in 2025 due to its critical role in ensuring appropriate clinical oversight, dosage control, and monitoring for bisphosphonate therapy across hospitals, clinics, and retail pharmacies. The widespread presence of regulatory frameworks governing osteoporosis medication dispensing facilitates controlled access, localized prescriber support, and timely treatment adjustment. Additionally, collaborations with healthcare providers, pharmacy networks, and regulatory agencies are enhancing product accessibility, reliability, and trust, further reinforcing the leading position of the prescription-based segment in the global market.
The institutional procurement segment is expected to witness the fastest CAGR of 5.0% from 2026 to 2033, driven by growing bulk purchasing of alendronate formulations by public hospital networks, long-term care institutions, and government essential-medicine programs. As healthcare systems increasingly centralize procurement to manage costs and ensure supply continuity, institutional channels are becoming an increasingly important route for alendronate distribution, particularly across public healthcare systems in emerging markets.
Which Region Holds the Largest Share of the Alendronate Market?
- North America dominated the alendronate market and accounted for the largest revenue share of 36.24% in 2025, supported by high osteoporosis diagnosis rates, well-established generic drug distribution networks, and the presence of established pharmaceutical manufacturing and healthcare infrastructure.
- The region also benefits from broad insurance coverage for osteoporosis medications, high adoption of retail and specialty clinic distribution channels, and growing use of alendronate across preventive and long-term bone-health treatment applications. Increasing focus on affordable generic therapies and expanding homecare treatment models continues to strengthen North America's leadership position in the global market.
U.S. Alendronate Market Insight
The U.S. alendronate market remains significant due to the country’s large aging population and high prevalence of osteoporosis. Alendronate is widely used as an oral bisphosphonate for fracture prevention and remains one of the most commonly used osteoporosis therapies in the U.S. The market is supported by established clinical use, generic availability, and cost advantages. However, competition from denosumab and newer osteoporosis therapies, alongside concerns regarding long-term bisphosphonate use, may limit future growth.
Canada Alendronate Market Insight
Canada’s alendronate market is supported by established osteoporosis treatment guidelines, generic availability, and continued use of oral bisphosphonates. Canadian guidelines recommend alendronate, risedronate, or zoledronic acid as initial pharmacological options for eligible patients. Multiple generic alendronate products are marketed in Canada, creating a competitive and cost-sensitive environment. However, competition from risedronate, denosumab, and other therapies, along with changing treatment patterns, can constrain market expansion.
Asia-Pacific Alendronate Market Insight
The Asia-Pacific alendronate market is supported by increasing osteoporosis prevalence, population aging, and growing awareness of fracture prevention. Alendronate remains a widely accessible bisphosphonate across the region, benefiting from established clinical use and relatively affordable treatment costs. However, significant differences in healthcare infrastructure, diagnosis, reimbursement, and treatment access remain across countries. Rising demand for osteoporosis management, particularly in rapidly aging markets, is expected to create continued opportunities for alendronate.
China Alendronate Market Insight
The China alendronate market is expanding steadily, supported by rising diagnosis and treatment rates for osteoporosis among the aging population, growing domestic generic drug manufacturing, and increasing investments in bone-health screening infrastructure. Hospitals and public health institutions are increasingly utilizing alendronate for both preventive and long-term osteoporosis care. Continuous expansion of hospital pharmacy networks, government essential-medicine procurement programs, and rising healthcare access in rural regions are further driving market growth in China.
Japan Alendronate Market Insight
The Japan alendronate market is witnessing consistent growth due to rising investments in geriatric care infrastructure, increasing awareness of osteoporosis-related fracture risk, and continued clinical reliance on established bisphosphonate therapies for the country's rapidly aging population. Hospitals, geriatric care facilities, and research institutes are increasingly adopting alendronate for both osteoporosis management and preventive bone-density care. Moreover, the country's aging demographic profile and focus on affordable, well-tolerated treatment options are further contributing to market growth.
Which are the Top Companies in Alendronate Market?
The alendronate industry is primarily led by well-established companies, including:
- Merck & Co., Inc. (U.S.)
- Teva Pharmaceutical Industries Ltd. (Israel)
- Viatris Inc. (U.S.)
- Sun Pharmaceutical Industries Ltd. (India)
- Cipla Ltd. (India)
- Dr. Reddy's Laboratories Ltd. (India)
- Aurobindo Pharma Limited (India)
- Lupin Limited (India)
- Zydus Lifesciences Ltd. (India)
- Alkem Laboratories Ltd. (India)
- Torrent Pharmaceuticals Ltd. (India)
- Intas Pharmaceuticals Ltd. (India)
- Macleods Pharmaceuticals Ltd. (India)
- Ajanta Pharma Ltd. (India)
- Cadila Pharmaceuticals Ltd. (India)
- Hetero Drugs Limited (India)
- Natco Pharma Limited (India)
- Wockhardt Ltd. (India)
- Hikma Pharmaceuticals PLC (U.K.)
- Amneal Pharmaceuticals, Inc. (U.S.)
- Sandoz International GmbH (Germany)
- Zentiva Group, a.s. (Czech Republic)
- Accord Healthcare Limited (U.K.)
- Glenmark Pharmaceuticals Ltd. (India)
- Actavis (a Teva company) (U.S.)
- Apotex Inc. (Canada)
- Cosette Pharmaceuticals, Inc. (U.S.)
- Alvogen, Inc. (U.S.)
- Rising Pharmaceuticals, Inc. (U.S.)
- Par Pharmaceutical, Inc. (Endo) (U.S.)
What are Latest Developments in Alendronate Market?
- In September 2025, Sun Pharmaceutical Industries expanded its generic alendronate manufacturing facility in India to increase production capacity for weekly-dose tablets and combination formulations, strengthening its ability to serve growing demand across emerging markets.
- In February 2025, Cipla launched an affordability-focused essential-medicines initiative that included expanded distribution of alendronate formulations across public healthcare centers in South Asia and Sub-Saharan Africa.
- In November 2025, Zydus Lifesciences received regulatory approval for an additional alendronate + vitamin D3 combination tablet strength, improving treatment simplification options for hospital and specialty-clinic customers. This development strengthens Zydus's position in the generic osteoporosis therapeutics market by enabling faster response to institutional procurement demand.
- In October 2024, Hikma Pharmaceuticals expanded its oral-solid osteoporosis therapy portfolio in North America and Europe to include additional alendronate dosage strengths, improving supply continuity for specialty-clinic and long-term care providers.
- In June 2023, Teva Pharmaceutical Industries partnered with a regional distributor network to expand availability of alendronate tablets and combination formulations across underserved markets, combining its generic manufacturing scale with the partner's regional pharmacy distribution capabilities to support broader patient access.
- In March 2023, Aurobindo Pharma received manufacturing approval from a regional regulatory authority for an additional alendronate effervescent tablet production line, enabling the company to expand supply to patients with swallowing difficulties and gastrointestinal sensitivity.

- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.