What is the Biofungicides for Soil Treatment Market Size and Growth Rate?
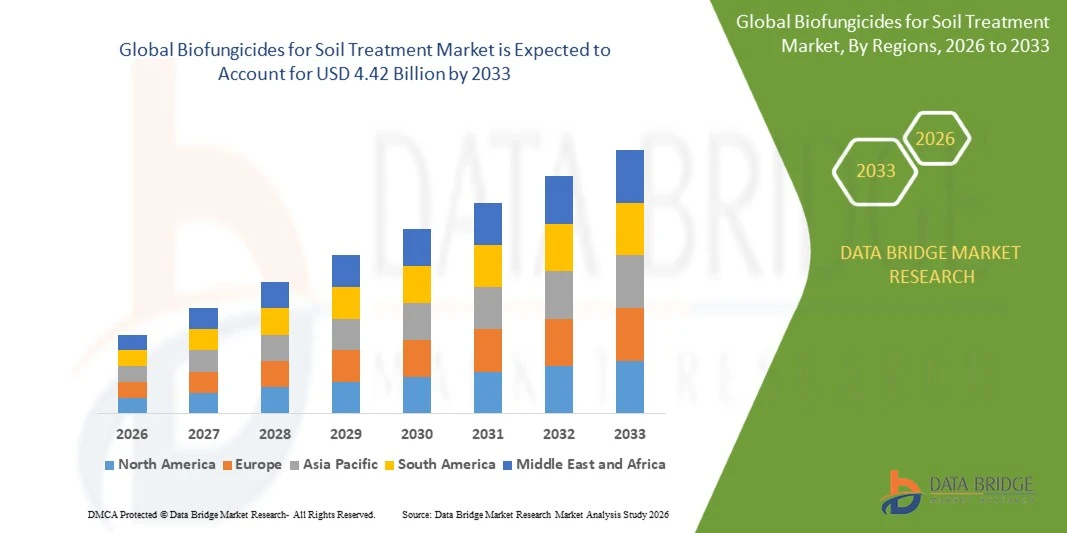
- As per Data Bridge Market Research analysis, the biofungicides for soil treatment market was valued at USD 1.32 billion in 2025 and is projected to reach USD 4.42 billion by 2033, growing at a CAGR of 16.30% from 2026 to 2033, across sustainable crop protection programs.
- The market is experiencing rapid growth driven by rising demand for sustainable crop protection, increasing soil-borne disease pressure, and expanding applications across fruits, vegetables, cereals, oilseeds, greenhouse crops, turf, and ornamental production worldwide.
- The increasing shift toward integrated pest management, residue-free produce, and reduced reliance on synthetic chemistry, combined with growing grower awareness of root-zone health and beneficial microbes, is supporting market adoption. Biofungicides for soil treatment are being applied across drench, in-furrow, irrigation, and granular programs, using beneficial fungi and bacteria to protect roots from pathogens such as Pythium, Rhizoctonia, and Fusarium within modern biopesticide strategies.
Market Size & Forecast
- Global Market Value (2025): USD 1.32 Billion
- Expected Market Value (2033): USD 4.42 Billion
- Forecast CAGR (2026–2033): 16.30%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia-Pacific
What are the Major Takeaways of the Biofungicides for Soil Treatment Market?
- North America dominated the biofungicides for soil treatment market with the largest revenue share of 34.80% in 2025, supported by strong adoption of biologicals, established suppliers, and widespread specialty crop and greenhouse production across the region and neighboring markets.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 19.40% from 2026 to 2033, fueled by expanding horticulture, rising organic farming, and growing government support for biological inputs across emerging markets.
- The Trichoderma segment led the market with a 38.7% share in 2025, driven by extensive use in controlling soil-borne fungal pathogens across crops and production systems.
- Bacillus is the fastest-growing product type, projected to register a CAGR of 18.6%, reflecting the surge in demand for versatile, root-colonizing biological solutions for soil disease control.
- The liquid segment dominated the form category with a 46.3% revenue share in 2025, led by ease of application through drench and irrigation systems and existing equipment.
- Fruits and vegetables accounted for 42.6% of the market share in 2025, preferred by increasing demand for residue-free, high-value produce and export markets.
- The greenhouse and nursery growers segment is the fastest-growing end-user category, with a CAGR of 18.1%, driven by intensive production and high crop value.
Report Scope and Biofungicides for Soil Treatment Market Segmentation
|
Attributes |
Biofungicides for Soil Treatment Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include import export analysis, production capacity overview, production consumption analysis, price trend analysis, climate change scenario, supply chain analysis, value chain analysis, raw material/consumables overview, vendor selection criteria, PESTLE Analysis, Porter Analysis, and regulatory framework. |
What is the Key Trend in the Biofungicides for Soil Treatment Market?
- Suppliers are increasingly shifting toward multi-strain and multifunctional soil biologicals, combining Trichoderma, Bacillus, and novel actives to protect roots, improve nutrient availability, and strengthen soil health within integrated disease management programs across crops and regions.
- For instance, in June 2026, Agronova Biotech’s Peptiva Rhyzo, based on Bacillus siamensis PB12 and Bacillus halotolerans PB13, was listed as a soil application in Spain, aimed at nutrient availability, beneficial microbial activity, and improved soil structure, reflecting the shift toward multifunctional biological solutions for root-zone health.
- Novel biological chemistries are broadening the toolbox, with new modes of action and non-traditional actives entering the market alongside established microbial strains used by growers.
- Convenient application formats such as drenches, granules, and irrigation-compatible products are making soil biofungicides easier to integrate into greenhouse, nursery, and open-field programs, including products used as drench, dip, granule, or fertigation inputs.
- For instance, in December 2024, Koppert and Amoéba announced a partnership to launch AXPERA, a biofungicide utilizing amoeba-derived lysate, illustrating innovation beyond conventional microbial strains in biological disease control, with the product positioned within integrated programs that combine microbial and novel biological actives.
- As integrated pest management, residue limits, and soil health priorities continue to strengthen, biofungicides for soil treatment are expected to evolve from niche alternatives into core components of crop protection programs across regions worldwide.
What are the Key Drivers of the Biofungicides for Soil Treatment Market?
- Rising incidence of soil-borne diseases and demand for sustainable alternatives to synthetic fungicides are increasing adoption of biofungicides that protect roots and improve plant establishment and early crop vigor.
- Growing demand for organic and residue-free produce, along with retailer and consumer expectations, is encouraging growers to adopt biological disease control within integrated programs across vegetables, fruits, and ornamentals.
- For instance, in February 2023, Certis Biologicals made SoilGard, based on Trichoderma virens, available to growers across all 50 U.S. states, applied through soil drench, root dip, or irrigation systems, or mixed as dry granules into growing media, giving growers flexibility across production systems.
- With regulatory pressure on synthetic chemistries and expanding specialty crop acreage, biological soil treatments offer flexible, resistance-friendly options for disease management in greenhouse and field crops worldwide and in organic programs.
What Factors Are Challenging the Growth of the Biofungicides for Soil Treatment Market?
- Biofungicide performance depends on living organisms, so soil conditions, temperature, storage, and application timing can affect efficacy, and inconsistent results can reduce grower confidence across seasons.
- For instance, in February 2026, according to Global Agriculture, new rules in the European Union will mandate digital labels for plant protection products from 2028, adding compliance and labeling work for suppliers of crop protection products, including biological products sold in the region.
- Registration requirements vary by country and state, and approval timelines can delay launches, particularly for novel strains, multi-strain products, and products with expanded label claims, which can slow supplier investment.
- Preventive, root-zone biologicals often act more slowly than conventional chemistries, and growers may be reluctant to switch when disease pressure is high and crop value is substantial, so field demonstrations and technical support are important.
- The combination of variable field performance, regulatory complexity, slower activity, and limited grower awareness can constrain expansion among conventional farmers, particularly where established chemical programs already satisfy disease control needs or where growers are cautious about changing practices.
How is the Biofungicides for Soil Treatment Market Segmented?
The biofungicides for soil treatment market is segmented on the basis of product, form, application, and end user across regions.
- By Product
On the basis of product, the biofungicides for soil treatment market is segmented into trichoderma, bacillus, pseudomonas, streptomyces, and others. The trichoderma segment dominated the market with 38.7% share in 2025, supported by extensive use in controlling soil-borne fungal pathogens across crops. Trichoderma strains colonize roots and surrounding soil, compete with pathogens, and produce enzymes that inhibit disease development. They are widely used across vegetables, row crops, orchards, and greenhouse production. Improvements in strain selection, formulation, and shelf life are further strengthening demand. Integration with irrigation systems and growing media also enables flexible application across protected and open-field systems.
The bacillus segment is projected to register the fastest growth at a CAGR of 18.6% from 2026 to 2033, driven by increasing demand for versatile, root-colonizing biological solutions. Bacillus amyloliquefaciens and related species form protective zones around roots, produce antimicrobial compounds, and are suited to stable spore-based formulations. Their applications include potatoes, vegetables, corn, soybeans, and ornamentals. Increasing registration of soil-active products is creating additional demand across growers, distributors, and nurseries. Improvements in spore stability and tank-mix compatibility are enhancing consistency. Broad-spectrum activity is also expanding commercial use. Combination approaches, such as Trichoderma harzianum with Bacillus amyloliquefaciens soil compositions, are also being developed to improve nutrient and moisture retention in the rhizosphere.
- By Form
On the basis of form, the biofungicides for soil treatment market is segmented into liquid, wettable powder, and granules. The liquid segment dominated the market with 46.3% share in 2025, supported by ease of application through drench, in-furrow, and irrigation systems. Liquid formulations offer a balanced combination of dosing accuracy, mixing convenience, and compatibility with existing equipment. Their availability across multiple suppliers and strains expands the potential customer base. Growers use liquids to deliver beneficial microbes directly into the root zone with water. The format also supports fertigation and precision application programs across greenhouse and field crops.
The granules segment is projected to register the fastest growth at a CAGR of 17.9% from 2026 to 2033, supported by increasing adoption in nursery, greenhouse, and potting media programs. Granules can be mixed directly into soil or growing media, providing extended root protection with simple handling. Growers are increasingly choosing formats that reduce mixing steps and application labor. Suppliers are developing dry granules and water-dispersible products that fit automated potting lines and transplant programs. Improved carriers and stability further strengthen the segment’s attractiveness. Storage conditions remain important considerations for expansion. Extended protection of up to 12 weeks has been highlighted for some Trichoderma granule products.
- By Application
On the basis of application, the biofungicides for soil treatment market is segmented into fruits & vegetables, cereals & grains, oilseeds & pulses, and others. The fruits and vegetables segment dominated the application category with 42.6% share in 2025, supported by increasing demand for residue-free, high-value produce. Soil biologicals help protect roots from damping-off, root rot, and wilt diseases. Sustainability goals are increasing the use of biological options in vegetable and fruit programs. Growth in greenhouse and protected cultivation further strengthens demand. Growers are also seeking products that combine disease protection, plant vigor, and compatibility with organic standards across intensive production systems.
The oilseeds and pulses segment is projected to register the fastest growth at a CAGR of 17.5% from 2026 to 2033, driven by increasing soybean and pulse acreage, seedling disease pressure, and interest in biological programs. In-furrow and soil-applied biologicals support emergence and root health in early growth stages. Growers in North America, South America, and Asia-Pacific are testing biological options. Rising demand for sustainable inputs is creating additional opportunities. Compatibility with seed treatments and fertilizers makes soil biofungicides particularly attractive. Supportive extension programs can further improve adoption across regions. Soil products from established brands target Rhizoctonia, Fusarium, Pythium, and Phytophthora in potatoes, tomatoes, and cucurbits.
- By End User
On the basis of end user, the biofungicides for soil treatment market is segmented into commercial farmers, greenhouse & nursery growers, turf & landscape managers, research institutions, and others. The commercial farmers segment dominated the end-user category with 58.4% share in 2025, supported by increasing requirements for scalable, effective soil disease management. Farm operators rely on biologicals to complement chemical programs and meet buyer expectations. The segment applies products through irrigation, in-furrow, and broadcast methods. Increasing acreage under specialty crops is creating further opportunities. Large operations also make cost-effectiveness and distributor support important considerations in purchase decisions for farm managers and cooperatives.
The greenhouse and nursery growers segment is projected to register the fastest growth at CAGR of 18.1% from 2026 to 2033, driven by increasing intensive production, high crop value, and strict disease management requirements. Protected environments favor beneficial microbes because root-zone conditions are controlled and reapplication is practical. Growers are expanding use of drenches, granules, and dips for propagation and potted crops. Closer collaboration with suppliers is accelerating development of tailored programs. Organic certification demand is further supporting adoption. Cost per pot, compatibility, and reliability remain important considerations for deployment across greenhouse and nursery operations.
Which Region Holds the Largest Share of the Biofungicides for Soil Treatment Market?
- North America dominated the biofungicides for soil treatment market with the largest revenue share of 34.80% in 2025, supported by strong adoption of biologicals, established suppliers, and widespread specialty crop and greenhouse production across the region and neighboring markets.
- The region also benefits from strong research capabilities, large specialty crop and greenhouse sectors, and the presence of established biological suppliers, along with growing demand for organic and residue-free produce. Increasing registrations, retail availability, and grower education continue to strengthen North America’s position in the global market, supported by strong distributor and retailer networks.
U.S. Biofungicides for Soil Treatment Market Insight
The U.S. biofungicides for soil treatment market is witnessing consistent growth due to rising investments in biological crop protection, specialty crops, and greenhouse production. Growers, distributors, and suppliers are increasingly focusing on root-zone disease management. Moreover, state-by-state product availability and continued launches of Trichoderma and Bacillus products, supported by strong retail and technical networks, are further contributing to market growth in the U.S., particularly among vegetable, fruit, and nursery growers.
Canada Biofungicides for Soil Treatment Market Insight
Canada’s biofungicides for soil treatment market is gaining traction as growers increasingly adopt sustainable crop protection solutions. Rising demand for organic produce, growing awareness of soil health, and efforts to reduce chemical pesticide use are supporting market development. Microbial products containing beneficial fungi and bacteria help suppress soil-borne pathogens while improving crop resilience. Horticulture, cereals, and high-value crops offer promising opportunities. However, product performance variability, regulatory requirements, and farmer awareness remain important challenges affecting widespread adoption.
Asia-Pacific Biofungicides for Soil Treatment Market Insight
The Asia-Pacific biofungicides for soil treatment market is expected to witness rapid growth, driven by expanding horticulture, rising organic farming, and increasing government support for biological inputs across countries such as India, China, Japan, and Australia. Growing demand for safe food, export-quality produce, and sustainable farming is supporting regional market expansion. In addition, the region’s large smallholder base, local manufacturing of biologicals, and rising grower awareness are accelerating demand for soil biofungicides across horticulture and plantation crops.
China Biofungicides for Soil Treatment Market Insight
China’s biofungicides for soil treatment market is expanding as sustainable agriculture and residue-free crop production gain importance. Beneficial microorganisms, particularly Bacillus and Trichoderma, offer opportunities to control soil-borne diseases in vegetables, cereals, and greenhouse crops. Government support for greener farming, increasing awareness of soil health, and advances in microbial formulations are encouraging adoption. However, registration requirements, inconsistent field performance, storage challenges, and price sensitivity may constrain growth.
India Biofungicides for Soil Treatment Market Insight
The India biofungicides for soil treatment market is experiencing steady growth, supported by expanding horticulture, government focus on natural farming, and rising awareness of biologicals. Input suppliers, farmer organizations, and manufacturers are increasingly seeking affordable, effective Trichoderma-based solutions. Furthermore, growing demand for residue-free produce, local production of biological inputs, and expanding distribution through agri-retail networks are supporting wider adoption of soil biofungicides in India, particularly among vegetable and fruit growers seeking residue-free production.
Which are the Top Companies in Biofungicides for Soil Treatment Market?
The biofungicides for soil treatment industry is primarily led by well-established companies, including:
- BASF SE (Germany)
- Bayer AG (Germany)
- Syngenta Group (Switzerland)
- Corteva, Inc. (U.S.)
- Koppert Biological Systems (Netherlands)
- Certis Biologicals (U.S.)
- BioWorks, Inc. (U.S.)
- Novonesis (Denmark)
- UPL Limited (India)
- FMC Corporation (U.S.)
- Nufarm Limited (Australia)
- Bioceres Crop Solutions (Argentina)
- Andermatt Biocontrol AG (Switzerland)
- Lallemand Inc. (Canada)
- Biobest Group NV (Belgium)
- Rizobacter Argentina S.A. (Argentina)
- SePRO Corporation (U.S.)
- OHP, Inc. (U.S.)
- Agronova Biotech (Spain)
- Lesaffre (France)
What are Latest Developments in Biofungicides for Soil Treatment Market?
- In June 2026, Global Agriculture’s launch tracker listed Agronova Biotech’s Peptiva Rhyzo, a Bacillus siamensis and Bacillus halotolerans soil application in Spain, alongside Syngenta’s Quillibrium biofungicide based on Quillaja saponaria, for Botrytis, sour rot, powdery mildew, and Alternaria in grapes, tomatoes, berries, and cherries in the U.S. and Mexico, highlighting rapid launch activity in biological crop protection.
- In February 2025, a new biofungicide called BELVINE was launched to combat downy mildew and powdery mildew in vineyards while reducing reliance on conventional copper and sulfur-based treatments, illustrating how product innovation is expanding the reach of integrated pest management compatible biological solutions across crops and production systems, including programs used by organic and conventional growers seeking to reduce copper and sulfur use.
- In December 2024, Koppert and Amoéba announced a partnership to launch AXPERA, a biofungicide utilizing amoeba-derived lysate, reflecting innovation beyond conventional microbial strains and expanding the range of biological disease control tools available to growers and crop advisers worldwide, particularly in programs where resistance management and reduced residues are priorities, and expanding the toolbox for soil and foliar disease control.
- In January 2024, Certis Biologicals introduced Convergence Biofungicide, a product using Bacillus amyloliquefaciens that targets key soil-borne and foliar diseases across corn, soybeans, and peanuts, strengthening its biological portfolio for row crop growers seeking alternatives or complements to synthetic fungicides, and enabling use in both soil-borne and foliar disease management programs, supported by retail and distributor channels across major U.S. crop regions.
- In February 2023, Certis Biologicals announced that SoilGard, a biofungicide based on Trichoderma virens, would be available to growers across all 50 states through retailers and distributors, supporting disease protection for greenhouse and specialty crops with soil drench, root dip, irrigation, and direct-to-media dry granule application options, responding to market demand from growers of greenhouse and agricultural specialty crops.
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.