The global biosimilar market is experiencing growth due to increasing applications across therapeutic areas, including oncology, autoimmune diseases, inflammatory disorders, diabetes, and hematological conditions. Biosimilars are increasingly being adopted as cost-effective alternatives to reference biologic medicines, helping improve patient access to advanced treatments while reducing healthcare expenditure. Growing demand for monoclonal antibodies, insulin products, and other biologic therapies is further supporting market expansion. Additionally, patent expirations of blockbuster biologic drugs are creating opportunities for biosimilar manufacturers to introduce competitive treatment options. Advances in biotechnology, improvements in manufacturing capabilities, and supportive regulatory frameworks are encouraging product development and commercialization. Increasing acceptance among healthcare professionals, hospitals, and payers is also contributing to the broader adoption of biosimilars across healthcare systems worldwide.
Access Full Report @ https://www.databridgemarketresearch.com/reports/global-biosimilar-market
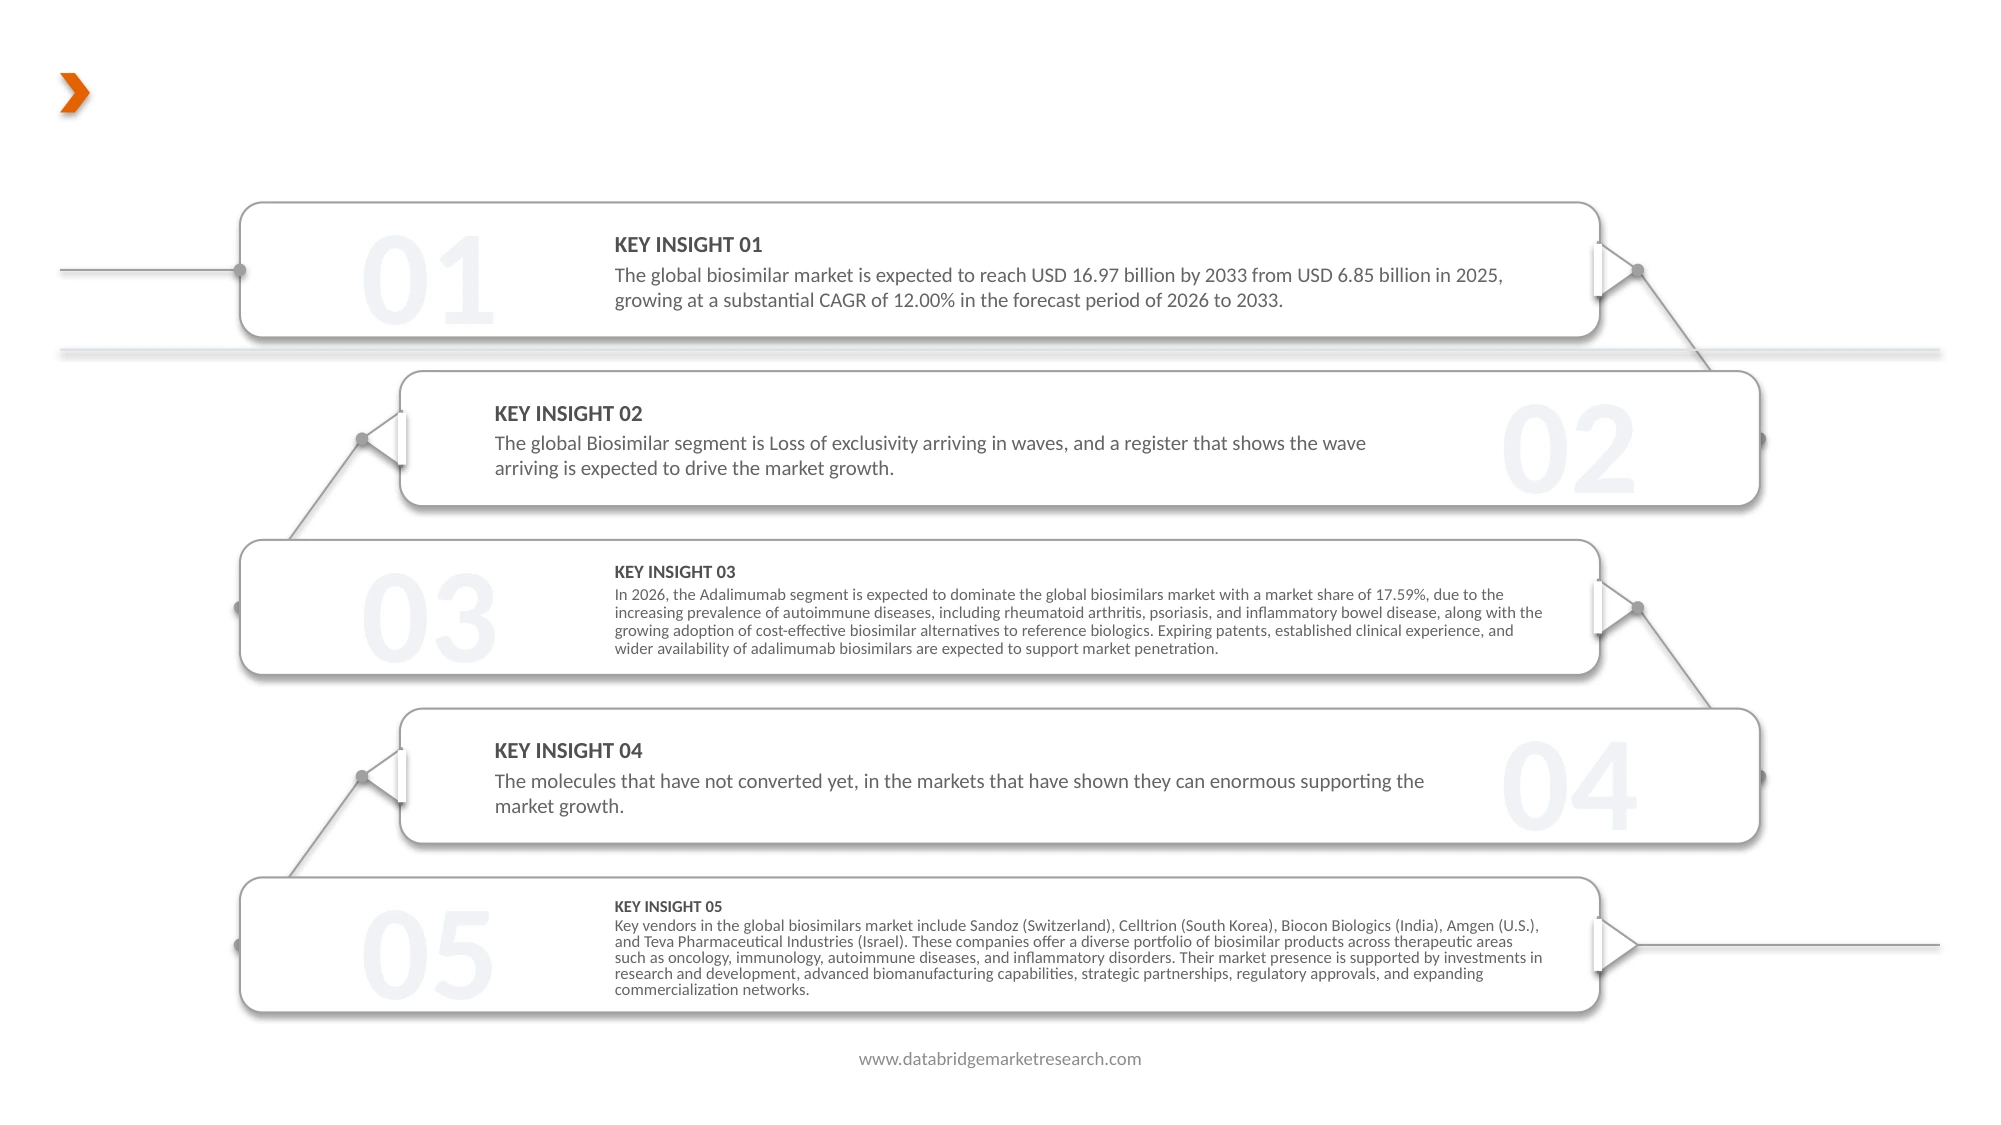
Data Bridge market research analyzes that the Global Biosimilar Market is expected to reach USD 16.97 billion by 2033 from USD 6.85 billion in 2025, growing at a substantial CAGR of 12.00% in the forecast period of 2026 to 2033.
Key Findings of the Study
Loss of Exclusivity Arriving in Waves, and a Register that Shows the Wave Arriving
Loss of exclusivity (LOE) refers to the expiration of patent protection and other market exclusivities that previously limited competition for a biologic medicine. In the global biosimilar market, LOE occurs in successive waves as patents for different high-revenue biologic drugs expire over time, creating opportunities for biosimilar manufacturers to develop and commercialize competing products. A register or LOE tracker records key information, including the reference biologic, manufacturer, patent expiration dates, regulatory exclusivity periods, therapeutic indications, and potential biosimilar entrants. This register helps companies identify when major biologics may face competition and prioritize product development, clinical studies, regulatory submissions, and commercialization strategies. By monitoring upcoming LOE events, manufacturers can anticipate competitive changes, allocate resources efficiently, and prepare for market entry. Consequently, an updated LOE register serves as a strategic planning tool for identifying future growth opportunities in the biosimilar industry.
Report Scope and Market Segmentation
|
Report Metric
|
Details
|
|
Forecast Period
|
2026 to 2033
|
|
Base Year
|
2025
|
|
Historic Years
|
2018-2024 (Customizable to 2013-2017)
|
|
Quantitative Units
|
Revenue in USD millions
|
|
Segments Covered
|
By Molecule (Denosumab, Aflibercept, Ustekinumab, Adalimumab, Pegfilgrastim, Bevacizumab, Ranibizumab, Trastuzumab, Filgrastim, Rituximab, Teriparatide, Etanercept, Tocilizumab, Epoetin alfa, Infliximab, Insulin aspart, Insulin glargine, Eculizumab, Epoetin zeta, Follitropin alfa, Golimumab, Insulin lispro, Enoxaparin sodium, Natalizumab, Omalizumab, Pertuzumab, Somatropin), By Therapeutic Group (Immunology and Inflammation, Oncology, Ophthalmology, Haematology and Supportive Care, Bone and Metabolic, Diabetes, Endocrinology and Fertility, Respiratory and Allergy), By Market Status (Marketed, Approved not launched, Filed, Not present, Not known), By Channel (Public tender, Hospital, Retail pharmacy, Private market)
|
|
Countries Covered
|
Germany, France, Italy, Spain, U.K., Brazil, Mexico, Argentina, Colombia, Chile, China, Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Saudi Arabia, U. A. E., Egypt, Turkey
|
|
Market Players Covered
|
|
|
Data Points Covered in the Report
|
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, patient epidemiology, pipeline analysis, pricing analysis, and regulatory framework.
|
Segment Analysis
The global biosimilar market is segmented into four notable segments based on molecule, therapeutic group, market status, channel.
- On the basis of molecule, the global biosimilar market is segmented into denosumab, aflibercept, ustekinumab, adalimumab, pegfilgrastim, bevacizumab, ranibizumab, trastuzumab, filgrastim, rituximab, teriparatide, etanercept, tocilizumab, epoetin alfa, infliximab, insulin aspart, insulin glargine, eculizumab, epoetin zeta, follitropin alfa, golimumab, insulin lispro, enoxaparin sodium, natalizumab, omalizumab, pertuzumab, and somatropin.
In 2026, the adalimumab segment is expected to dominate the market
In 2026, the adalimumab segment is expected to dominate the global biosimilar market due to its widespread use in treating autoimmune and inflammatory conditions, including rheumatoid arthritis, psoriasis, psoriatic arthritis, Crohn’s disease, and ulcerative colitis. The availability of multiple biosimilar versions of the reference biologic Humira is intensifying competition and improving access to cost-effective treatment options.
- On the basis of therapeutic group, the global biosimilar market is segmented into immunology and inflammation, oncology, ophthalmology, haematology and supportive care, bone and metabolic, diabetes, endocrinology and fertility, and respiratory and allergy.
In 2026, the immunology and inflammation segment is expected to dominate the market
In 2026, the immunology and inflammation segment is expected to dominate the global biosimilars market due to the rising prevalence of autoimmune and chronic inflammatory diseases, including rheumatoid arthritis, psoriasis, Crohn’s disease, and ulcerative colitis. The growing use of biologic therapies, such as adalimumab, infliximab, and etanercept, is supporting demand for biosimilars across these indications.
- On the basis of market status, the global biosimilar market is segmented into marketed, approved not launched, filed, not present, and not known.
In 2026, the marketed segment is expected to dominate the market
In 2026, the marketed segment is expected to dominate the global biosimilars market due to the established commercial availability of approved biosimilar products and their increasing adoption across hospitals, specialty clinics, and healthcare systems. These products have completed the required regulatory assessments to demonstrate similarity to reference biologic medicines in terms of quality, safety, and efficacy, supporting their use in approved indications.
- On the basis of channel, the global biosimilar market is segmented into public tender, hospital, retail pharmacy, and private market.
In 2026, the hospital segment is expected to dominate the market
In 2026, the hospital segment is expected to dominate the global biosimilars market due to the widespread use of biologic therapies in hospital settings, particularly for oncology, immunology, and inflammatory diseases. Hospitals provide specialized facilities, trained healthcare professionals, and appropriate infrastructure for administering injectable and intravenous biosimilars that require medical supervision and patient monitoring.
Major Players
Sandoz (Switzerland), Celltrion (South Korea), Biocon Biologics (India) , Biocon BiologicsAmgen (U.S.), Teva Pharmaceutical Industries (Israel), among others are the major players dealing in the market.
Regional Analysis
Geographically, the country covered in the global biosimilars market report is Germany, France, Italy, Spain, U.K., Brazil, Mexico, Argentina, Colombia, Chile, China, Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Saudi Arabia, U. A. E., Egypt, Turkey
As per Data Bridge Market Research analysis:
Europe is the dominant region in the global biosimilars market
Europe is a leading region in the global biosimilars market, supported by its well-established regulatory framework, extensive history of biosimilar adoption, and strong pharmaceutical manufacturing capabilities. The European Medicines Agency (EMA) approved the first biosimilar in 2006, giving the region a longstanding foundation for product development, commercialization, and clinical acceptance. Increasing demand for cost-effective biologic therapies, patent expirations of major biologic medicines, and supportive healthcare policies are further encouraging biosimilar uptake across oncology, immunology, and inflammatory diseases. Additionally, established reimbursement systems, growing competition among manufacturers, and efforts to improve patient access to advanced treatments are supporting regional market development.
Southeast Asia is estimated to be the fastest-growing region in the global biosimilars market
Southeast Asia is estimated to be the fastest-growing region in the global biosimilars market, driven by increasing demand for affordable biologic therapies, rising prevalence of chronic diseases, and expanding healthcare access across emerging economies. Countries such as Indonesia, Thailand, Vietnam, and the Philippines are creating growth opportunities as healthcare infrastructure improves and demand for treatments for cancer, autoimmune disorders, and inflammatory diseases increases. Government initiatives to strengthen domestic pharmaceutical manufacturing, improve access to advanced medicines, and encourage biotechnology investments are further supporting market development. Additionally, collaborations between regional pharmaceutical companies and international biopharmaceutical manufacturers, along with evolving regulatory frameworks, are expected to accelerate biosimilar development and adoption. However, differences in reimbursement policies, regulatory requirements, and physician awareness continue to influence the pace of regional growth.
Market Developments
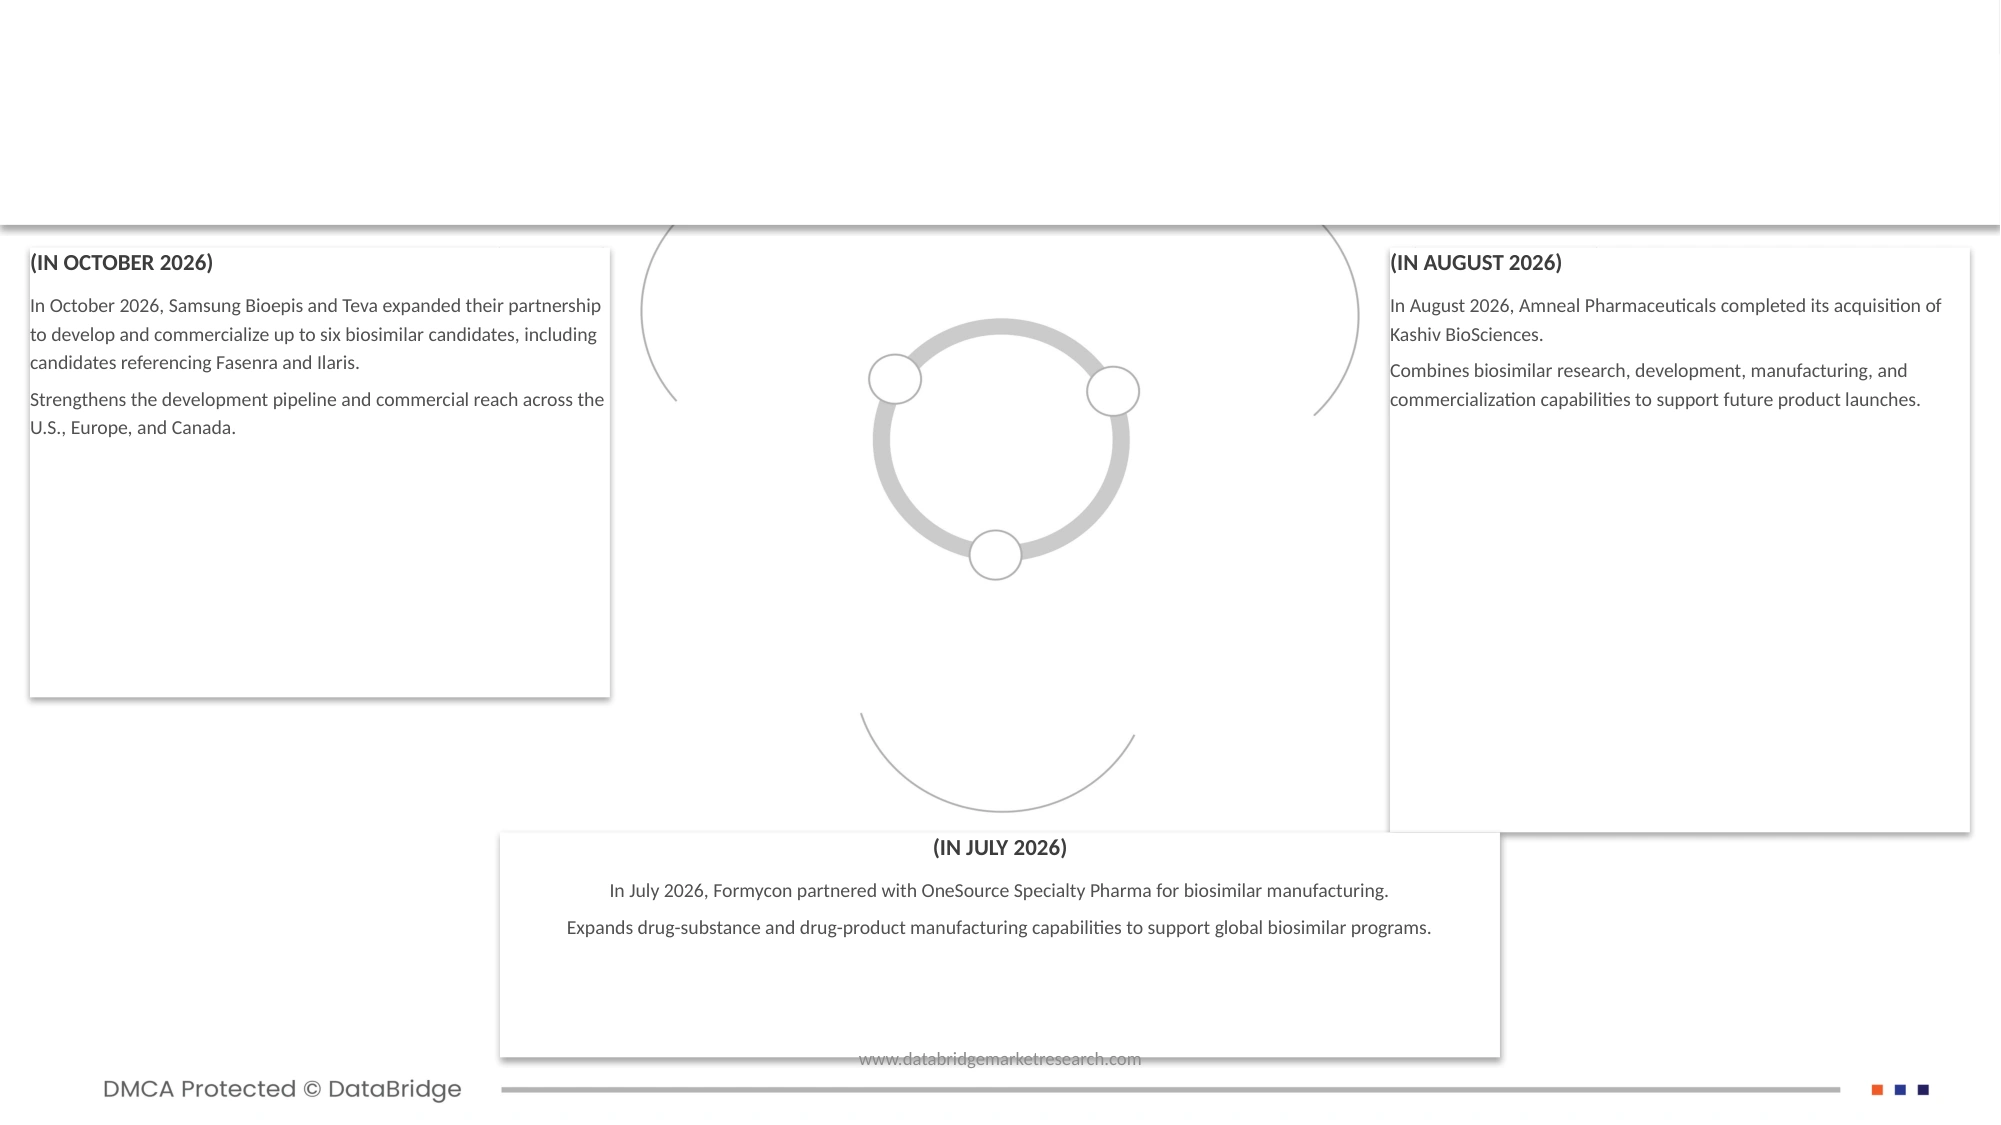
- In October 2026, Samsung Bioepis and Teva expanded their partnership to develop and commercialize up to six biosimilar candidates, including candidates referencing Fasenra and Ilaris. Strengthens the development pipeline and commercial reach across the U.S., Europe, and Canada.
- In August 2026, Amneal Pharmaceuticals completed its acquisition of Kashiv BioSciences. Combines biosimilar research, development, manufacturing, and commercialization capabilities to support future product launches.
- In July 2026, Formycon partnered with OneSource Specialty Pharma for biosimilar manufacturing. Expands drug-substance and drug-product manufacturing capabilities to support global biosimilar programs.
- In May 2026, Formycon and Klinge Biopharma launched the aflibercept biosimilar products Ahzantive and Baiama in the EU, with initial rollouts in Germany, France, and Italy. Expands competition in ophthalmology and provides additional treatment options for retinal diseases.
- In March 2026, Samsung Bioepis partnered with Sandoz to develop and commercialize up to five biosimilar candidates, including a vedolizumab candidate referencing Entyvio. Strengthens the biosimilar pipeline in immunology and supports broader commercialization across global markets.
As per Data Bridge Market Research analysis:
For more detailed information about the Global biosimilars market report, click here – https://www.databridgemarketresearch.com/reports/global-biosimilar-market