What is the Companion Radiodiagnostics Market Size and Growth Rate?
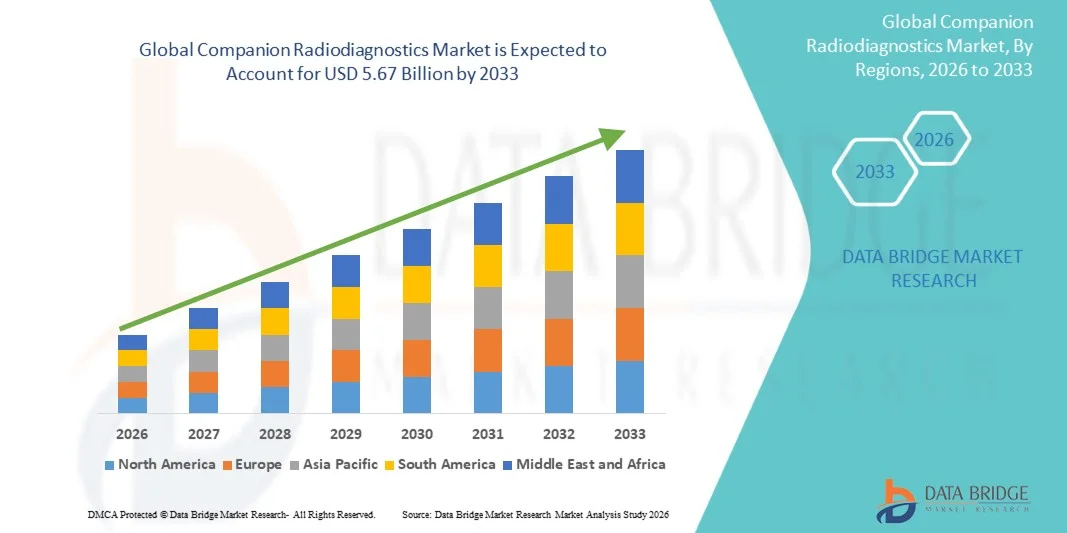
- As per Data Bridge Market Research analysis, the companion radiodiagnostics market was valued at USD 2.48 billion in 2025 and is projected to reach USD 5.67 billion by 2033, growing at a CAGR of 10.90% from 2026 to 2033.
- The market is experiencing consistent growth driven by rising demand for personalized medicine, increasing adoption of companion diagnostics in oncology, and rapid advancements in molecular imaging and radiopharmaceutical technologies.
- The increasing prevalence of cancer globally, combined with the growing need for precise patient selection and targeted treatment, is compelling pharmaceutical companies, diagnostic providers, and healthcare institutions to adopt advanced companion radiodiagnostic solutions. PET and SPECT-based imaging technologies are increasingly being integrated with targeted therapies, enabling more accurate disease characterization, treatment selection, and monitoring while supporting the development of personalized treatment strategies.
Market Size & Forecast
- Global Market Value (2025): USD 2.48 Billion
- Expected Market Value (2033): USD 5.67 Billion
- Forecast CAGR (2026–2033): 10.90%
- Leading Region in 2025: North America
- Fastest Growing Region: Asia Pacific
What are the Major Takeaways of the Companion Radiodiagnostics Market?
- North America dominated the companion radiodiagnostics market with the largest revenue share of 39.9% in 2025, supported by advanced healthcare infrastructure, increasing adoption of precision medicine, rising prevalence of cancer and chronic diseases, and strong regulatory support for targeted therapies.
- Asia-Pacific is expected to be the fastest-growing region at a CAGR of 12.5% from 2026 to 2033, fueled by increasing healthcare investments, rising adoption of advanced diagnostic technologies, growing cancer burden, and expanding precision medicine initiatives across China, Japan, India, and South Korea.
- The assays, kits & reagents segment led the market with a 55.0% share in 2025, driven by increasing demand for biomarker detection, molecular testing, and patient stratification solutions.
- Software & services are the fastest-growing product & services type, projected to register a CAGR of 12.4%, reflecting the surge in adoption of digital pathology, AI-based imaging analysis, and advanced diagnostic data interpretation.
- The polymerase chain reaction (PCR) segment dominated the technology category with a 30.0% revenue share in 2025, led by its high sensitivity, specificity, and established use in molecular diagnostics
- Positron emission tomography (PET) accounted for 40.0% of the market share in 2025, preferred by increasing use of molecular imaging for disease characterization and treatment selection.
- The neurological disorders segment is the fastest-growing indication category, with a CAGR of 13.5%, driven by increasing demand for advanced imaging biomarkers and early disease detection.
Report Scope and Companion Radiodiagnostics Market Segmentation
|
Attributes |
Companion Radiodiagnostics Key Market Insights |
|
Segments Covered |
|
|
Countries Covered |
North America
Europe
Asia-Pacific
Middle East and Africa
South America
|
|
Key Market Players |
|
|
Market Opportunities |
|
|
Value Added Data Infosets |
In addition to the insights on market scenarios such as market value, growth rate, segmentation, geographical coverage, and major players, the market reports curated by the Data Bridge Market Research also include in-depth expert analysis, patient epidemiology, pipeline analysis, pricing analysis, and regulatory framework. |
What is the Key Trend in the Companion Radiodiagnostics Market?
- Companion radiodiagnostics is increasingly shifting toward molecular imaging and theranostics, enabling clinicians to identify biomarker expression, select suitable patients, and monitor targeted radiopharmaceutical therapies through non-invasive imaging across oncology applications.
- For instance, in June 2025, Siemens Healthineers announced a theranostics research collaboration with Massachusetts General Hospital, establishing a Therapy Command Center using advanced PET/CT imaging to determine appropriate treatment pathways for individual patients.
- Advanced PET imaging enables physicians to visualize tumor heterogeneity, molecular targets, and treatment response, strengthening the role of imaging biomarkers in personalized treatment selection and supporting more precise disease characterization during clinical decision-making processes.
- Pharmaceutical companies and radiopharmaceutical developers are increasingly integrating companion imaging into clinical development programs to identify treatment-responsive populations, evaluate diagnostic performance, and support targeted oncology therapies using molecularly specific imaging agents.
- For instance, in April 2025, Radiopharm Theranostics dosed the first patient in a U.S. Phase 2b study of 18F-RAD101, evaluating diagnostic performance in suspected recurrent brain metastases from solid tumors.
- As precision oncology increasingly depends on accurate biomarker characterization and patient stratification, adoption of molecular imaging, PET-based radiogenomics, and theranostic approaches is expected to accelerate, reinforcing companion radiodiagnostics within personalized cancer care.
What are the Key Drivers of the Companion Radiodiagnostics Market?
- The rising prevalence of cancer and increasing adoption of precision oncology are significantly increasing demand for imaging-based companion diagnostics capable of identifying molecular targets, stratifying patients, and guiding targeted treatment decisions across complex cancer populations.
- For instance, in April 2025, Radiopharm Theranostics initiated a Phase 2b U.S. imaging study involving 30 patients to evaluate 18F-RAD101 for suspected recurrent brain metastases, highlighting expanding clinical development of oncology radiodiagnostics.
- Pharmaceutical companies, healthcare providers, and imaging developers are increasingly integrating companion radiodiagnostics with targeted radiopharmaceutical therapies to improve patient selection, treatment monitoring, and therapeutic decision-making while supporting personalized cancer management.
- For instance, in November 2025, Siemens Healthineers reported operating 60 PET radiopharmaceutical facilities across nine countries, manufacturing more than 100,000 batches annually and supporting PET imaging for oncology and theranostic applications.
- With molecular imaging increasingly supporting biomarker assessment, treatment selection, and response monitoring, companion radiodiagnostics will remain important for expanding precision medicine and improving clinical outcomes across targeted oncology and radiopharmaceutical therapies.
What Factors are Challenging the Growth of the Companion Radiodiagnostics Market?
- Companion radiodiagnostics faces significant regulatory complexity because imaging tools must demonstrate analytical performance, clinical validity, and therapeutic relevance, increasing development requirements and potentially extending approval timelines for innovative diagnostic technologies.
- For instance, in March 2025, Clinical Cancer Research reported that companion diagnostic regulations create increasing complexity and cost burdens, while expensive diagnostic tests and reimbursement challenges can become roadblocks to clinical adoption.
- These regulatory requirements can increase development costs and create accessibility challenges, particularly when pharmaceutical companies and diagnostic developers must coordinate evidence generation, regulatory submissions, reimbursement strategies, and clinical implementation across multiple healthcare systems.
- For instance, in September 2024, the OECD reported that fewer than half of surveyed countries automatically link reimbursement of companion diagnostics to reimbursement of the corresponding medicine, noting that this lack of integrated reimbursement can slow personalized-medicine adoption and create additional financial burdens for patients
- The regulatory burden, reimbursement uncertainty, and high costs associated with developing and implementing companion radiodiagnostics continue to restrict adoption, particularly where imaging infrastructure and specialized molecular diagnostic capabilities remain limited. These barriers slow broader market penetration.
How is the Companion Radiodiagnostics Market Segmented?
The companion radiodiagnostics market is segmented on the basis of product & services, technology, radiodiagnostic modality, indication, and end user.
- By Product & Services
On the basis of product & services, the companion radiodiagnostics market is segmented into assays, kits & reagents, instruments & systems, and software & services. The assays, kits & reagents segment dominated the market with 55.0% share in 2025, owing to increasing demand for biomarker detection, molecular testing, and patient stratification solutions. These products are extensively used alongside targeted therapies to identify patients most likely to benefit from specific treatments. Growing adoption of personalized medicine is increasing the recurring demand for diagnostic assays and reagents. Pharmaceutical and biotechnology companies are also integrating these products into clinical trials and drug-development programs. Increasing cancer prevalence and expansion of precision oncology are further strengthening demand.
The software & services segment is projected to register the fastest growth at a CAGR of 12.4% from 2026 to 2033, driven by increasing adoption of digital pathology, AI-based imaging analysis, and advanced diagnostic data interpretation. These solutions help healthcare providers analyze complex molecular and imaging information more efficiently. Integration of AI and machine learning is improving biomarker interpretation and supporting personalized treatment decisions. Cloud-based platforms are also enabling secure data sharing between laboratories, hospitals, pharmaceutical companies, and research organizations. Increasing demand for automated workflows is further encouraging adoption.
- By Technology
On the basis of technology, the companion radiodiagnostics market is segmented into polymerase chain reaction (PCR), next-generation sequencing (NGS), immunohistochemistry (IHC), in-situ hybridization (ISH), magnetic resonance imaging (MRI), and other technologies. The polymerase chain reaction (PCR) segment dominated the market with 30.0% share in 2025, supported by its high sensitivity, specificity, and established use in molecular diagnostics. PCR enables the detection of specific genetic biomarkers associated with targeted therapies. Its relatively rapid turnaround time makes it suitable for routine clinical testing. Diagnostic laboratories widely use PCR because of its established workflows and compatibility with automated systems. Increasing demand for biomarker testing in oncology is further supporting adoption.
The next-generation sequencing (NGS) segment is expected to witness the fastest growth at a CAGR of 15.7% from 2026 to 2033, driven by increasing demand for comprehensive genomic profiling and precision medicine. NGS can simultaneously identify multiple genetic alterations, making it valuable for complex patient stratification. Growing adoption of targeted therapies is increasing the need for detailed genomic information. Pharmaceutical companies are increasingly incorporating NGS into clinical trials and companion diagnostic development. Technological improvements are increasing sequencing speed while reducing testing costs. Expanding genomic databases and bioinformatics capabilities are further supporting adoption. These factors are positioning NGS as an increasingly important technology for personalized treatment selection.
- By Radiodiagnostic Modality
On the basis of radiodiagnostic modality, the companion radiodiagnostics market is segmented into magnetic resonance imaging (MRI), computed tomography (CT), positron emission tomography (PET), single photon emission computed tomography (SPECT), and other imaging modalities. The positron emission tomography (PET) segment dominated the market with 40.0% share in 2025, driven by increasing use of molecular imaging for disease characterization and treatment selection. PET enables visualization of biological processes and molecular targets within the body. Its strong application in oncology is supporting widespread adoption in companion radiodiagnostic workflows. Increasing use of targeted radiopharmaceuticals is further strengthening demand for PET-based imaging. PET also supports treatment monitoring by helping physicians evaluate changes in disease activity.
The magnetic resonance imaging (MRI) segment is projected to register the fastest growth at a CAGR of 10.2% from 2026 to 2033, supported by increasing demand for high-resolution, non-invasive disease characterization. MRI provides detailed anatomical and functional information without exposure to ionizing radiation. Increasing adoption in oncology and neurological disorders is expanding its role in advanced diagnostic assessment. AI-enabled MRI analysis is improving image interpretation and workflow efficiency. Development of quantitative imaging biomarkers is creating additional opportunities for personalized diagnosis and treatment monitoring. Healthcare providers are increasingly investing in advanced MRI infrastructure. These developments are expected to support sustained growth of MRI-based companion radiodiagnostic applications.
- By Indication
On the basis of indication, the companion radiodiagnostics market is segmented into oncology, infectious diseases, cardiovascular diseases, neurological disorders, and other indications. The oncology segment dominated the market with 55.0% share in 2025, supported by the increasing prevalence of cancer and growing adoption of precision oncology. Companion radiodiagnostics help identify molecular characteristics of tumors and support selection of appropriate targeted treatments. PET and other molecular imaging approaches are increasingly used for tumor characterization and treatment monitoring. Growing availability of targeted cancer therapies is increasing the need for accurate patient stratification. Pharmaceutical companies are also investing heavily in oncology-focused diagnostic development.
The neurological disorders segment is expected to witness the fastest growth at a CAGR of 13.5% from 2026 to 2033, driven by increasing demand for advanced imaging biomarkers and early disease detection. Molecular imaging technologies are increasingly being investigated for neurological conditions such as Alzheimer’s disease and Parkinson’s disease. Improved visualization of disease-related biological changes is supporting more precise diagnosis and monitoring. Growing research into neurodegenerative biomarkers is expanding clinical applications. AI-based image analysis is also improving interpretation of complex neurological imaging data. An aging population and increasing burden of neurological disorders are supporting demand. Expansion of personalized approaches to neurological care is expected to further accelerate segment growth.
- By End User
On the basis of end user, the companion radiodiagnostics market is segmented into hospitals & physician laboratories, diagnostic laboratories, reference laboratories, academic & research centers, contract research organizations (CROs), pharmaceutical & biotechnology companies, and other end users. The pharmaceutical & biotechnology companies segment dominated the market with 35.0% share in 2025, driven by increasing integration of companion diagnostics into targeted drug development and clinical trials. These companies use companion radiodiagnostics to identify appropriate patient populations and evaluate treatment response. Growing emphasis on precision medicine is increasing demand for diagnostic solutions during drug development. Collaborations between pharmaceutical companies and diagnostic developers are supporting new product development. Companion diagnostics can improve patient selection and strengthen clinical trial efficiency.
The academic & research centers segment is projected to register the fastest growth at a CAGR of 13.5% from 2026 to 2033, driven by increasing research into molecular imaging, biomarkers, and personalized medicine. Academic institutions are increasingly adopting advanced imaging technologies to investigate disease mechanisms and treatment response. Growing collaboration between universities, hospitals, pharmaceutical companies, and diagnostic developers is supporting innovation. Research centers are also playing an important role in validating new imaging biomarkers and radiodiagnostic technologies. Increasing funding for precision medicine and translational research is strengthening adoption. Expansion of clinical research involving molecular imaging is creating additional demand. These factors are expected to make academic and research centers an increasingly important end-user segment.
Which Region Holds the Largest Share of the Companion Radiodiagnostics Market?
- North America dominated the companion radiodiagnostics market with the largest revenue share of 39.9% in 2025, supported by advanced healthcare infrastructure, increasing adoption of precision medicine, rising prevalence of cancer and chronic diseases, and strong regulatory support for targeted therapies.
- The region also benefits from favorable regulatory frameworks, increasing adoption of AI-enabled imaging technologies, strong pharmaceutical and biotechnology research capabilities, and growing investments in targeted therapies and radiopharmaceutical development. Rising demand for biomarker-based diagnostics and personalized treatment strategies continues to strengthen North America’s leadership position in the global market.
U.S. Companion Radiodiagnostics Market Insight
The U.S. companion radiodiagnostics market is witnessing strong growth due to increasing adoption of precision medicine, molecular imaging, and targeted treatment strategies. The country’s advanced healthcare infrastructure, strong pharmaceutical and biotechnology ecosystem, and increasing utilization of PET-based imaging biomarkers are driving demand across oncology and personalized healthcare applications. In addition, increasing regulatory support for radiopharmaceutical imaging agents and companion diagnostic technologies is accelerating market adoption across hospitals, research institutions, and pharmaceutical companies.
Asia-Pacific Companion Radiodiagnostics Market Insight
The Asia-Pacific companion radiodiagnostics market is expected to witness rapid growth, driven by rising cancer prevalence, expanding healthcare infrastructure, and increasing investments in precision medicine across countries such as China, Japan, and India. Growing adoption of PET imaging, radiopharmaceutical technologies, and biomarker-based diagnostic approaches is supporting demand across hospitals, pharmaceutical companies, and research institutes. In addition, increasing healthcare investments, technological advancements, and expanding personalized medicine initiatives are accelerating the adoption of companion radiodiagnostics throughout the region.
Japan Companion Radiodiagnostics Market Insight
The Japan companion radiodiagnostics market is witnessing consistent growth due to the country’s advanced healthcare system, aging population, and increasing focus on precision medicine and innovative cancer therapies. Hospitals, pharmaceutical companies, and research institutes are increasingly adopting molecular imaging, PET-based diagnostics, and biomarker-driven approaches for treatment selection and disease monitoring. Moreover, growing investments in radiopharmaceutical research and theranostics, along with Japan’s strong technological capabilities, are further contributing to market development.
China Companion Radiodiagnostics Market Insight
The China companion radiodiagnostics market is growing rapidly, driven by increasing cancer burden, expanding precision medicine programs, and rising investments in advanced diagnostic imaging infrastructure. Growing adoption of PET imaging, radiopharmaceutical development, and biomarker-based treatment strategies across major hospitals is significantly boosting market demand. In addition, government initiatives supporting healthcare modernization, innovative drug development, and domestic biotechnology are strengthening the adoption of companion radiodiagnostics and positioning China as a key growth market in the region.
U.K. Companion Radiodiagnostics Market Insight
The U.K. companion radiodiagnostics market is experiencing steady growth, supported by increasing adoption of precision oncology, molecular imaging technologies, and personalized healthcare approaches. The country’s strong clinical research ecosystem, NHS infrastructure, and growing focus on biomarker-driven treatment decisions are contributing to wider implementation of advanced diagnostic solutions. Furthermore, increasing investments in radiopharmaceutical research, genomic medicine, and AI-enabled imaging technologies are improving diagnostic capabilities and supporting market expansion.
Germany Companion Radiodiagnostics Market Insight
The Germany companion radiodiagnostics market is expanding steadily due to the country’s advanced healthcare infrastructure, strong pharmaceutical industry, and growing adoption of molecular imaging technologies. Hospitals, research organizations, and biotechnology companies are increasingly utilizing PET-based diagnostics, imaging biomarkers, and precision medicine solutions, particularly for oncology applications. Continuous investments in radiopharmaceutical research, digital healthcare, and personalized medicine, together with Germany’s strong clinical research capabilities, are further driving market growth.
Which are the Top Companies in Companion Radiodiagnostics Market?
The companion radiodiagnostics industry is primarily led by well-established companies, including:
- GE HealthCare (U.S.)
- Siemens Healthineers AG (Germany)
- Lantheus (U.S.)
- Bracco (Italy)
- Novartis AG (Switzerland)
- Bayer AG (Germany)
- Cardinal Health, Inc. (U.S.)
- Thermo Fisher Scientific Inc. (U.S.)
- Danaher Corporation (U.S.)
- Revvity, Inc. (U.S.)
- Telix Pharmaceuticals Limited (Australia)
- Eckert & Ziegler SE (Germany)
- Jubilant Radiopharma (U.S.)
- RadioMedix, Inc. (U.S.)
- IONETIX Corporation (U.S.)
- NTP Radioisotopes SOC Ltd (South Africa)
- Koninklijke Philips N.V. (Netherlands)
- Hologic, Inc. (U.S.)
- United Imaging Healthcare Co., Ltd. (China)
- ESAOTE S.p.A. (Italy)
What are Latest Developments in Companion Radiodiagnostics Market?
- In June 2025, GE HealthCare announced that the U.S. FDA had approved an updated label for Vizamyl (flutemetamol F 18 injection), expanding its PET imaging applications for beta-amyloid detection. The updated label introduced quantitative assessment of amyloid burden and enabled clinicians to monitor patient response to anti-amyloid therapies, supporting more precise diagnosis, treatment selection, and therapy monitoring for Alzheimer’s disease. This development strengthens the role of PET-based companion radiodiagnostics in personalized neurological care.
- In February 2025, GE HealthCare announced that the first U.S. patients had received doses of Flyrcado (flurpiridaz F 18 injection), its FDA-approved PET radiotracer for myocardial perfusion imaging. The radiotracer was introduced at early-adopter imaging centers to support the detection of coronary artery disease and provide clinicians with a ready-to-use PET imaging option. The development expands the application of molecular imaging beyond oncology into cardiovascular disease diagnosis.
- In December 2024, Siemens Healthineers completed the acquisition of Advanced Accelerator Applications Molecular Imaging from Novartis, expanding its PET radiopharmaceutical manufacturing and distribution network in Europe. The acquisition added manufacturing sites and strengthened Siemens Healthineers’ capabilities in diagnostic radiopharmaceuticals for PET imaging, supporting applications in cancer, cardiovascular disease, and neurological disorders. The development also strengthens the infrastructure required for radiopharmaceutical-based personalized medicine and theranostics.
- In September 2022, GE HealthCare and Lantheus announced positive Phase III results for the investigational flurpiridaz F 18 PET radiotracer for coronary artery disease detection. The study met its co-primary endpoints for sensitivity and specificity and demonstrated higher diagnostic efficacy compared with SPECT myocardial perfusion imaging. The development supported continued advancement of PET-based cardiac radiodiagnostics and expanded the potential use of molecular imaging for cardiovascular disease assessment.
- In March 2022, Novartis announced FDA approval of Pluvicto as the first targeted radioligand therapy for progressive PSMA-positive metastatic castration-resistant prostate cancer, alongside approval of the complementary diagnostic imaging agent Locametz. Locametz enables PET identification of PSMA-positive lesions and helps identify patients who may be eligible for PSMA-targeted radioligand treatment. This development marked an important advancement in companion radiodiagnostics by directly linking molecular imaging-based patient selection with targeted radiopharmaceutical therapy
- Interactive Data Analysis Dashboard
- Company Analysis Dashboard for high growth potential opportunities
- Research Analyst Access for customization & queries
- Competitor Analysis with Interactive dashboard
- Latest News, Updates & Trend analysis
- Harness the Power of Benchmark Analysis for Comprehensive Competitor Tracking
Data collection and base year analysis are done using data collection modules with large sample sizes. The stage includes obtaining market information or related data through various sources and strategies. It includes examining and planning all the data acquired from the past in advance. It likewise envelops the examination of information inconsistencies seen across different information sources. The market data is analysed and estimated using market statistical and coherent models. Also, market share analysis and key trend analysis are the major success factors in the market report. To know more, please request an analyst call or drop down your inquiry.
The key research methodology used by DBMR research team is data triangulation which involves data mining, analysis of the impact of data variables on the market and primary (industry expert) validation. Data models include Vendor Positioning Grid, Market Time Line Analysis, Market Overview and Guide, Company Positioning Grid, Patent Analysis, Pricing Analysis, Company Market Share Analysis, Standards of Measurement, Global versus Regional and Vendor Share Analysis. To know more about the research methodology, drop in an inquiry to speak to our industry experts.
Data Bridge Market Research is a leader in advanced formative research. We take pride in servicing our existing and new customers with data and analysis that match and suits their goal. The report can be customized to include price trend analysis of target brands understanding the market for additional countries (ask for the list of countries), clinical trial results data, literature review, refurbished market and product base analysis. Market analysis of target competitors can be analyzed from technology-based analysis to market portfolio strategies. We can add as many competitors that you require data about in the format and data style you are looking for. Our team of analysts can also provide you data in crude raw excel files pivot tables (Fact book) or can assist you in creating presentations from the data sets available in the report.